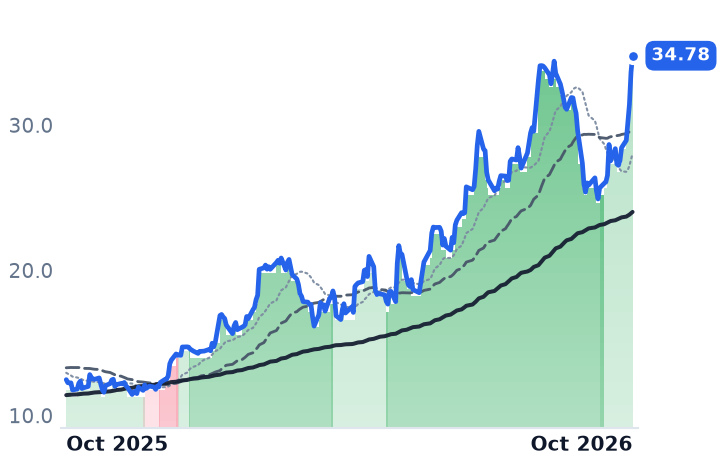
American Frac Work Is Growing, Yet Halliburton Fell Further Than Liberty Energy
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
The oilfield service complex was sold through late September as though American completion work were drying up. Primary Vision's frac spread count says otherwise: 196 active spreads on 2 October, seventeen more than a year earlier, and the Dallas Fed's index of prices received for oilfield services turned positive in the third quarter.
Halliburton, whose international revenue of $3.4bn was its highest for any second quarter in more than a decade, fell harder over the past month than Liberty Energy, which pumps only American wells. The quarters explain neither drop: Halliburton grew revenue and operating income and now trades at 14.0x forward earnings against 23.1x trailing in May, while Liberty's gross profit more than doubled.
ProPetro is the one name whose discount is earned, still loss-making with price-to-gross-profit at 12.2x against 7.1x in May.
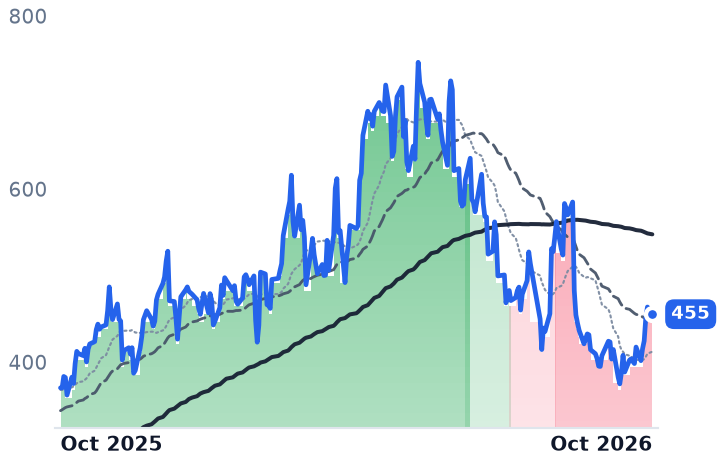
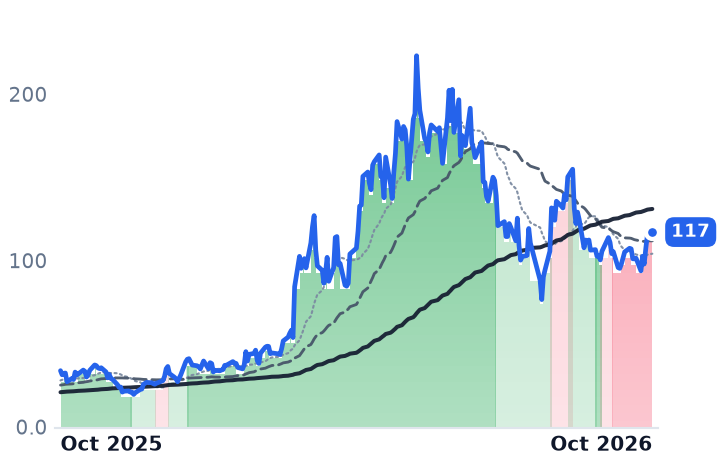
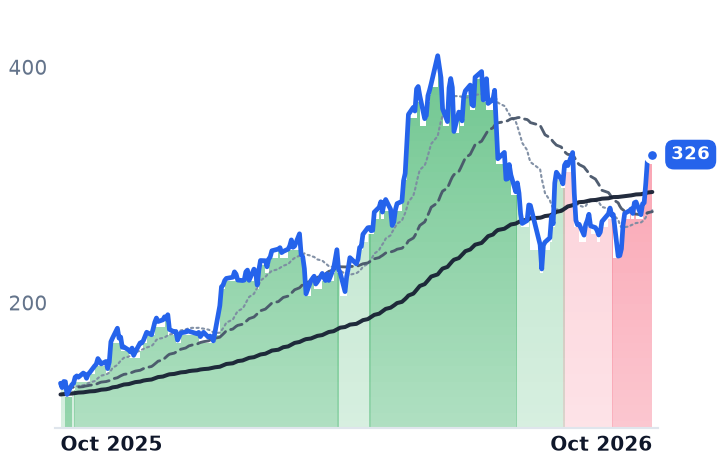
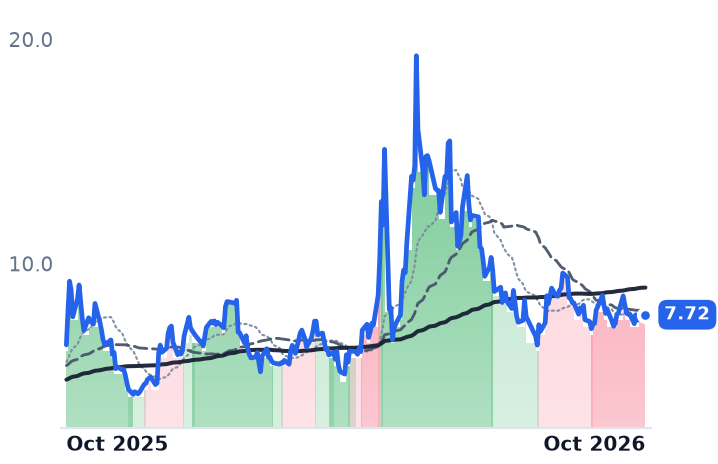
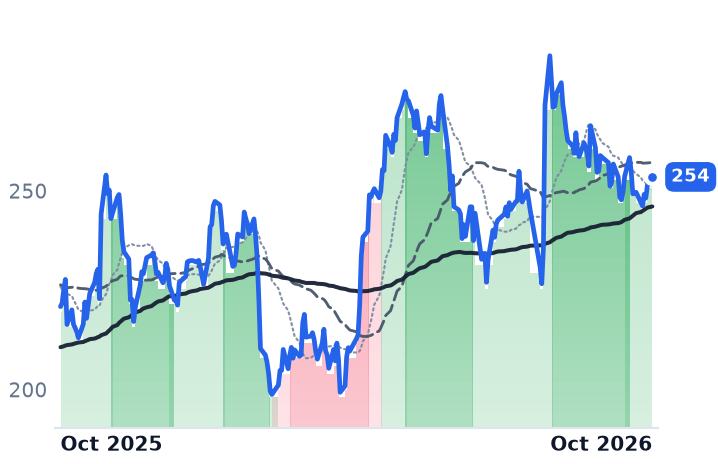
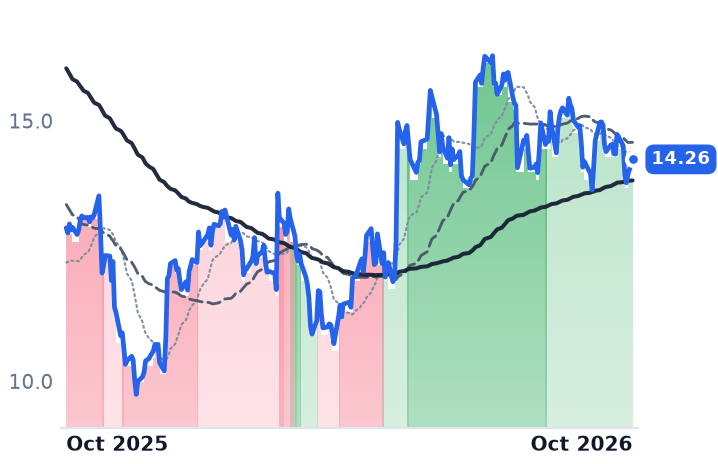
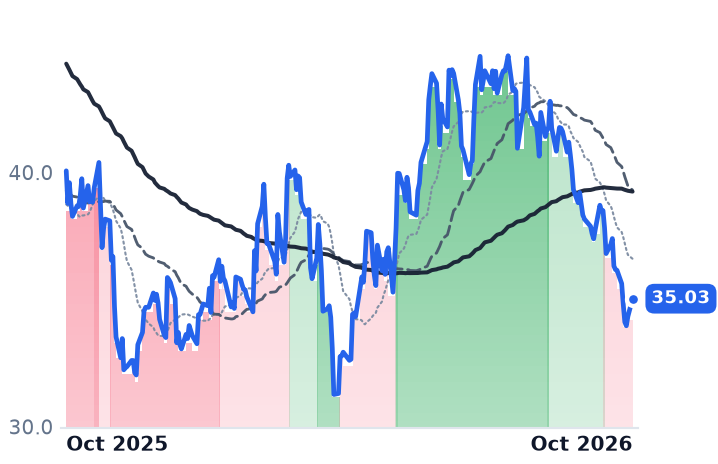
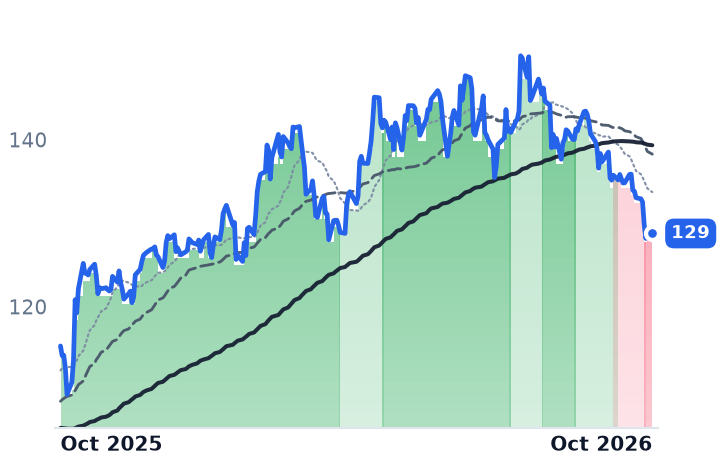
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
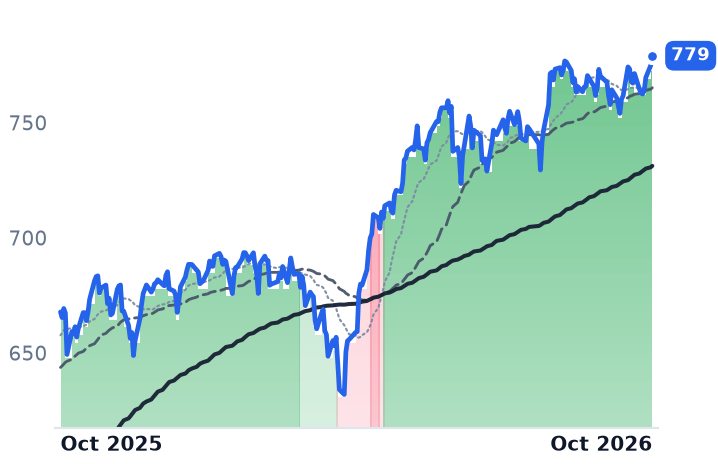
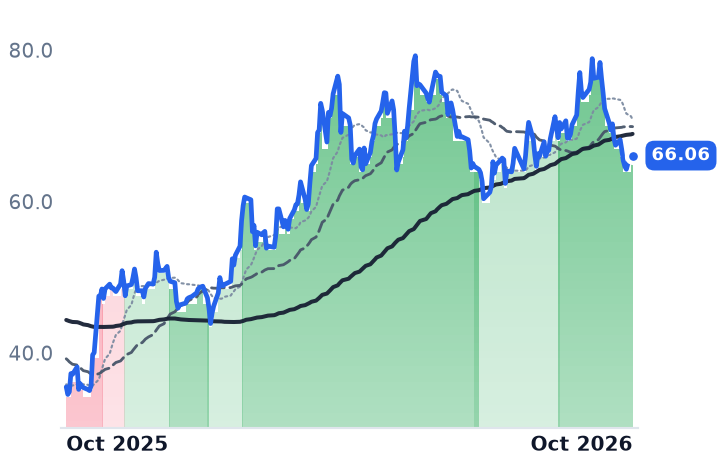
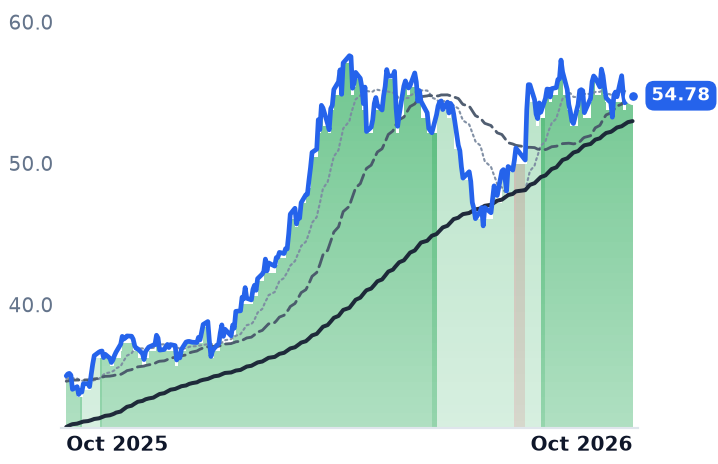
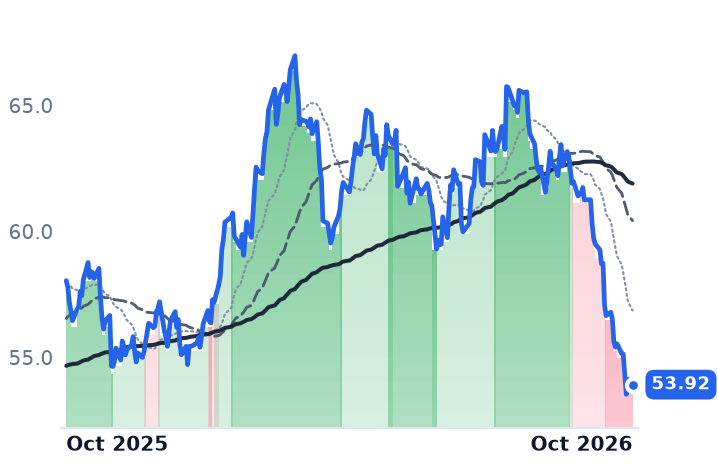
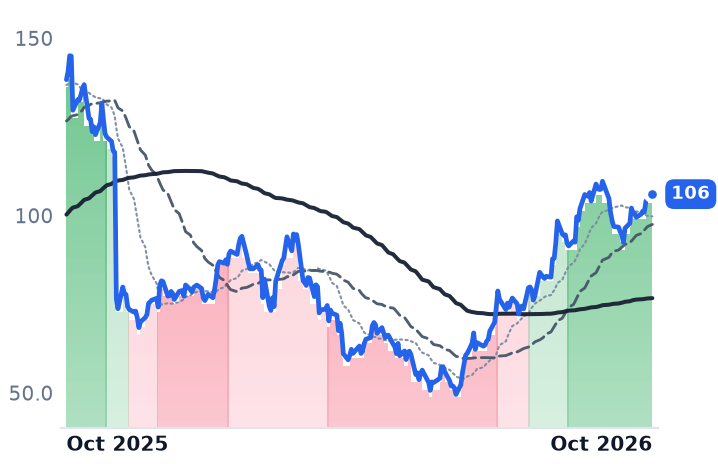
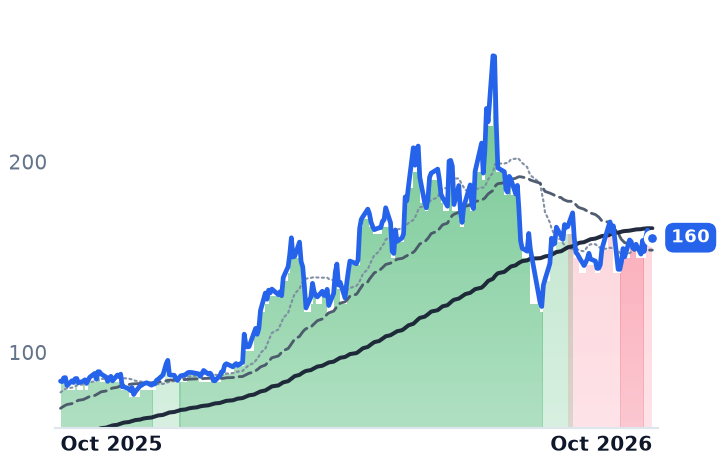
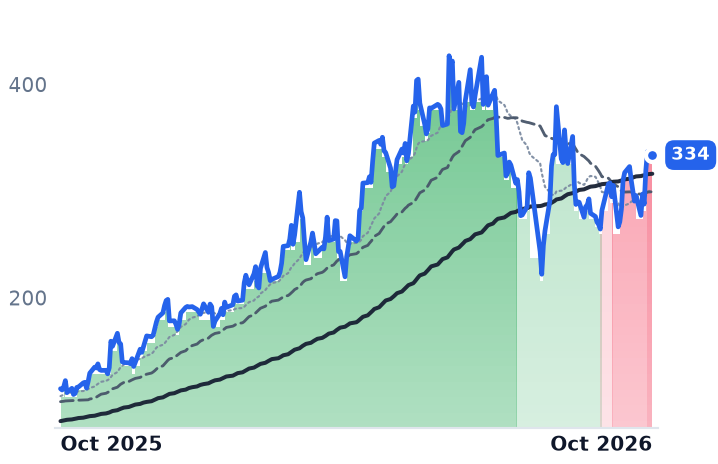
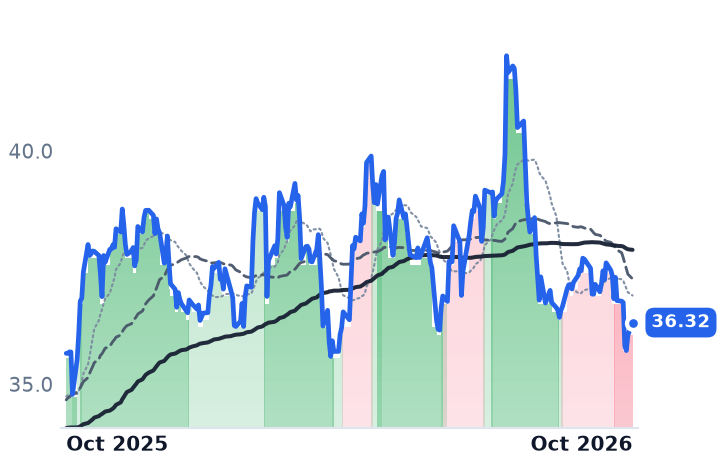
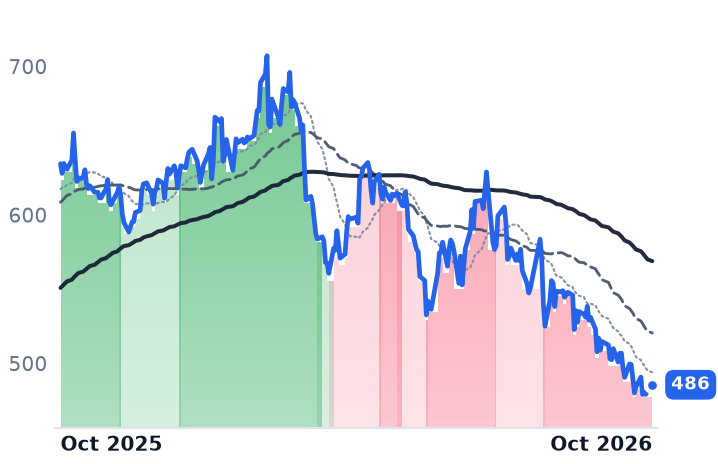
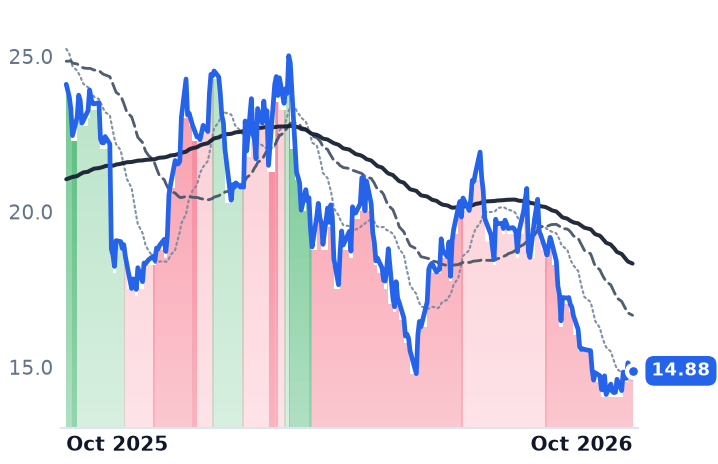
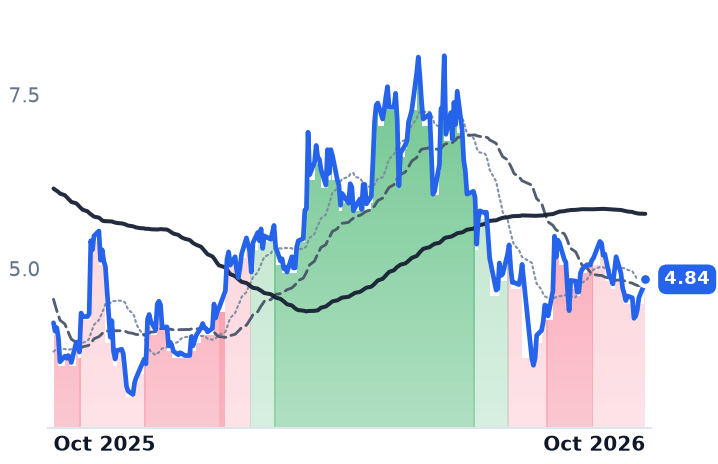
HAL | Halliburton | Well Services & Stimulation | ⚠️ Emerging Bear | −11.1% | +35.8% |
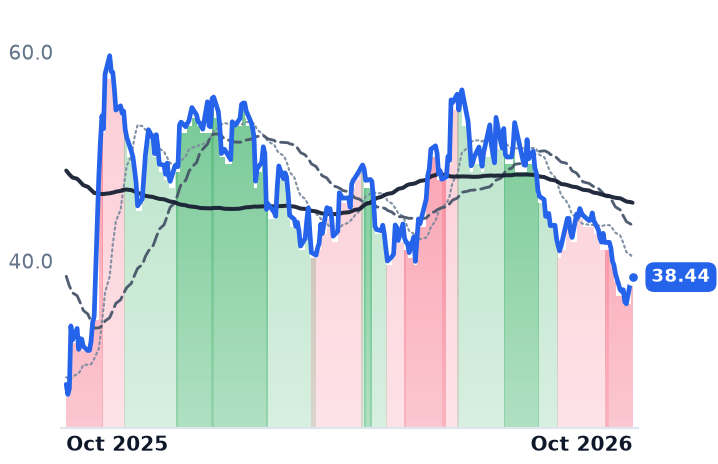
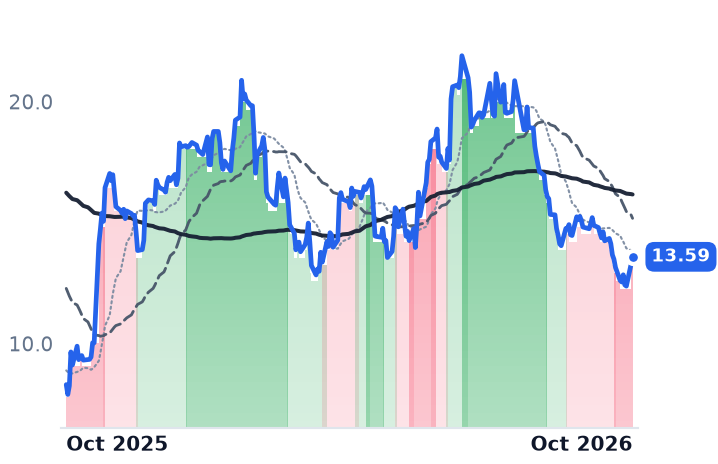
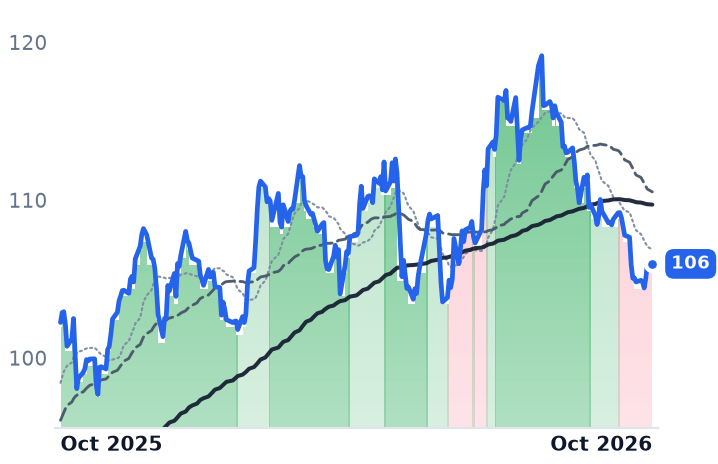
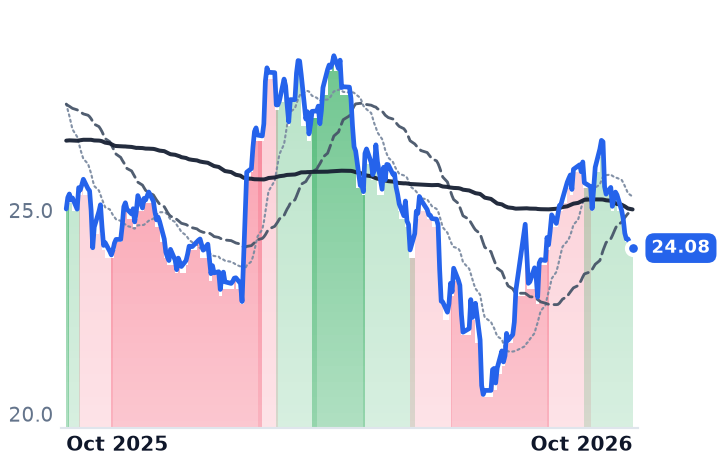
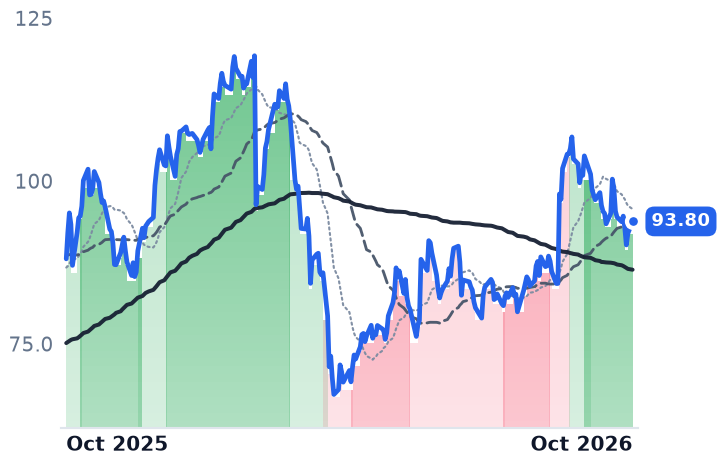
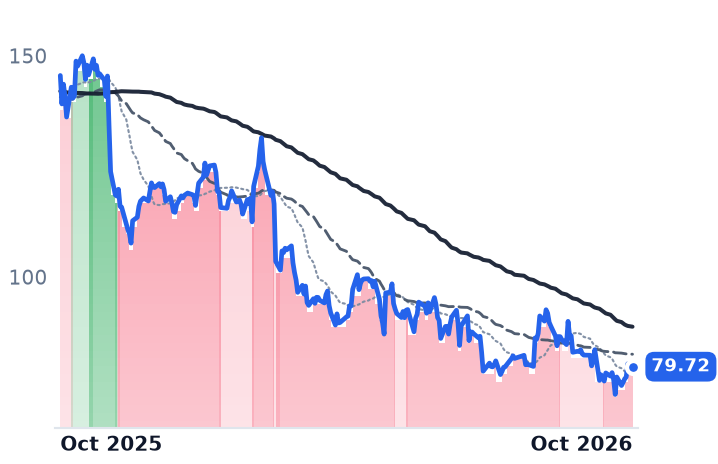
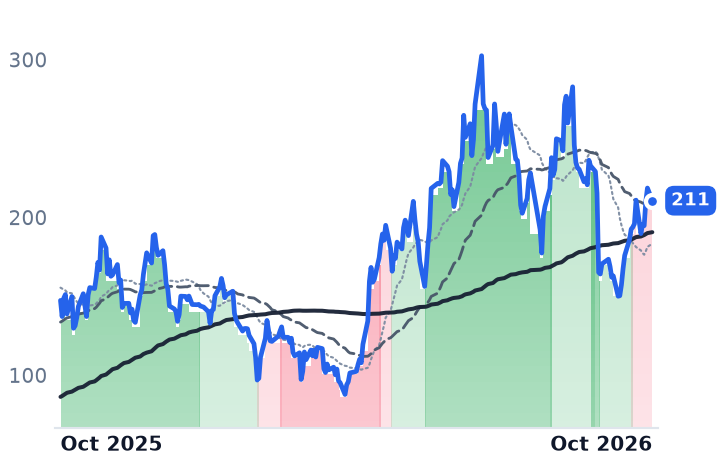
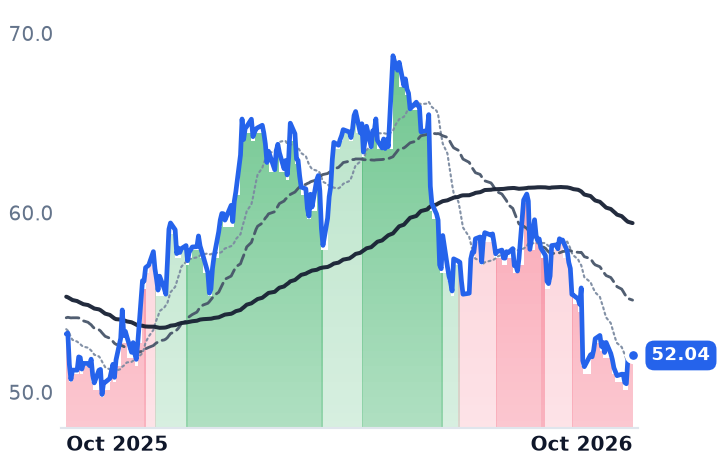
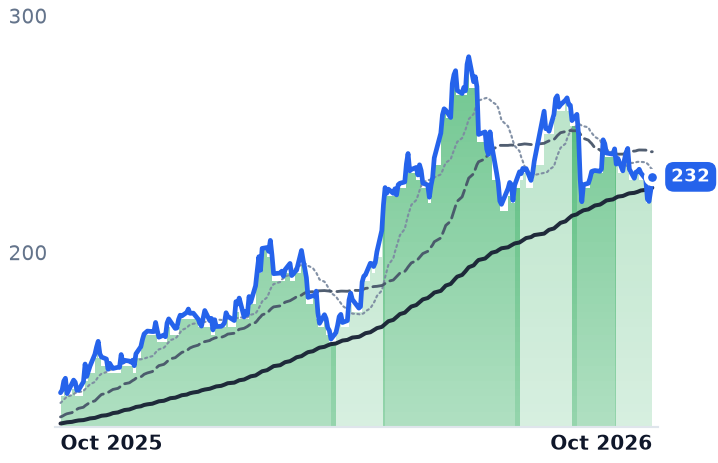
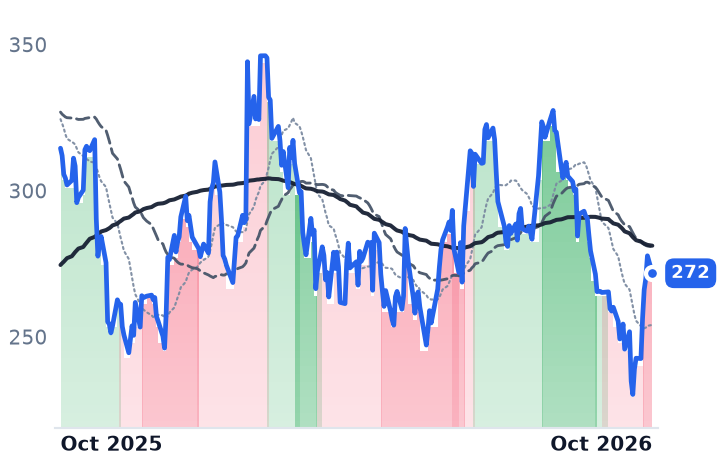
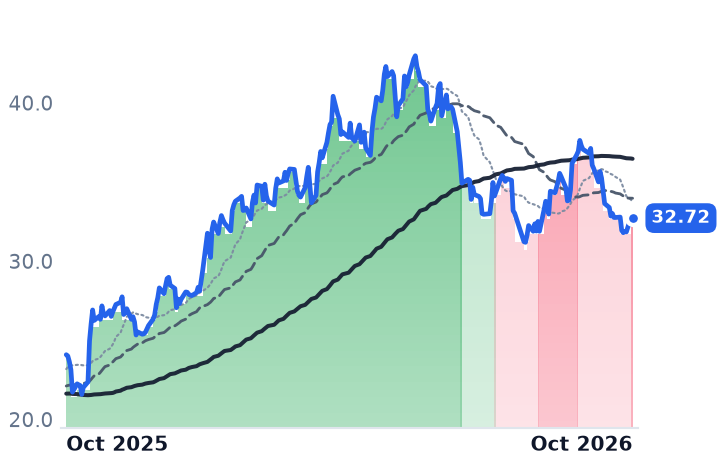
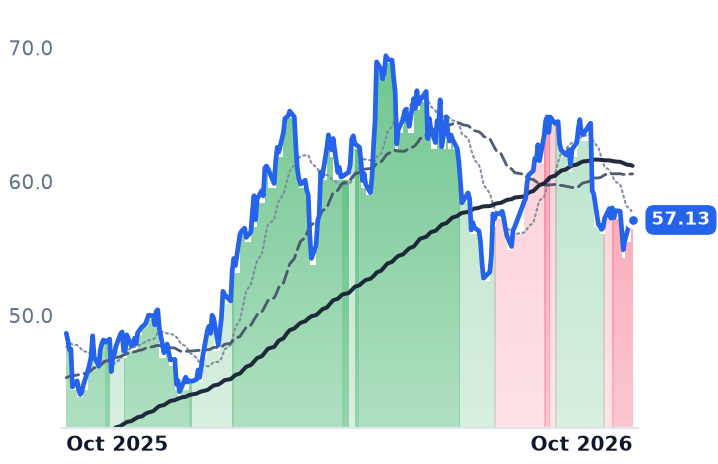
LBRT | Liberty Energy | Well Services & Stimulation | ⚠️ Emerging Bear | −7.0% | +52.8% |
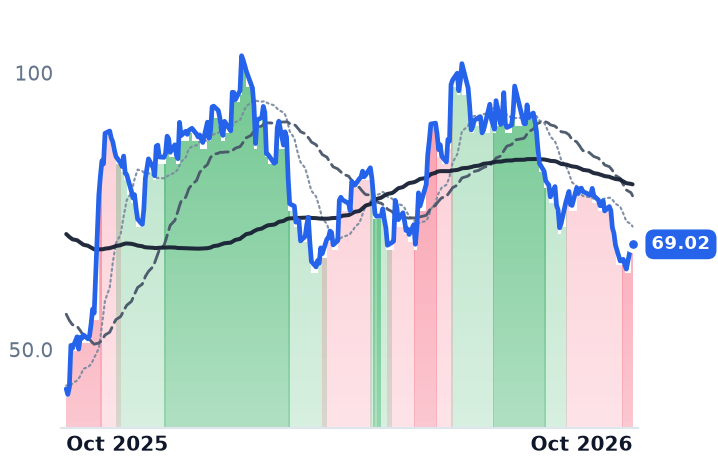
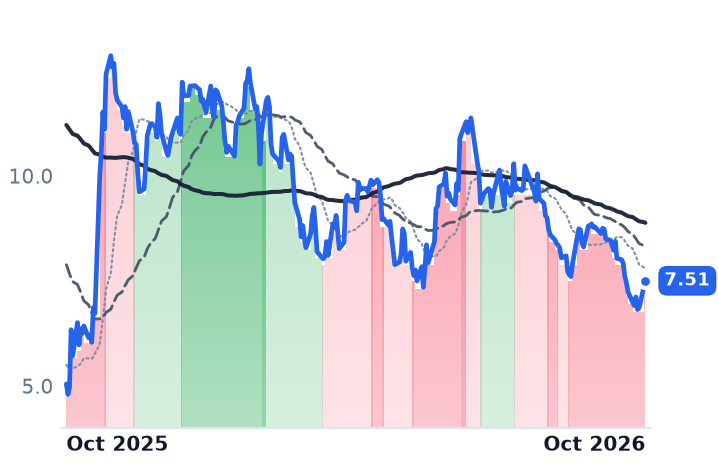
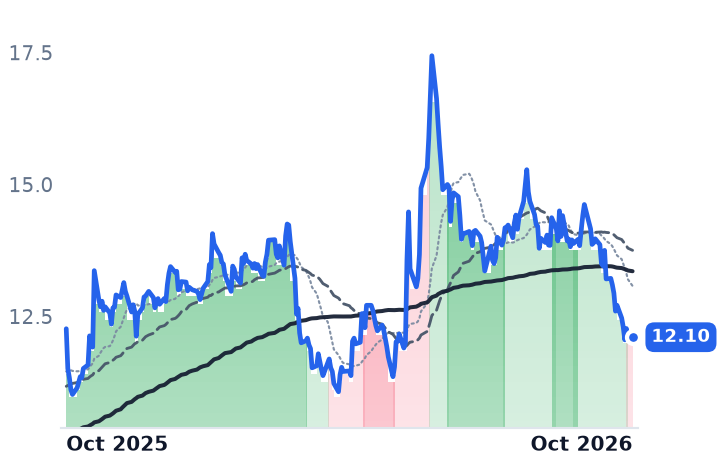
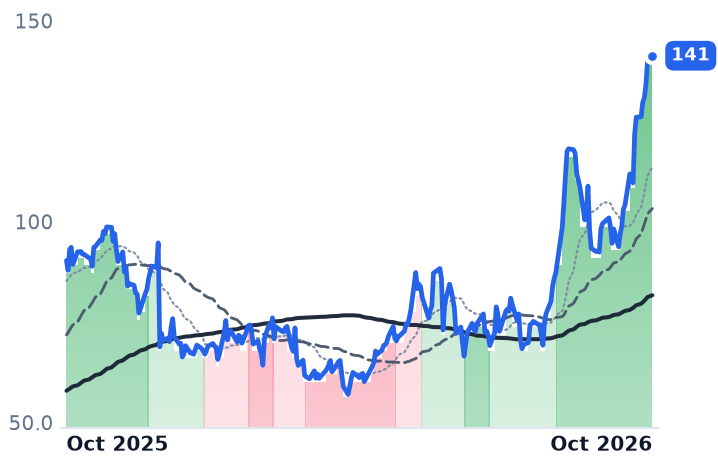
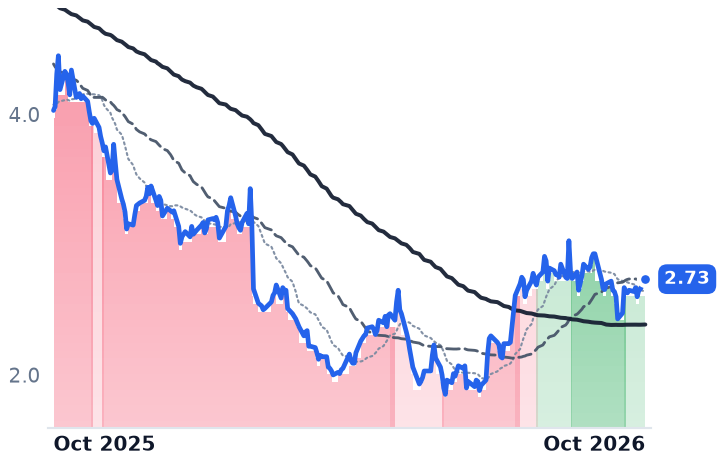
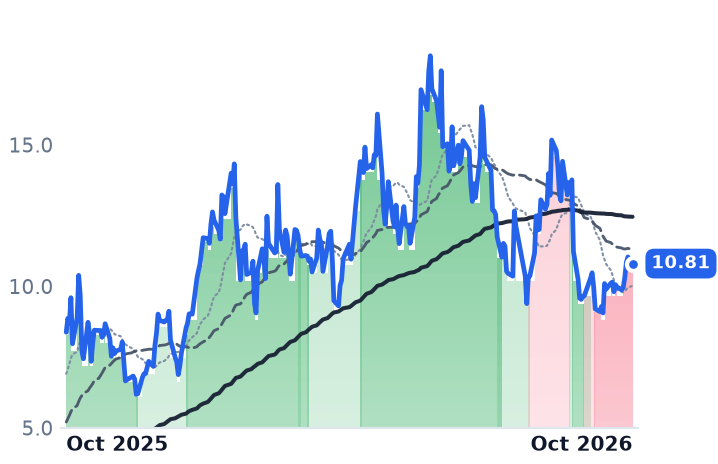
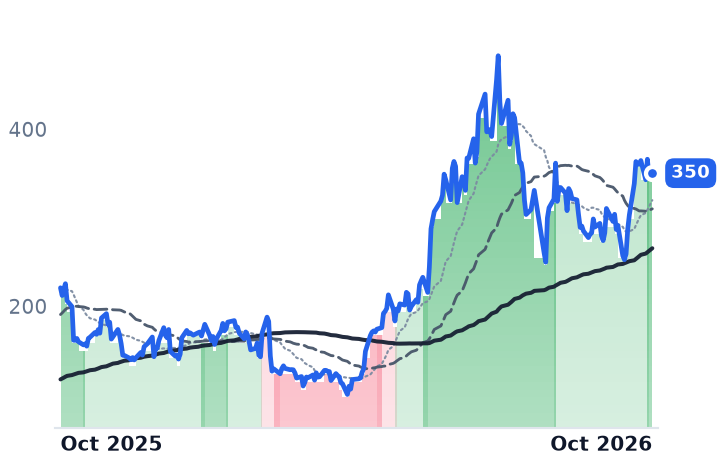
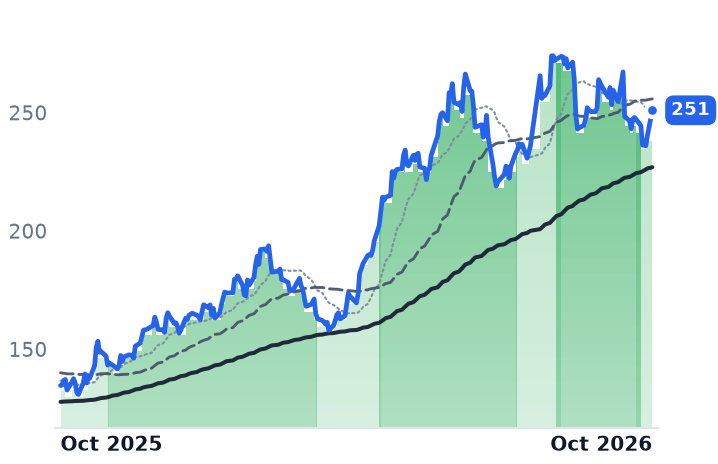
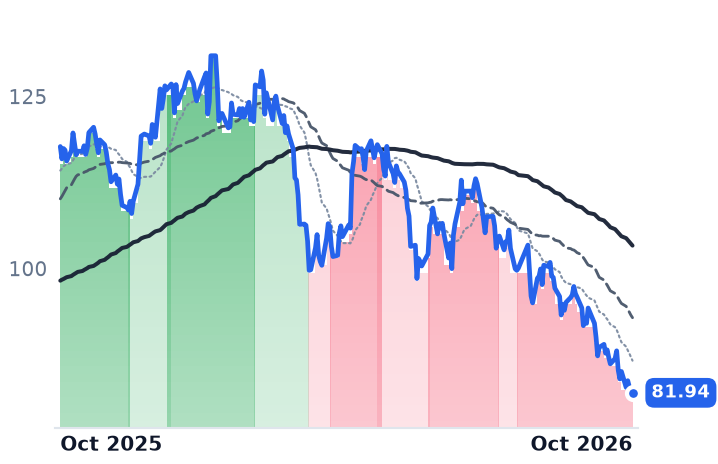
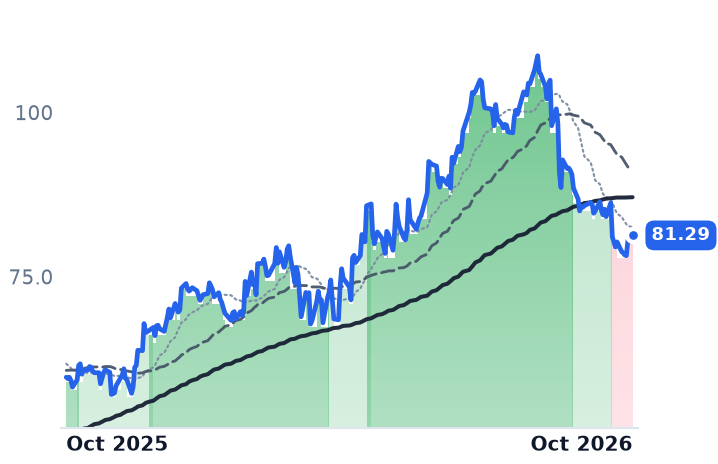
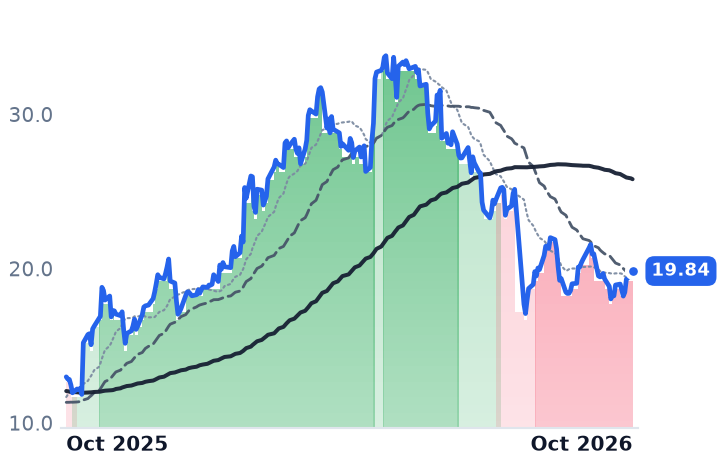
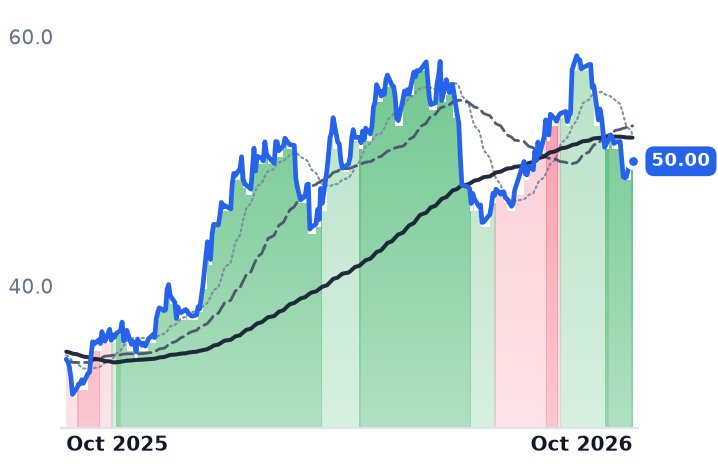
PUMP | ProPetro | Well Services & Stimulation | ⚠️ Emerging Bear | −19.6% | +74.0% |
| Compared against · context, not the story | |||||
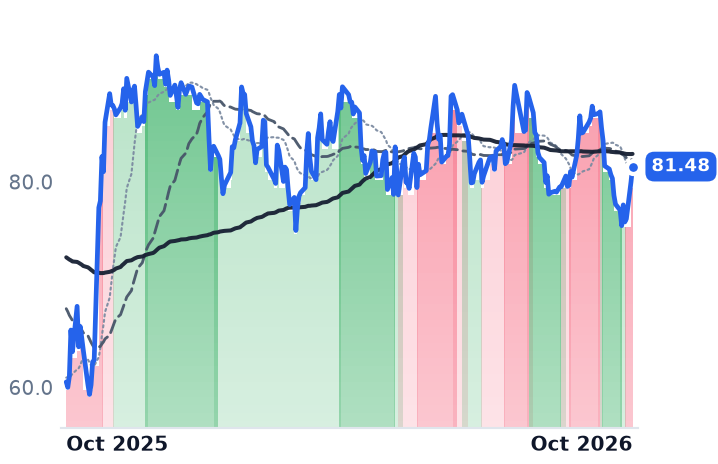
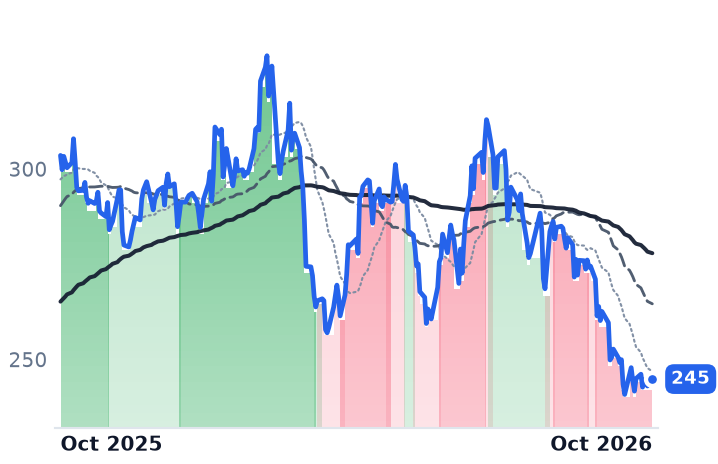
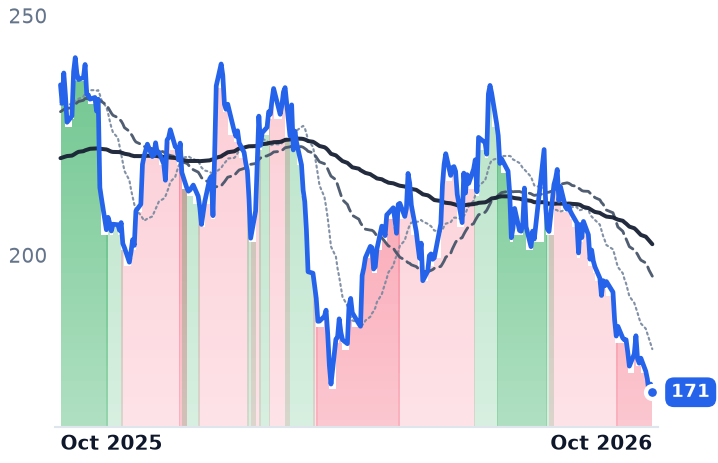
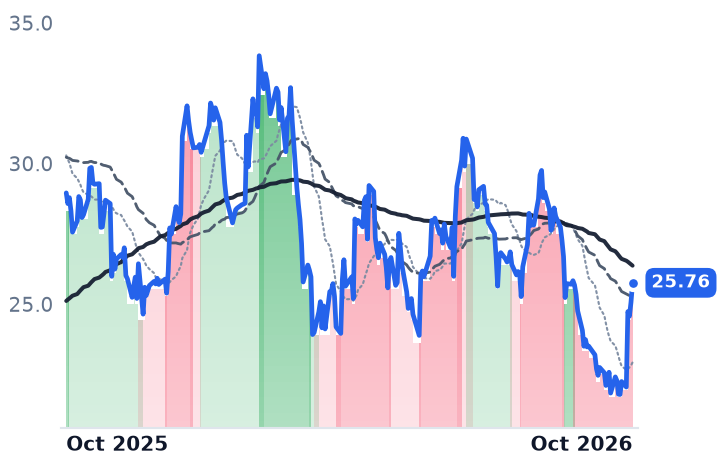
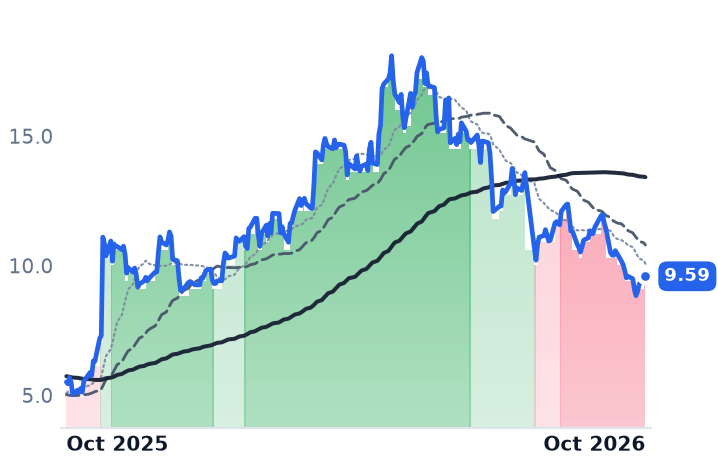
ACDC | ProFrac | Well Services & Stimulation | ⚠️ Emerging Bear | −10.1% | +14.8% |
BKR | Baker Hughes | Well Services & Stimulation | ⚠️ Emerging Bear | −11.0% | +17.4% |
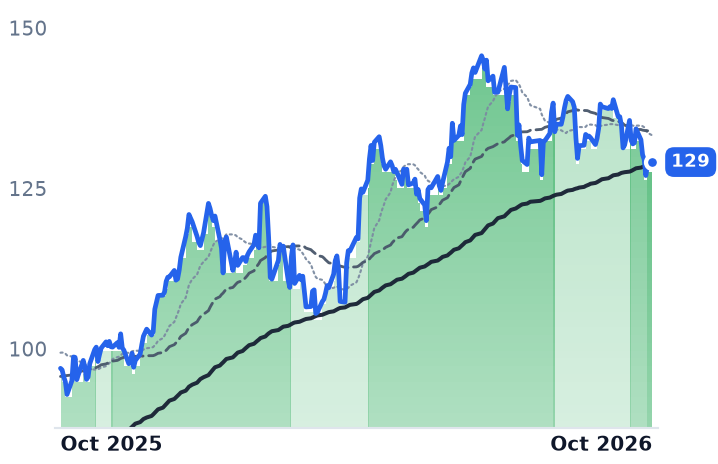
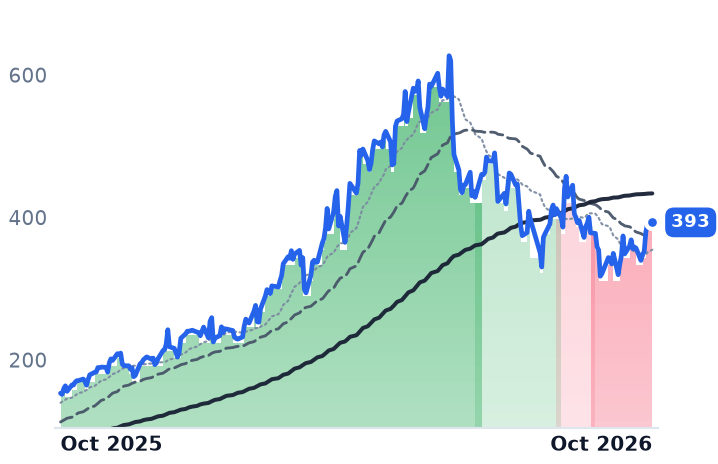
SLB | Slb | Well Services & Stimulation | 🟢 Cont. Bull | −13.4% | +46.6% |
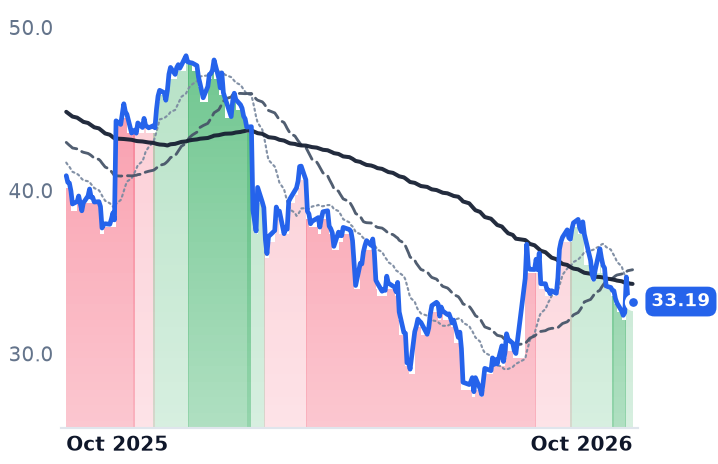
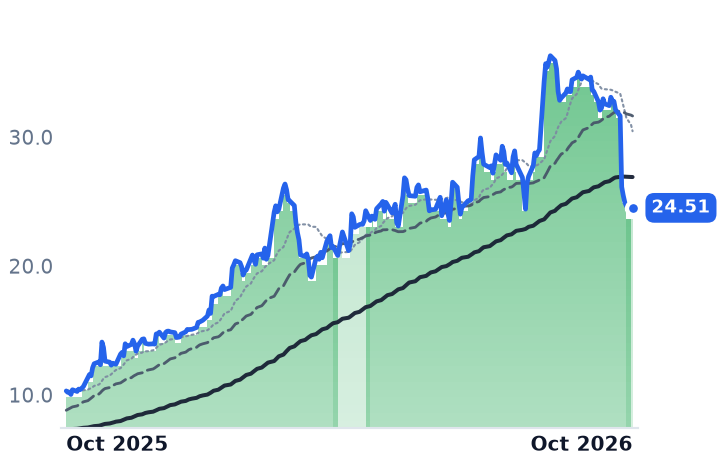
NESR | National Energy Services Reunited | Well Services & Stimulation | 🟢 Cont. Bull | −28.9% | +137.7% |
RES | RPC | Well Services & Stimulation | 🔴 Cont. Bear | −7.6% | +27.9% |
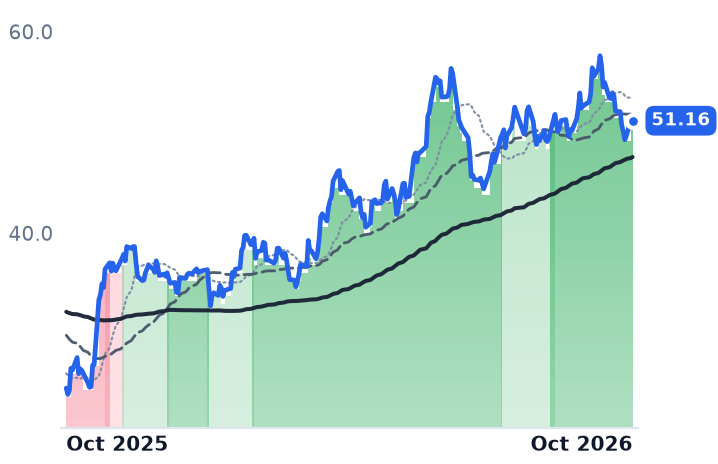
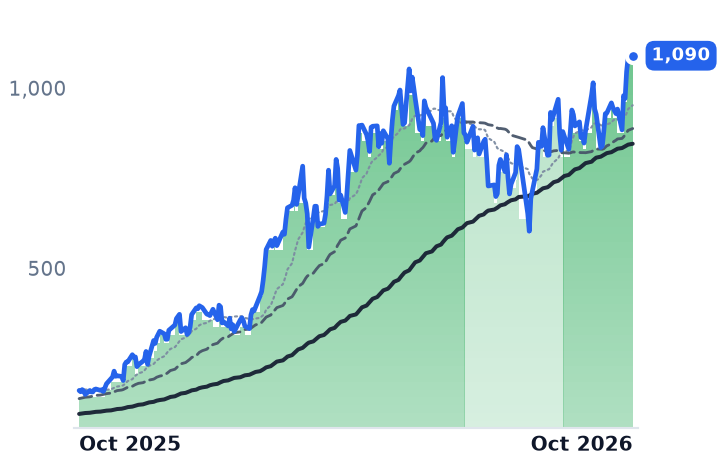
WTTR | Select Water Solutions | Water Services & Energy Solutions | 🟢 Cont. Bull | −3.3% | +86.5% |
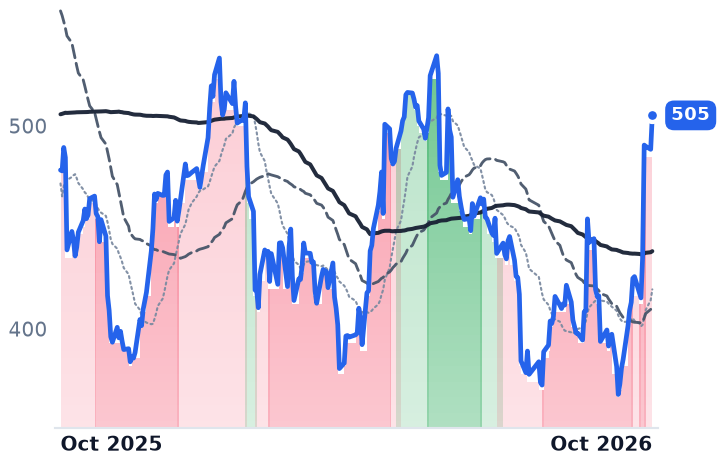
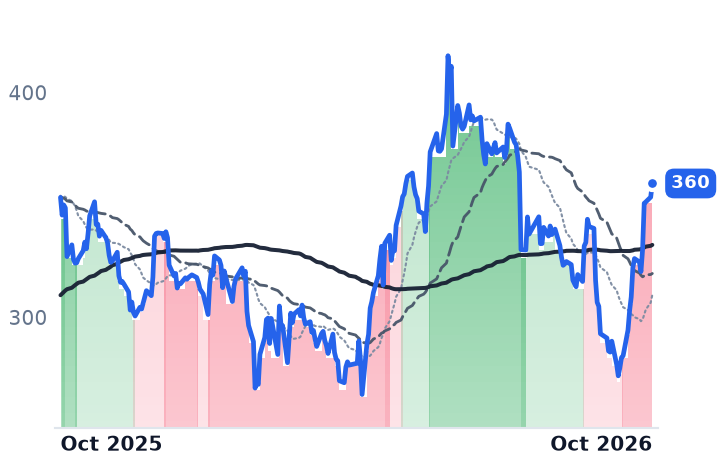
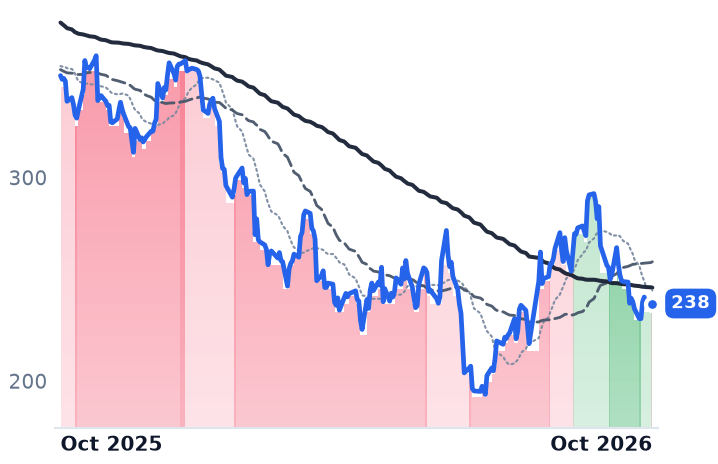
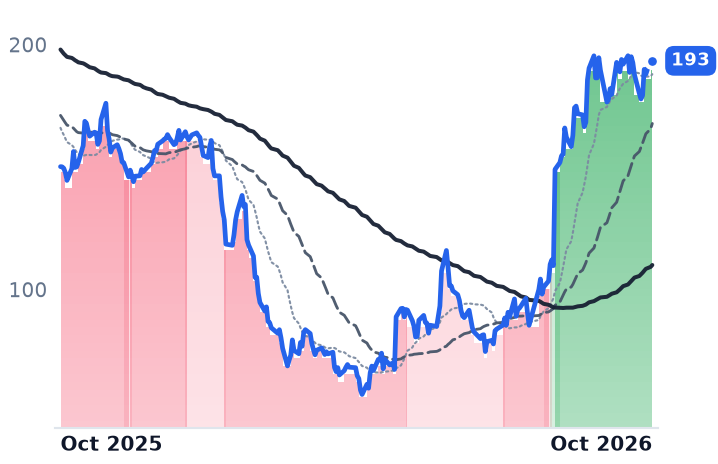
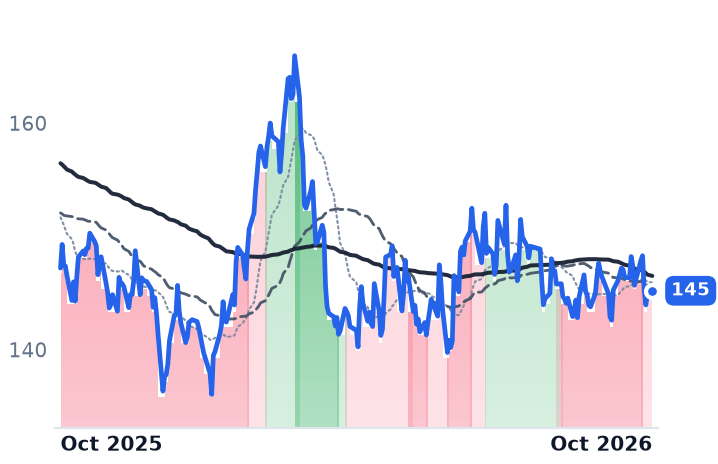
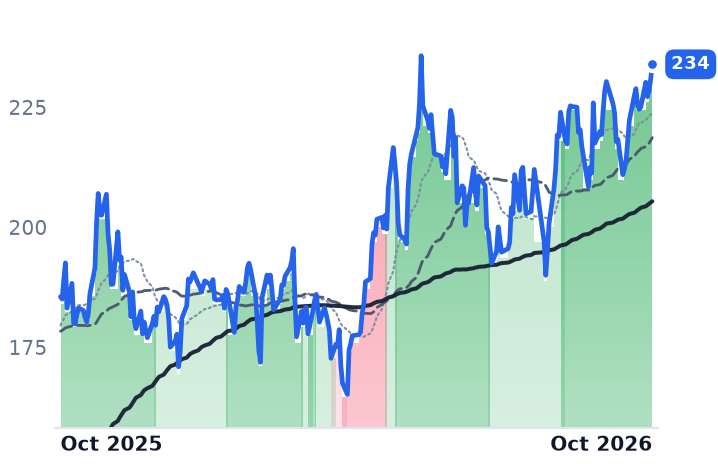
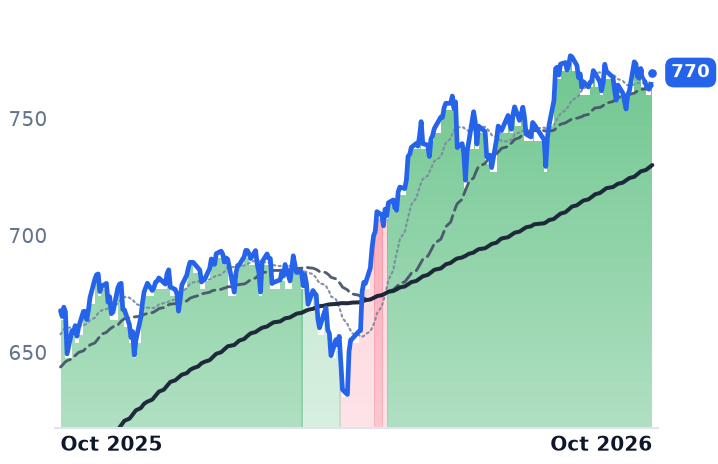
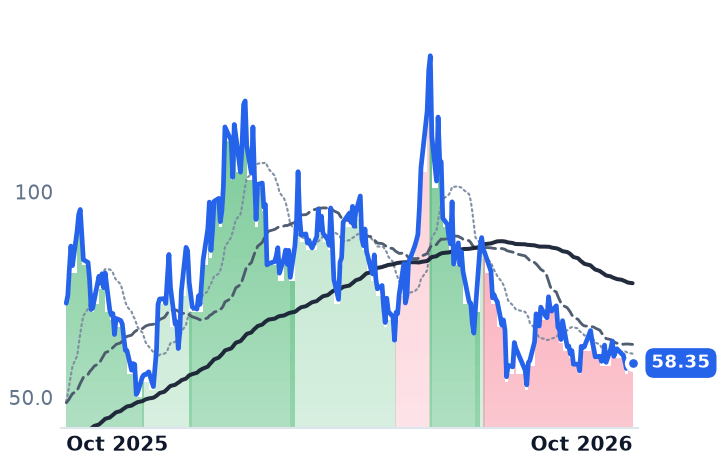
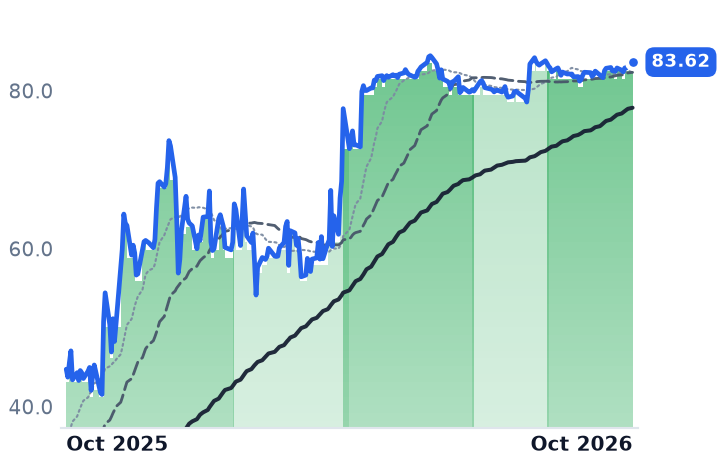
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
HAL | $27.3B | 17.1x | 14.0x | 1.2x | 1.2x | 8.1x | 8.1x | 8.1x | 6.3% |
LBRT | $3.3B | 26.7x | 86.6x | 0.8x | 0.7x | 6.1x | 5.6x | 7.0x | -9.6% |
PUMP | $1.2B | n/m | — | 1.0x | 1.0x | 12.2x | 11.5x | 7.4x | -1.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ACDC | $828.6M | n/m | — | 0.5x | 0.4x | 10.2x | 9.1x | 15.3x | -7.3% |
BKR | $62.0B | 19.9x | 23.7x | 2.2x | 2.2x | 9.5x | 9.4x | 13.2x | 5.0% |
SLB | $75.9B | 24.6x | 20.6x | 2.1x | 2.1x | 12.6x | 12.4x | 12.0x | 6.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NESR | $2.6B | 39.7x | 15.9x | 1.8x | 1.4x | 16.0x | 12.4x | 11.0x | 4.9% |
RES | $1.5B | 65.8x | 26.8x | 0.8x | 0.8x | 8.6x | 8.4x | 6.1x | 2.7% |
WTTR | $2.2B | 73.6x | 30.6x | 1.5x | 1.4x | 8.0x | 7.4x | 10.3x | -3.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
HAL | Revenue | +2.0% | +5.4% | +4.6% |
| EPS | +3.0% | +23.2% | +16.9% | |
LBRT | Revenue | +18.2% | +7.7% | +13.9% |
| EPS | −465.4% | −56.9% | +509.6% | |
PUMP | Revenue | −2.9% | +16.9% | +10.6% |
| EPS | −27.2% | −899.2% | +68.5% | |
ACDC | Revenue | +4.6% | +10.8% | −4.3% |
| EPS | −22.0% | −44.0% | −78.7% | |
BKR | Revenue | +2.3% | +10.9% | +7.5% |
| EPS | +6.7% | +14.6% | +20.0% | |
SLB | Revenue | +4.1% | +7.8% | +6.7% |
| EPS | −13.9% | +28.6% | +15.5% | |
NESR | Revenue | +41.8% | +22.0% | +18.3% |
| EPS | +111.9% | +47.6% | +29.2% | |
RES | Revenue | +12.5% | +2.1% | +2.7% |
| EPS | −15.0% | +4.1% | +35.2% | |
WTTR | Revenue | +12.3% | +8.4% | +4.8% |
| EPS | +166.8% | +2.6% | +55.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
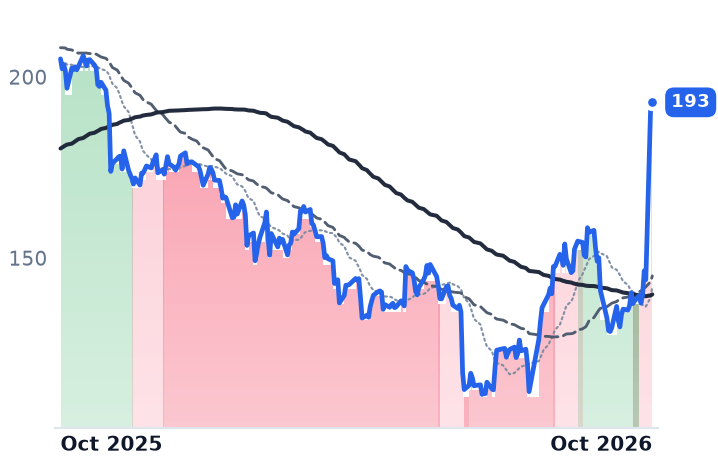
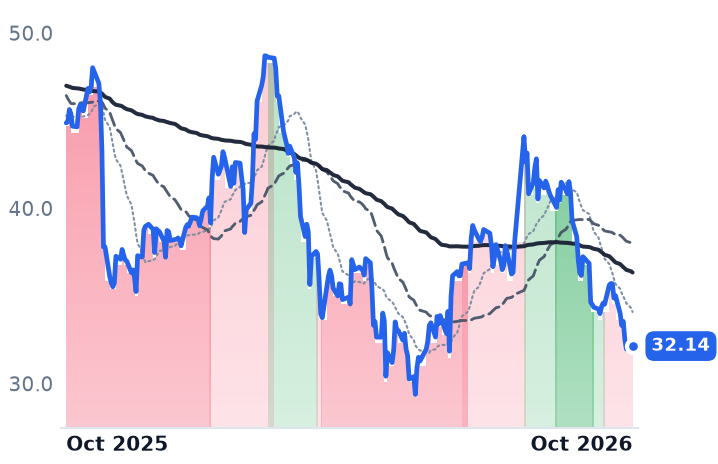
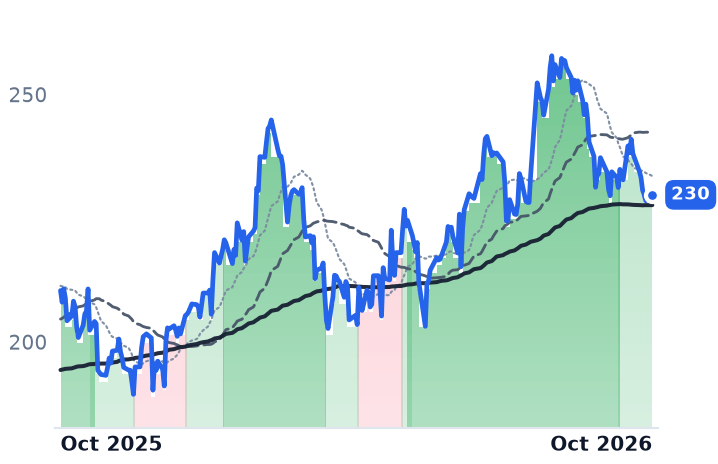
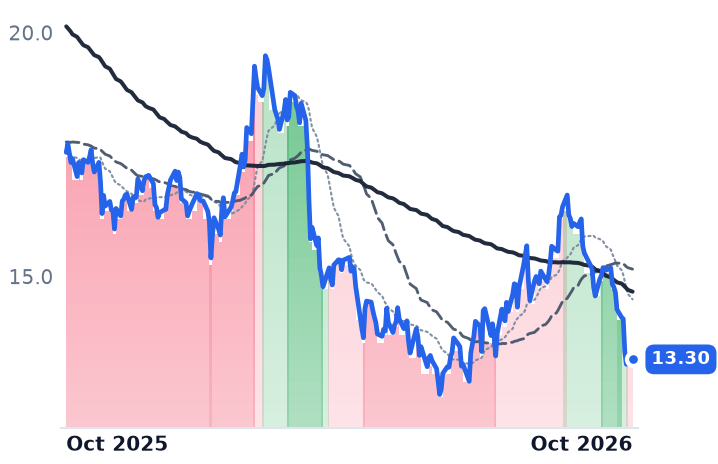
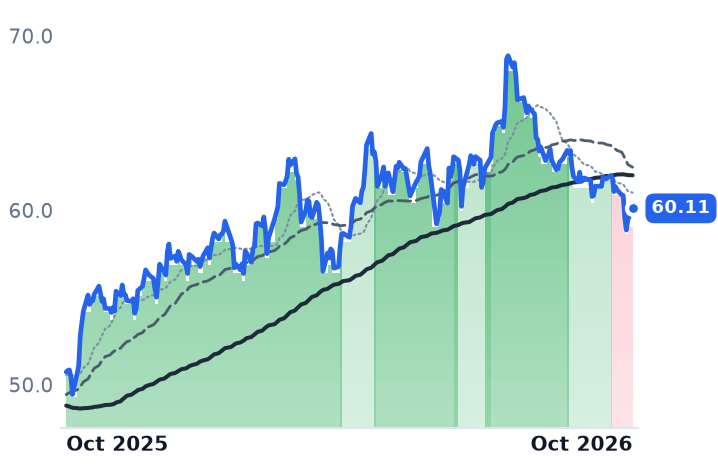
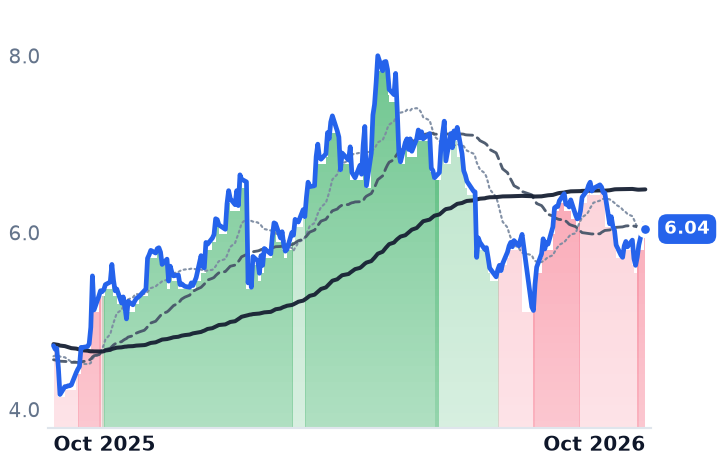
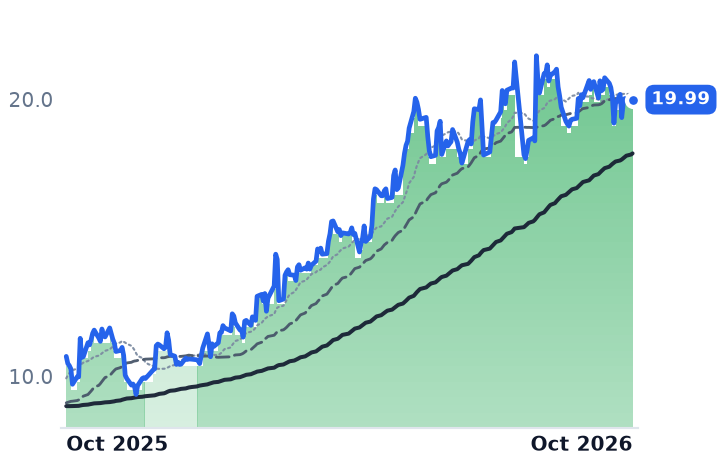
Halliburton booked more revenue outside North America in the June quarter than in any second quarter in more than a decade, and its shares still fell about 12% over the thirty days to 6 October. Liberty Energy, which pumps only American wells, fell under 4% in the same month.
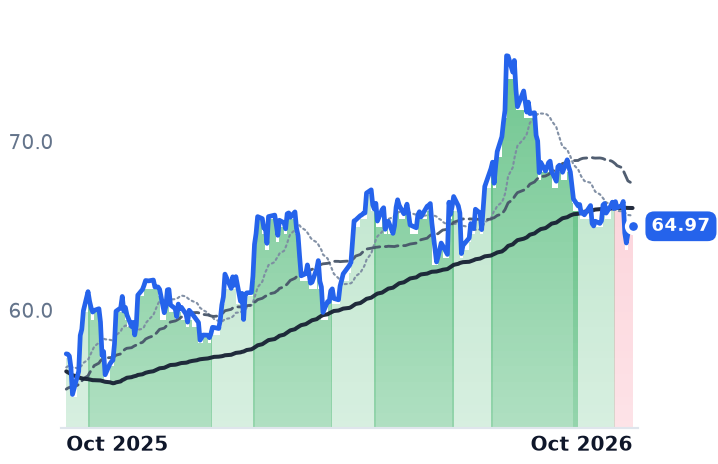
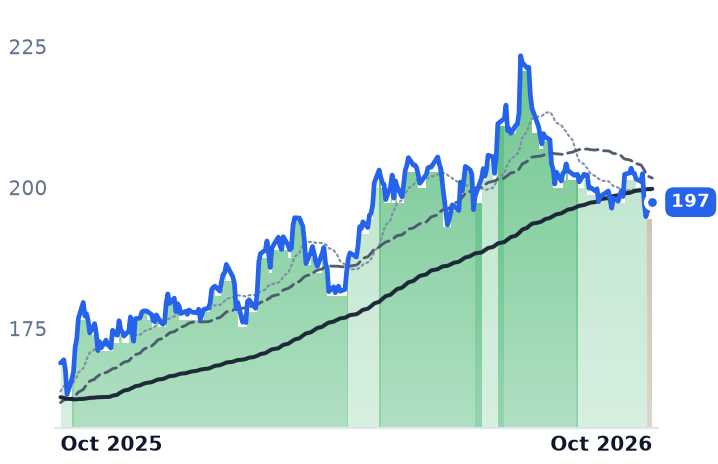
That ordering sits awkwardly with the explanation the market has used since July, when the pressure pumpers dropped out of their uptrends and the complex began trading as though North American completion work were shrinking. Primary Vision counted 196 active frac spreads on 2 October, seventeen more than a year earlier, and expects the count to hold near 200 through at least November. The Dallas Fed's third-quarter energy survey showed its index of prices received for oilfield services swing from -30.0 to 9.3, meaning services pricing turned up in the quarter. The work grew and its price firmed; what moved was the barrel these companies are paid in.
Halliburton's two halves get one multiple
North America revenue of $2.3bn was roughly flat year on year and up 7% sequentially on more US land stimulation, while international revenue of $3.4bn rose 6% to the highest second-quarter figure in more than a decade. "Our international business delivered its highest second quarter revenue in more than a decade, despite the disruption in the Middle East," chief executive Jeff Miller said on the 21 July earnings call, adding that "our North America business delivered sequential improvement, and my outlook for our business is positive." Completion and Production, the stimulation arm directly comparable to the independent pumpers, earned $474m on $3.2bn of revenue, a 15% segment operating margin.
Group operating income rose 7% on 3.7% revenue growth. The shares now change hands at 14.0x forward earnings against 17.1x trailing and 23.1x in May, on a 6.3% trailing free cash flow yield, with consensus earnings per share going from $2.34 this year to $2.88 next.
The month a Gulf premium came out of the barrel
Brent slid from above $105 in mid-September to $97.44 on 30 September as Saudi exports recovered. The United States announced an exchange of 40m barrels from the Strategic Petroleum Reserve on 29 September; the G7 agreed to release 100m barrels of crude and diesel on 2 October, and OPEC+ left November targets unchanged. By 6 October Brent held about $13.80 over WTI on record Persian Gulf tanker freight near $33 a barrel, with the inland US benchmark, the one that actually prices an American stage, down over the month.
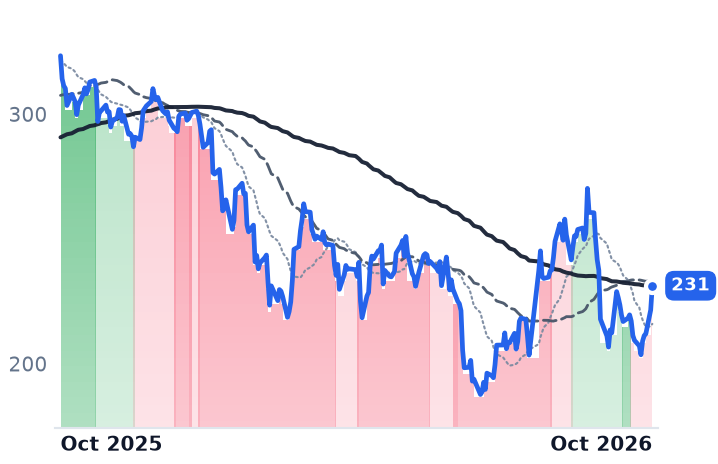
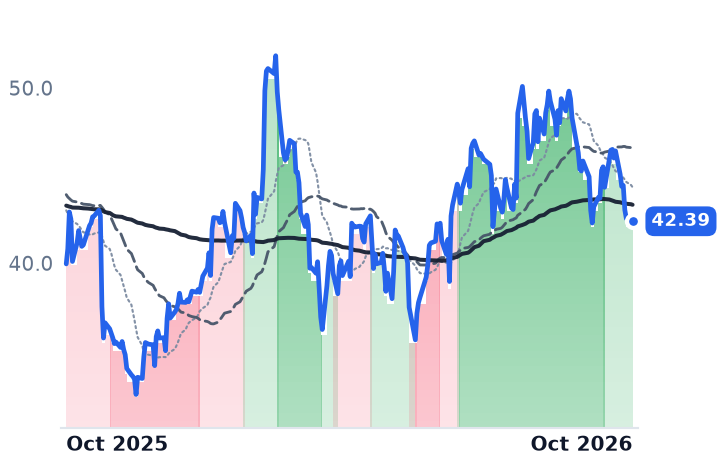
The Gulf-exposed names took the worst of it. NESR, the Middle East pumper, fell 29.5% over the thirty days and 3.9% on 30 September alone with nothing company-specific disclosed, UBS trimming its target to $46 from $47; SLB fell 13.1%. The likelier reading is a war premium deflating rather than Middle East activity turning down.
Liberty's cash is pre-paying for turbines
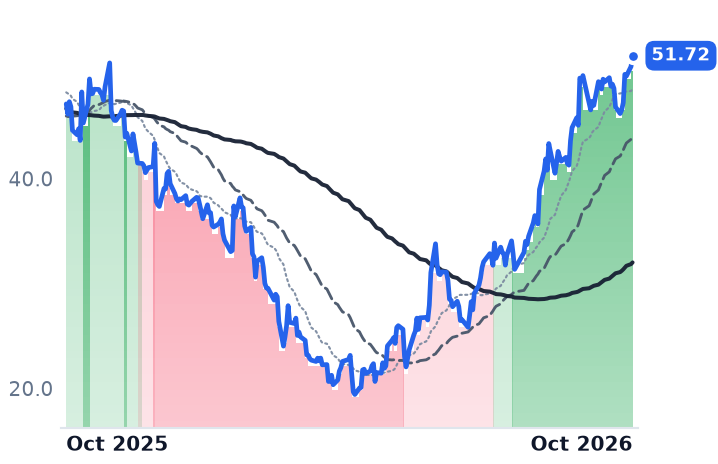
Liberty's June quarter was strong on every line a pumper is judged by: revenue of $1.189bn up 14%, gross margin 17.5% against 9.7%, gross profit more than doubled, records for pump hours, horsepower hours and utilisation and $151m of adjusted EBITDA. The shares fell 13.7% on the day of that beat.
At 0.78x trailing sales against 1.36x in May, and 7.0x EV/EBITDA, the de-rating is attached to the cash statement: trailing free cash flow yield is -9.6% as roughly $1.5bn of 2026 capital spending goes largely to deposits on long-lead power equipment, with $1.1bn of supply contracts still committed at 30 June and a further order worth $801m signed with Caterpillar on 22 July. "We have line of sight to that inbound 3 gigawatts," chief executive Ron Gusek said on the 23 July call. First power at the planned 2GW West Texas data-center campus Liberty is backing through a joint venture is anticipated in the fourth quarter of 2027.
ProPetro earned its discount
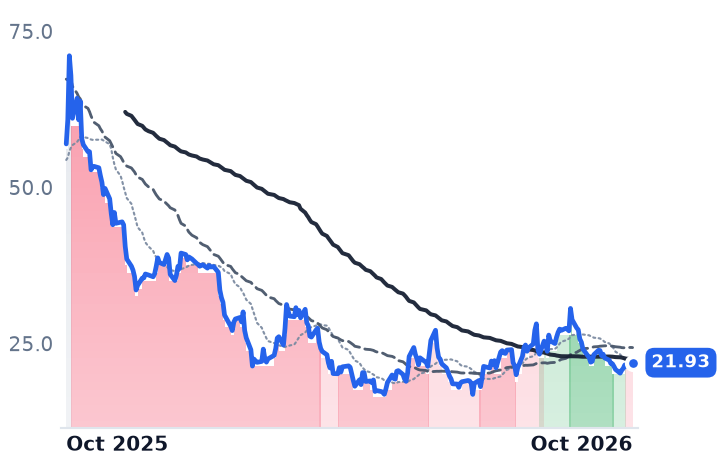
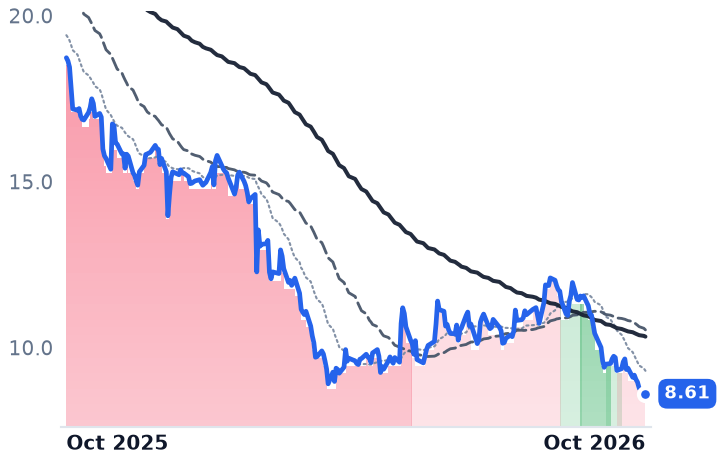
The Midland pumper is the one name where the share price is tracking the business. Revenue of $305.8m was down 6.2% year on year though up 13% sequentially, and the company lost $8.1m, an operating loss in five of the last six reported quarters. Price-to-gross-profit has risen from 7.1x in May to 12.2x even as the stock halved, because gross profit fell faster than the price. Its PROPWR book reached roughly 350MW of contracted capacity from about 240MW, and $47m of the quarter's $71m of capital spending went to power equipment inside a $525-595m full-year budget set against roughly $1.16bn of trailing revenue. Twelve fleets ran in the quarter, with a thirteenth scheduled for the end of the third. "We're beginning to see positive pricing momentum," chief executive Sam Sledge told investors, saying the industry has "consolidated through attrition."
What the quarters do and do not account for
Very little of the month. Halliburton grew revenue and operating income and shed about a quarter of its multiple since May; Liberty doubled its gross profit and lost more than a third of its price-to-sales. Each name has its own reason for being sold: Halliburton and NESR for where their barrels come from, Liberty for what it has contracted to pay suppliers years before a megawatt is delivered, ProPetro for losing money with twelve fleets working. Nor has the oilfield dollar left services — Select Water Infrastructure, the produced-water handler, has held its uptrend throughout and is up 84% on twelve months.
The frac count says the work is there and the Dallas Fed says its price is firming. What the past month repriced was the crude benchmark, and that is decided a long way from Midland.