

Norwegian Cruise Line Bought Three Years of Time as Its Advance Ticket Sales Went Flat
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
A cruise operator's forward cash is the money it holds for voyages nobody has sailed. Norwegian's has stopped growing: advance ticket sales including the long-term portion stood at $4.0bn at the end of June against $3.9bn a year earlier, on a fleet with more capacity days to fill.
On 1 October its finance subsidiary priced notes due 2031 to retire notes due 2028, lifting the coupon by 262.5 basis points, and guided 2027 net interest to $860m-$880m. Third-quarter net yield is guided down 8.9% in constant currency.
The group does not move together. Royal Caribbean collected $996m of deposits in the June quarter against $883m a year earlier and raised earnings guidance; Viking's net yield rose 6.2% before its European rivers ran dry. Norwegian is the one whose berths and interest payments arrive on fixed calendar dates.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
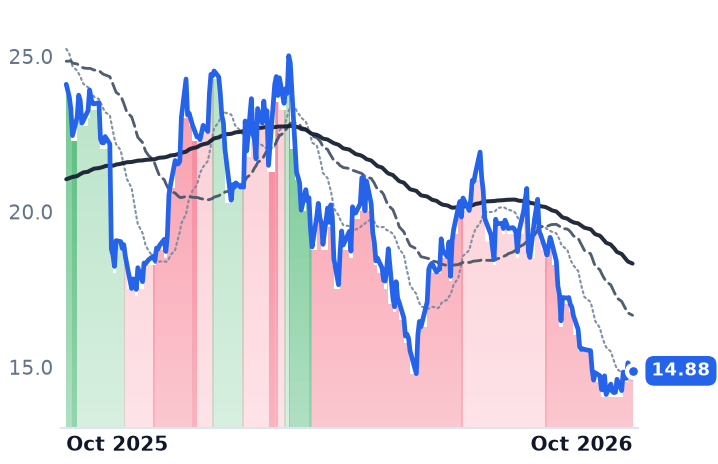
NCLH | Norwegian Cruise Line | Cruise Operators | 🔴 Cont. Bear | −4.2% | −38.3% |
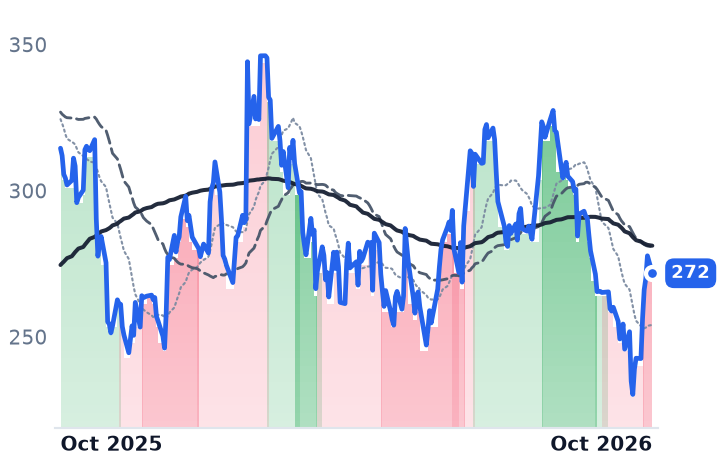
RCL | Royal Caribbean Cruises | Cruise Operators | 🔴 Cont. Bear | +2.4% | −13.6% |
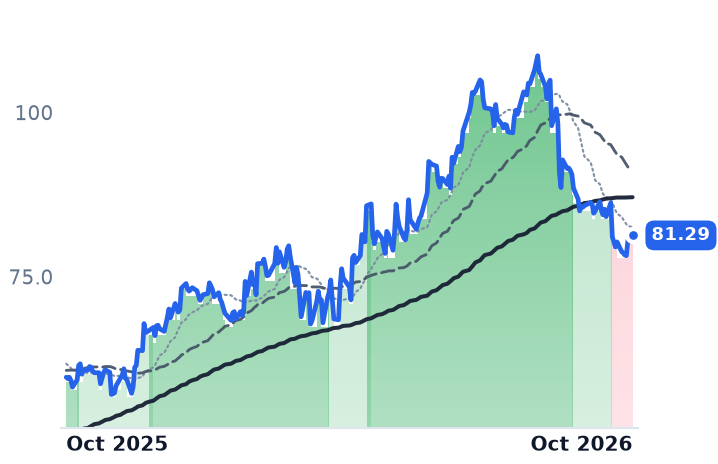
VIK | Viking | Cruise Operators | 🟢 Cont. Bull | −5.8% | +36.2% |
| Compared against · context, not the story | |||||
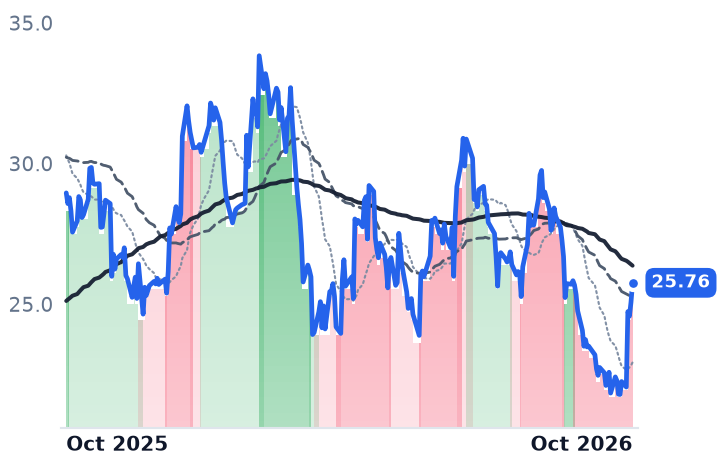
CCL | Carnival | Cruise Operators | 🔴 Cont. Bear | +11.0% | −11.0% |
LIND | Lindblad Expeditions | Cruise Operators | 🟢 Cont. Bull | +31.9% | +178.9% |
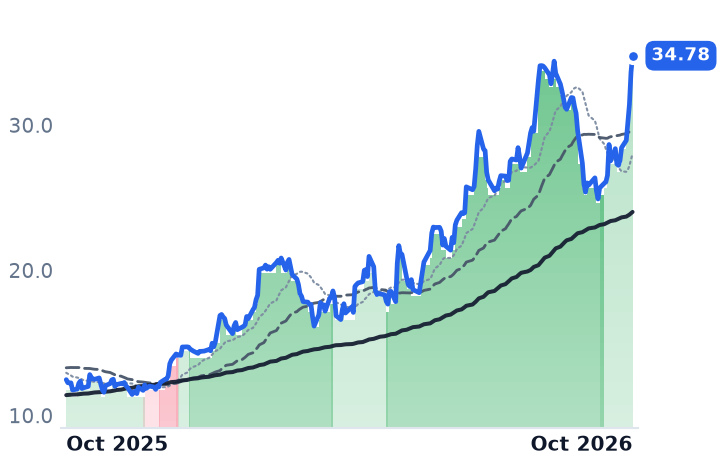
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NCLH | $6.8B | 8.9x | 9.7x | 0.7x | 0.7x | 1.6x | 1.6x | 8.3x | -16.8% |
RCL | $72.9B | 16.7x | 15.3x | 3.9x | 3.7x | 8.4x | 8.0x | 13.2x | -0.6% |
VIK | $36.1B | 26.8x | 25.0x | 5.2x | 4.9x | 13.4x | 12.6x | 19.2x | 2.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CCL | $34.8B | 11.0x | 11.3x | 1.3x | 1.3x | 3.7x | 3.7x | 8.1x | 9.1% |
LIND | $2.3B | n/m | 180.1x | 2.8x | 2.6x | 8.0x | 7.6x | 25.5x | 4.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
NCLH | Revenue | +1.1% | +4.9% | +6.2% |
| EPS | −26.2% | +8.1% | +18.8% | |
RCL | Revenue | +9.0% | +7.2% | +9.4% |
| EPS | +13.6% | +14.4% | +14.9% | |
VIK | Revenue | +15.3% | +21.2% | +13.5% |
| EPS | +30.5% | +34.6% | +22.3% | |
CCL | Revenue | +4.0% | +3.2% | +4.1% |
| EPS | +4.7% | +14.1% | +18.7% | |
LIND | Revenue | +15.0% | +9.2% | +4.1% |
| EPS | −139.6% | +159.6% | +34.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Norwegian Cruise Line Holdings, which sells voyages across the Norwegian, Oceania and Regent Seven Seas brands, went to the bond market on 1 October to push its nearest maturity out three years and paid a coupon 262.5 basis points higher to do it. The money it holds against voyages already sold has meanwhile stopped growing: advance ticket sales including the long-term portion came to $4.0bn at 30 June against $3.9bn a year earlier, on a fleet whose capacity days keep rising.
Late September read this industry as intact. Carnival reported on 29 September with third-quarter-record customer deposits of $7.6bn, half a billion dollars above the prior-year record, and the whole shelf gapped up that session, Royal Caribbean 5.7% and Norwegian 4.2%. But a cruise line collects its money when the ticket is sold, up to two years early, and holds it free of interest until the passenger sails. That balance is the forward demand meter, and on it Norwegian is standing still while two peers are still filling up.
The float is flat while the fleet grows
The current advance-ticket line was $3,651.2m at 30 June against $3,200.6m at the end of December, a seasonal build that leaves the year-on-year total roughly where it was. Inside the quarter, the second dollar carried the first: passenger ticket revenue rose 1.2% to $1.73bn while onboard and other revenue — beverage packages, excursions, casino — rose 12.6% to $910.7m, taking onboard to 34.5% of revenue from 32.1%.
Net yield fell about 2.6% in constant currency, ahead of the company's own guidance, with the full year guided down roughly 5% and the third quarter guided down 8.9%. Net cruise cost excluding fuel per capacity day was $168.52 as reported, against guidance of about 1% growth. What compressed was the price.
Chief executive John Chidsey was blunt about the cause on the 30 July call. "The vast majority of our problems are self-inflicted execution issues, not macro," he said, calling them "totally in our control to fix" alongside $225m of identified savings. The company also said first-half 2027 net yields will be negative.
Berths and interest arrive on fixed dates
Net leverage was 5.3x at 30 June on roughly $16bn of debt against a $6.83bn equity value. NCL Corporation priced an upsized $950m of senior notes due 2031 at 8.750% to redeem the 6.125% notes due 2028, repay about $376.3m of revolver borrowings and prepay about $42.2m of export-credit-backed facilities, closing 15 October. Adjusted for that, 2027 net interest is guided to $860m-$880m: by arithmetic, about 8.6% of the revenue analysts expect that year, before a ship arrives.
Ships do arrive. The orderbook runs to 14 vessels valued at over $19bn and some 45,000 berths, including the 3,650-guest Norwegian Luna in 2027.
At 8.3x trailing enterprise value to EBITDA, Norwegian trades well below Royal Caribbean's 13.2x and Viking's 19.2x. Its forward price-to-earnings of 9.7x sits above its trailing 8.9x, which is the market pricing a smaller profit; consensus has 2026 earnings per share 26% under 2025, and trailing free cash flow is negative 16.8% of market value.
Royal Caribbean collected faster, Viking collected more per day
Royal Caribbean, with 61 ships across Royal Caribbean International, Celebrity, Azamara and Silversea, is the mirror image on the float: deposits reached $6,736m at 30 June and built $996m during the quarter against a build of $883m a year earlier. Operating income slipped 1.7% and gross margin gave up 2.4 points, yet net yields rose 1.2% in constant currency and full-year adjusted earnings guidance went up to $17.73-$17.87, roughly 14% above 2025. The shares are down 14.3% over twelve months, taking the multiple to 15.3x forward from about 20x realised 2025 earnings, while the company funds about $4.7bn of 2026 capital spending including $1.6bn outside new ships, much of it on private destinations whose yields land years later.
Viking Holdings, whose 92-vessel fleet is 81 riverboats against nine ocean liners, is the one whose price per day is rising: net yield of $645 per passenger cruise day, up 6.2% on revenue up 16.5%, with $4,711m of 2027 advance bookings, 21% ahead of 2026 at the same point. As of 9 August it had 53% of 2027 core capacity sold at $958 per passenger cruise day, up 10%, on 15% more capacity. Its shares still fell 19.2% over three months, from the most expensive multiple on the shelf, and it carries a cost shock the ocean operators cannot have: more than half its European river-cruise days from mid-July to mid-August were hit by low water, with 10-12% of affected passengers cancelling.
What the autumn selling actually described
Three of these names fell over the past three months: Norwegian 22.7%, Viking 19.2%, Royal Caribbean 5.6%. Only Norwegian's decline is matched by deteriorating results — falling yields, operating income down 14.3%, a flat float and an interest bill fixed by contract. Royal Caribbean's de-rating has no earnings decline underneath it, and Viking's followed a weather event from a starting multiple of 19.2x EBITDA. Norwegian's shares have been in a downtrend since August and touched $14.18 on 18 September, before the company said on 1 October that third-quarter results would exceed July guidance.
The ceiling over all of it is supply. The global orderbook stands at 78 ships and more than 206,600 berths, with 15 ships and about 27,860 berths due in 2027, roughly 4% more capacity. Carnival's Josh Weinstein told investors on 29 September that "for full year 2027, we are already half booked with both occupancy and pricing at record levels" — on planned capacity growth of 0.5%. Norwegian is adding berths into the same water at a pace its forward book has not yet matched.
Norwegian reports third-quarter results on 4 November. Its yield is already written down for that quarter; the company has said so. What the market has not seen is the deposit line, the money collected for voyages nobody has sailed, and the only figure that says whether the next two years have been sold.