

BWX Technologies' Navy Backlog Grew All Year While the Market Priced It Like Oklo
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
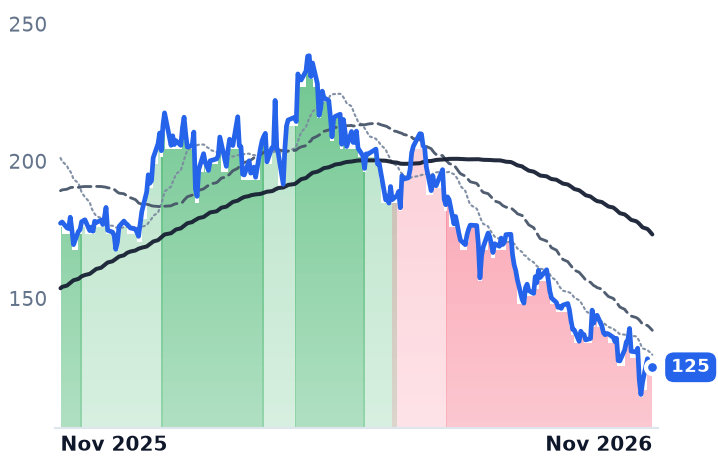
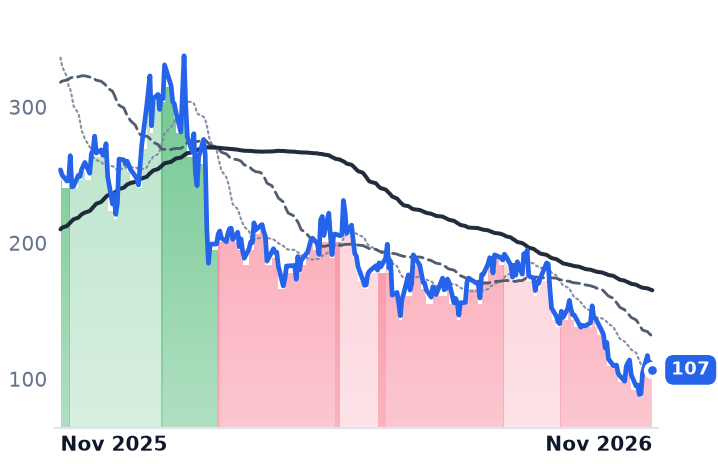
One sentiment markdown has been applied to three nuclear income statements that have almost nothing in common. BWX Technologies, sole-source supplier of naval reactors to the US Navy, widened operating margin from 10.6% to 13.9% in the September quarter, pushed backlog to $8,556m and raised the low end of its free-cash-flow guidance. Its shares are down 39.6% in six months.
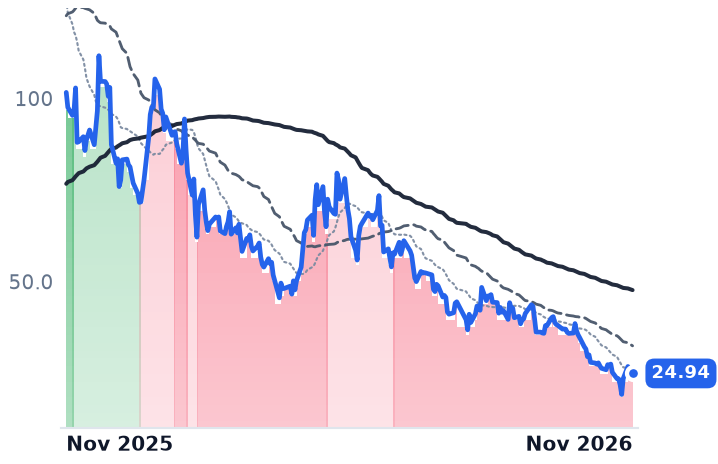
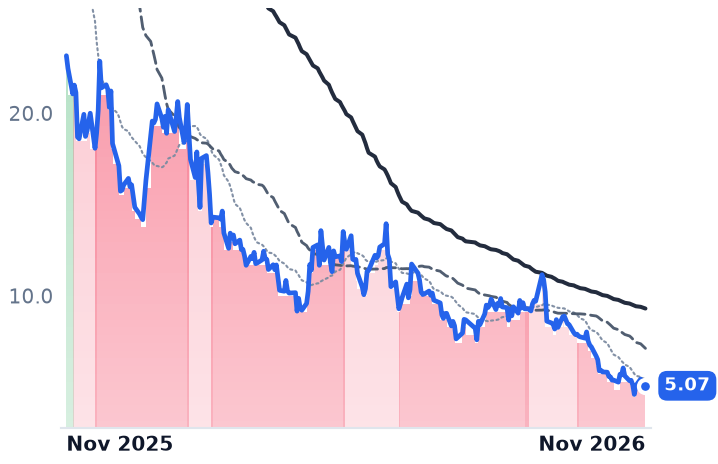
Oklo and NuScale fell further on results that explain the fall: Oklo booked $3.07m of revenue in nine months against a customer book its own filing calls non-binding letters of intent, and NuScale's quarterly revenue fell 96.6% to $0.281m with no module sold. Both are diluting hard, both hold years of cash.
BWXT now trades at 26.2x forward earnings against roughly 46x forward in May. Nothing in its disclosures moved the way the price did.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
BWXT | BWX Technologies | Aerospace Components & Propulsion | 🔴 Cont. Bear | −8.7% | −29.6% |
OKLO | Oklo | Advanced Nuclear | 🔴 Cont. Bear | −15.5% | −75.5% |
SMR | NuScale Power | Advanced Power Systems | 🔴 Cont. Bear | −13.9% | −78.1% |
| Compared against · context, not the story | |||||
CCJ | Cameco | Uranium | 🔴 Cont. Bear | −11.3% | −15.4% |
LEU | Centrus Energy | Uranium | 🔴 Cont. Bear | −13.1% | −57.9% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BWXT | $11.4B | 30.4x | 26.2x | 3.2x | 3.0x | 14.0x | 13.3x | 22.4x | 3.3% |
OKLO | $4.8B | n/m | — | — | — | — | — | n/m | -9.4% |
SMR | $1.5B | n/m | — | 535.9x | 116.3x | — | — | n/m | -41.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CCJ | $30.1B | 106.4x | 52.1x | 12.2x | 8.6x | 51.3x | 36.1x | 48.8x | 0.7% |
LEU | $2.0B | 26.9x | 42.9x | 4.5x | 4.2x | 19.6x | 18.6x | 8.9x | -14.5% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
BWXT | Revenue | +20.2% | +8.8% | +9.6% |
| EPS | +24.4% | +9.9% | +12.6% | |
OKLO | Revenue | — | +195.4% | +401.0% |
| EPS | +61.0% | +17.9% | +16.1% | |
SMR | Revenue | −70.0% | +628.0% | +174.1% |
| EPS | −77.2% | +19.4% | −5.9% | |
CCJ | Revenue | +2.4% | +12.8% | +8.8% |
| EPS | −7.5% | +88.3% | +27.3% | |
LEU | Revenue | +6.9% | +4.5% | −5.5% |
| EPS | −46.4% | +46.7% | −12.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
BWX Technologies builds the reactors, nuclear fuel and missile launch tubes that the US Navy's propulsion program buys from it as sole source, and in the September quarter it widened operating margin to 13.86% from 10.64% a year earlier while total backlog reached $8,556m, up from $8,398m three months before. The shares closed at $124.87 on 12 November, down 39.6% from six months earlier and 47.6% below their April peak.
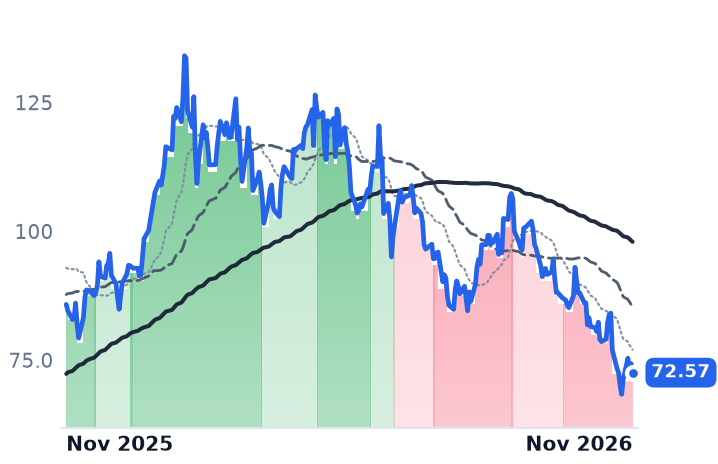
That decline arrived in step with Oklo, down 66.1% over the same six months, and NuScale, down 57.7%. The market has treated listed nuclear as a single expression of the AI-power trade, and the late-October trigger was financial rather than nuclear: Meta's raised capital-expenditure forecast reignited concern about data-center borrowing, sending Centrus, Oklo, NuScale and BWX Technologies to 52-week lows together. What separates them is whether anyone has signed anything.
The backlog rose through every month of the decline
BWXT's Government Operations segment grew revenue 4% to $639m in the quarter with operating income up 26% to $122.6m; Commercial Operations revenue rose 25%, 15% of it organic. A $189m annual naval fuel contract was booked. At the 2 November report the company raised the low end of 2026 free-cash-flow guidance to $350-360m and tightened non-GAAP earnings guidance to $4.72-$4.77 a share.
The de-rating is in the multiple alone. BWXT trades at 26.2x forward earnings against roughly 46x forward in May 2026, when the trailing multiple was 54.97x against 30.4x now, and consensus has 2026 earnings growing 24.4% before decelerating to about 10% in 2027.
Oklo's customer book is letters of intent, and its regulator is the Energy Department
Oklo's 10-Q for the nine months to 30 September records total revenue of $3.07m and describes non-binding letters of intent with Equinix and other customers that it is still working to convert into binding power purchase agreements. The 1.2 GW Ohio campus agreement with Meta, 900 MW of it under grid study, is not binding either. The company has not tendered a combined licence application to the Nuclear Regulatory Commission; its 2020 filing was dismissed without prejudice in January 2022, and it is building under Energy Department authorisation instead. First power at Aurora-Idaho slipped to 2028-2029 from 2027-2028.
Meanwhile operating cash burn rose 127% year on year to $110.9m for the nine months, and diluted shares rose 25.4%. "We have everything we need, and that's an incredible position to be in and something that hasn't been very present in the United States for decades," chief executive Jake DeWitte told investors on 6 November. He is right about the cash: $3.1bn, or $16.44 per diluted share against a $24.94 close, roughly five years at guided burn and capital spend.
NuScale has the approved design and no buyer of record
NuScale's quarterly revenue fell 96.6% to $0.281m and it has still sold no power module. Its commercial route runs through ENTRA1, which holds global exclusive rights to deploy the plants and whose September 2025 Tennessee Valley Authority agreement for up to 6 GW is non-binding; shareholder class actions followed a research report characterising ENTRA1 as thinly staffed. Management's own sequence puts the power purchase agreement first and module revenue last. "We are no longer simply designing and planning, we are manufacturing," chief executive John Hopkins said on 5 November of first-article work with Doosan Enerbility, which sits on the balance sheet as inventory recoverable only through a future equipment contract. Diluted shares rose 39.0%; liquidity is $1.9bn against about $65m of quarterly operating expense, and the stock trades at 0.99x book.
For the two developers the results account for the move. Nominal revenue, heavy dilution and a start-up date pushed a year later are the repricing of announcements into deliveries, and neither is a solvency story. For BWXT nothing in the disclosures moved that way; the likelier reading is rotation out of defence and nuclear multiples that had reached levels earnings could not hold.
One event would separate the three again. "I said at the beginning of this year that I expected us to have new orders for U.S. reactor plant builds in -- by the end of this year," chief executive Rex Geveden said on 2 November. "And I still think that's a possibility for us, but certainly no later than about the first half of the next year." A signed build order lands on the one company here already paid for work it has done.