

Teradyne Says Test's Cut of Chip Capex Rose to 8.1% From 6.4% in 2025
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
The three US-listed companies paid to prove that someone else's die works all reported accelerating September quarters, and all three were marked down by a fifth or more inside a month. Teradyne did $1.306bn of revenue, up 70%, including a record $301m of memory test; FormFactor's fourth straight record quarter lifted gross profit 91% year on year; Aehr raised its fiscal 2027 outlook to $150m after booking 1.4x what it billed.
The only soft disclosures are sequential: Teradyne's lower fourth-quarter margin guide and FormFactor's near-flat revenue guide, which management attributes to full plants rather than thin orders.
On price the shelf splits. Teradyne and FormFactor now trade near 14x gross profit, against 25.2x and 34.4x in May 2026. Aehr, at 67.6x, has unwound an extreme anchor rather than a business.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
TER | Teradyne | Test & Assembly Services | 🟢 Cont. Bull | −26.3% | +55.7% |
FORM | FormFactor | Test & Assembly Services | ⚠️ Emerging Bear | −24.5% | +80.3% |
AEHR | Aehr Test Systems | Test & Assembly Services | 🟢 Cont. Bull | −16.6% | +195.3% |
| Compared against · context, not the story | |||||
CAMT | Camtek | Test & Assembly Services | 🔴 Cont. Bear | −23.4% | +4.4% |
COHU | Cohu | Test & Assembly Services | 🟢 Cont. Bull | −24.0% | +98.9% |
6857.T | Advantest | Semiconductors | 🟢 Cont. Bull | −21.5% | +53.6% |
0522.HK | ASMPT | Semiconductors | 🟢 Cont. Bull | −33.1% | +24.5% |
ONTO | Onto Innovation | Fabrication Equipment & Materials | 🟢 Cont. Bull | −14.2% | +61.8% |
LRCX | Lam Research | Fabrication Equipment & Materials | 🟢 Cont. Bull | −18.8% | +52.3% |
AMAT | Applied Materials | Fabrication Equipment & Materials | 🟢 Cont. Bull | −13.9% | +72.9% |
ASML | ASML | Fabrication Equipment & Materials | 🟢 Cont. Bull | −11.2% | +48.2% |
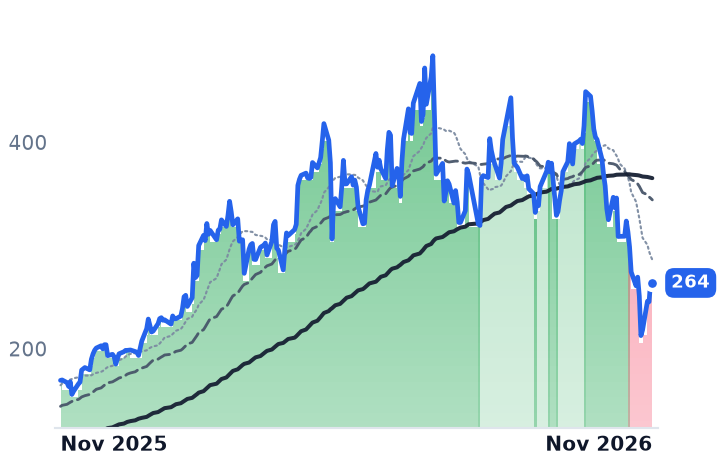
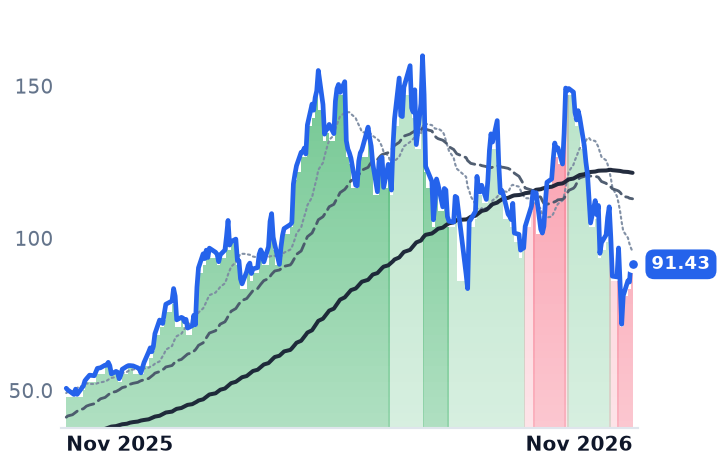
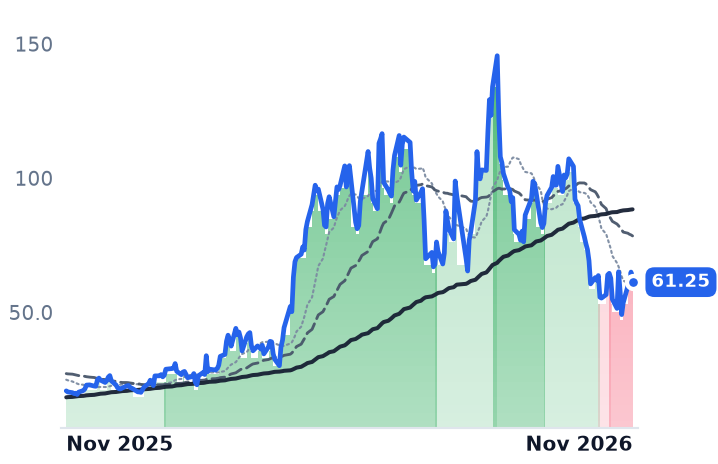
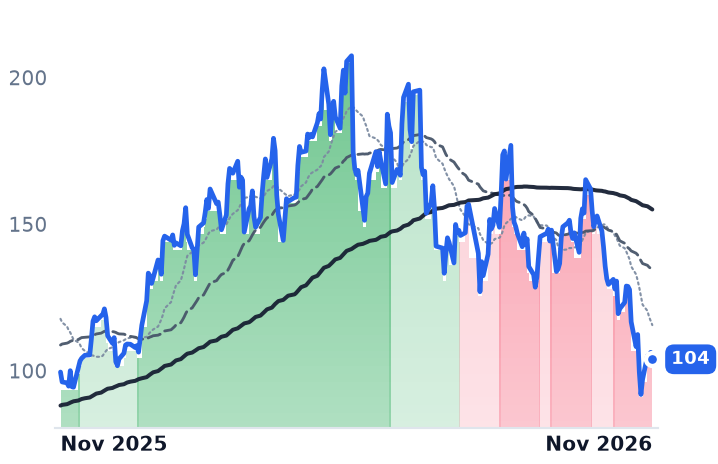
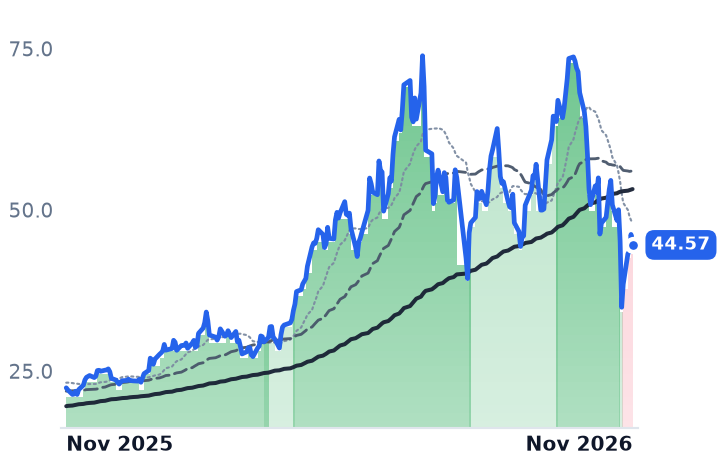
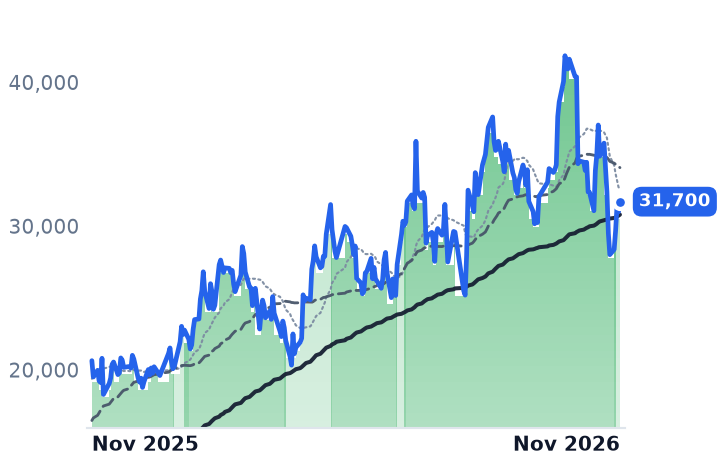
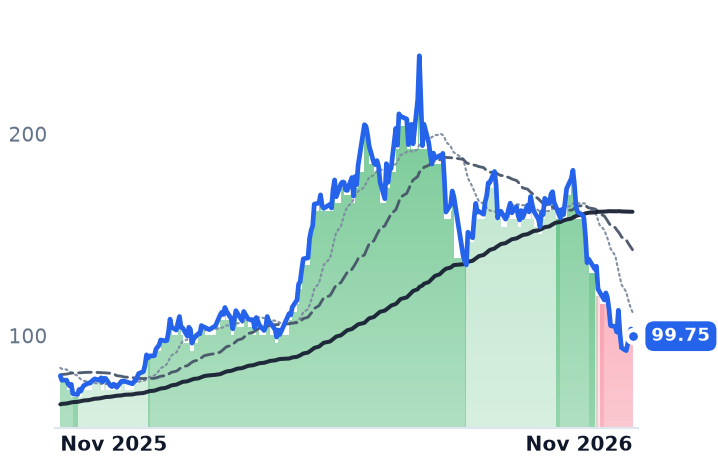
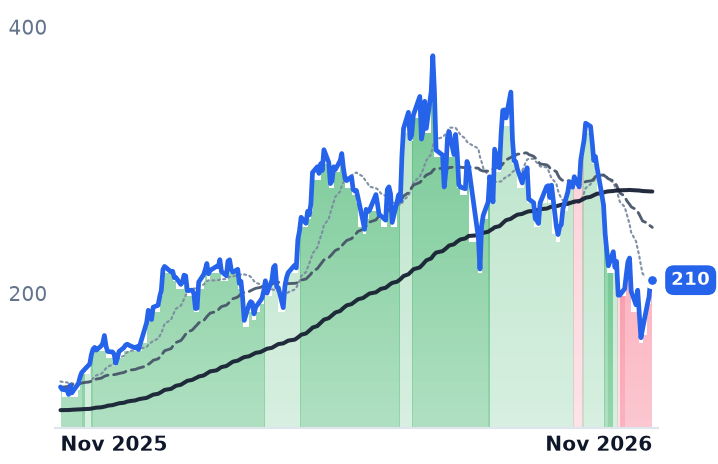
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TER | $41.2B | 30.1x | 27.8x | 8.2x | 7.9x | 13.9x | 13.3x | 22.8x | 2.5% |
FORM | $7.2B | 41.6x | 27.4x | 7.4x | 6.9x | 14.9x | 13.9x | 31.3x | 2.5% |
AEHR | $2.0B | — | — | 27.4x | 40.1x | 67.6x | 99.0x | 810.3x | -0.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CAMT | $4.5B | 33.7x | 26.9x | 8.3x | 7.6x | 16.6x | 15.2x | 35.8x | 0.0% |
COHU | $1.8B | n/m | 36.2x | 3.2x | 2.9x | 7.6x | 7.0x | 45.0x | 3.1% |
6857.T | $25.1T | 54.7x | 42.8x | 20.4x | 15.5x | 31.0x | 23.6x | 40.5x | 1.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
0522.HK | $74.0B | 72.6x | 30.4x | 3.1x | 4.0x | 8.1x | 10.3x | 36.8x | -0.4% |
ONTO | $8.5B | 64.7x | 21.4x | 7.6x | 5.9x | 15.1x | 11.7x | 35.1x | 3.0% |
LRCX | $250.8B | 29.7x | 20.8x | 9.6x | 7.1x | 18.8x | 13.9x | 24.3x | 2.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AMAT | $264.0B | 28.5x | 17.7x | 8.6x | 5.6x | 17.3x | 11.4x | 22.9x | 2.1% |
ASML | $549.1B | 36.7x | 34.6x | 12.5x | 12.4x | 23.1x | 22.8x | 29.8x | 4.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
TER | Revenue | +69.7% | +24.6% | +22.3% |
| EPS | +167.0% | +30.0% | +30.9% | |
FORM | Revenue | +34.7% | +24.7% | +26.6% |
| EPS | +199.0% | +29.7% | +39.0% | |
AEHR | Revenue | −17.7% | +0.0% | +197.3% |
| EPS | −211.4% | +0.0% | −800.4% | |
CAMT | Revenue | +20.5% | +35.0% | +17.0% |
| EPS | +12.5% | +42.4% | +18.0% | |
COHU | Revenue | +38.1% | +34.2% | +17.4% |
| EPS | +147643.1% | +122.8% | +35.8% | |
6857.T | Revenue | +43.8% | +49.2% | +22.8% |
| EPS | +98.8% | +74.8% | +23.7% | |
0522.HK | Revenue | +15.4% | −1.0% | — |
| EPS | +46.4% | +14.8% | — | |
ONTO | Revenue | +2.2% | +43.1% | +30.8% |
| EPS | −5.1% | +63.3% | +44.9% | |
LRCX | Revenue | +27.0% | +52.4% | +20.1% |
| EPS | +41.9% | +69.5% | +25.6% | |
AMAT | Revenue | +21.5% | +36.5% | +22.0% |
| EPS | +36.8% | +46.5% | +31.2% | |
ASML | Revenue | +36.8% | +29.7% | +25.6% |
| EPS | +66.3% | +38.0% | +32.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Chipmakers are handing a larger share of their equipment budgets to the companies that verify the parts work, and the September quarter is where that shift turned into revenue. "The portion of semi CapEx associated with test is increasing as well," Teradyne chief executive Gregory S. Smith told investors on October 28. "From 6.4% in 2025 to 8.1% for the first 8 months of 2026."
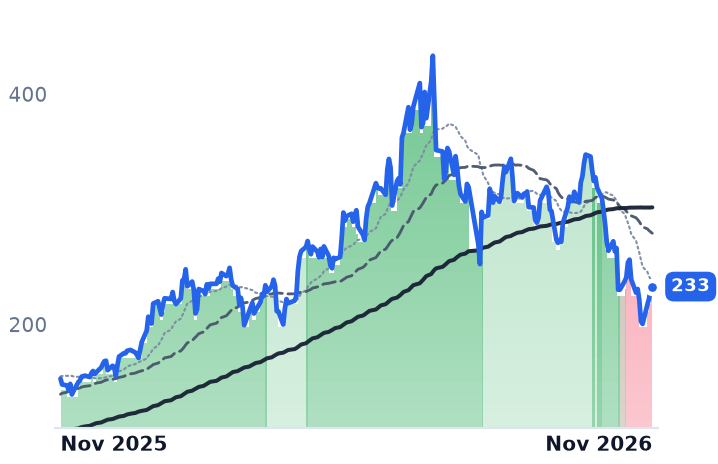
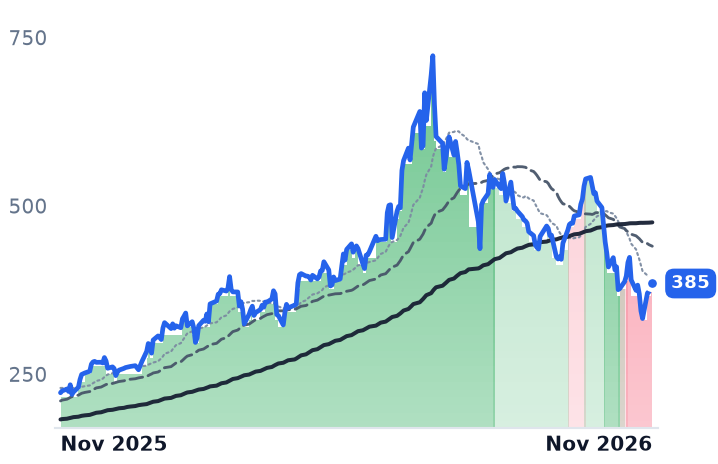
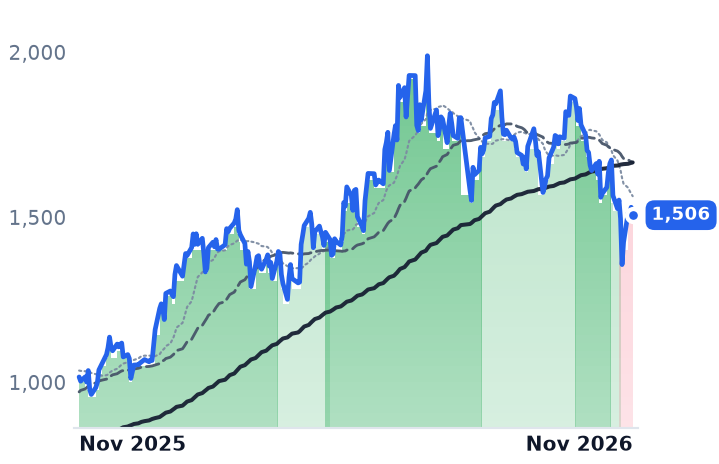
That is the mechanism the back-end shelf has been priced on all year, and it was read this autumn as a capex-timing trade: when the duration of the hyperscaler build came into question, the test names' order books were supposed to pause with it. What the September filings disclose instead is more content per tested die, more consumable revenue, and in one case a supplier that has run out of factory. Teradyne fell 28.5% over the 30 sessions to November 12, FormFactor 26.9% and Aehr 19.0%, and the dates of those declines sit outside the three companies' own disclosures.
Where the extra capex points landed
Teradyne, which sells the automated testers that verify chips at wafer and packaged stages, did $1,305.95m of revenue in the quarter ended September 27, up 69.8%, with operating income up 176.6% to $402.0m. Semiconductor Test was $1,072m of that, or 82% of the company, so the group number is a test read; the Universal Robots cobot business contributed $96m, grew 28% and turned profitable, and is too small to move either way. Memory test set a record at $301m, a fourth consecutive quarter above $200m on high-bandwidth memory and DRAM, with a NAND resurgence behind it.
The one soft line is the fourth quarter: $1.25bn to $1.35bn of revenue, flat sequentially at the midpoint, with gross margin guided to 57.5–58.5% against 59.1% delivered. Secondary coverage ties the post-print fall to that margin guide rather than to the revenue line, which came in above consensus.
A probe card is bought by the wafer, and FormFactor has no floor space left
FormFactor sells probe cards, the consumable interface that touches the wafer at test, and its quarter was its fourth straight record: $280.5m of revenue, up 38.4%, with gross profit up 90.7% and GAAP gross margin at 54.7% against 39.7% a year earlier. Its 10-Q attributes roughly 75% of the year-over-year increase in DRAM product revenue to high-bandwidth memory designs, even though mix within the quarter tilted toward DDR5 as customers chased a DDR5 contract price that went from $8.70 a 16Gb chip in October 2025 to about $48 in September 2026.
"We delivered again record DRAM revenue and at the same time, delivered record or near record company gross margins," chief executive Mike Slessor said on October 28. "That's something you would have not seen from the FormFactor of the past." The fourth-quarter guide of $285m plus or minus $10m is about 1.6% sequential growth, which management puts down to existing capacity being at its limit. Chief financial officer Aric McKinnis set the release date on that constraint: "Exiting 2027, we expect Farmers Branch will have the capability to produce about $400 million in annual probe card revenue."
Teradyne has bought into the bottleneck. It agreed to invest $300m of equity in FormFactor alongside a multi-year collaboration on probe and interface technology for high-performance compute, advanced packaging, high-bandwidth memory and silicon photonics, expected to close in the fourth quarter. FormFactor frames it as an open-ecosystem effort and keeps its existing partnership with Advantest.
Aehr's blades outgrew its razors
Aehr sells wafer-level and package-level burn-in systems with WaferPak contactors attached. Revenue was a record $33.0m, up 200.9%, against quarters of $11.0m, $9.9m, $10.3m and $19.8m through fiscal 2026. Consumables were $13.5m, 41% of the quarter and more than five times the year-ago level, and are guided to about 35% of fiscal 2027 against 29–30% last year. Bookings of $46.7m were 1.4x revenue; effective backlog reached $109.3m as of November 1 from $80.6m at fiscal year-end, and the company raised its full-year outlook to $150m. Chief executive Gayn Erickson gave the per-die arithmetic on November 2: "For every million units shipped in a calendar year... you would need somewhere between 5 and 10 of our systems per million units per year... It's $35 million to $70 million for each million units." NAND burn-in, he said, is moving more slowly on limited new fab capacity.
Aehr's trend turned down on October 21, six sessions before it reported. The shares rose 26.5% the day after the print, to $65.11, then gave all of it back by November 5.
What the books account for, and what they do not
None of it. The markdown is uniform across the back-end: Camtek down 26.9%, Advantest 21.5%, ASM Pacific 33.1%, Cohu 29.2%, Lam Research 22.1% over the same 30 days. Advantest, Teradyne's direct rival in both SoC and memory test, reported record September results and raised full-year guidance and fell with the rest. Two dated sessions carry most of it: October 22, when Lam's supply-constrained December guide took the PHLX Semiconductor Index down more than 6%, and November 5, when semiconductor shares plunged on fears about the AI trade and all three protagonists fell about 15% in one day. What is being repriced is the duration of the data-center build, not this quarter's wafer starts.
The repricing does not land evenly. Teradyne at 13.9x trailing gross profit, against 25.2x in May 2026, and FormFactor at 14.9x against 34.4x, have each had roughly half their multiple removed while gross profit grew 72% and 91%. Aehr at 67.6x trailing gross profit has fallen 57.9% from its peak and still carries the dearest valuation of the three; measured against its own raised $150m guide, the $2.0bn market capitalization is nearer 13x sales. The caveat on Aehr belongs with it: 138 employees, a lumpy book, and a $22m follow-on order from one lead AI-processor customer doing much of the work.
Smith was blunt about why the old framework no longer reads this business. "The patterns that we saw up through 2024 are over," he said on October 28. "There has been a seismic shift in the semiconductor test market that started in 2024 and really took hold in 2025." Teradyne can now see more than two quarters out, against a historical thirteen weeks of visibility. The market spent this month deciding it would rather not look that far.