

Fair Isaac Froze the FICO Score Price That Produced All of Last Year's Growth
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Fair Isaac's fiscal 2026 was an administered price increase wearing a growth company's clothes, and the lever is now clamped shut. Revenue rose 27.3% to $2.535bn and operating margin reached 49.9%, but the company's own fourth-quarter release attributes the 39% rise in business-to-business Scores revenue to a higher mortgage score unit price "partially offset by a decline in mortgage originations volume."
The wholesale mortgage score price went from $4.95 to $10, and under the Preferred Program launched in October it stays at $10 through 2027 — sold to lenders that pull FICO on all mortgage applications. Management withheld fiscal-2027 guidance entirely and said it will stop disclosing prices and program terms.
The business explains the markdown only once read forward: consensus has FY27 revenue up 2.3% and net income down 3.7%, with the Mortgage Bankers Association forecasting 5.0 million loans next year.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
FICO | Fair Isaac | Data, Analytics & Intelligence | 🔴 Cont. Bear | −0.3% | −58.7% |
| Compared against · context, not the story | |||||
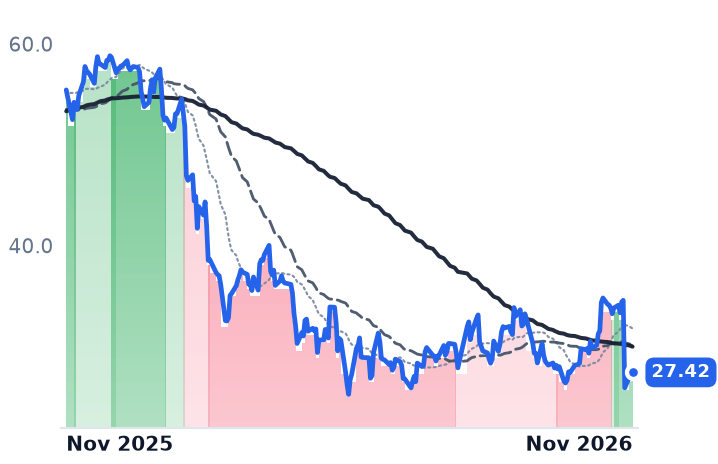
BL | BlackLine | Other | 🔴 Cont. Bear | −6.5% | −50.5% |
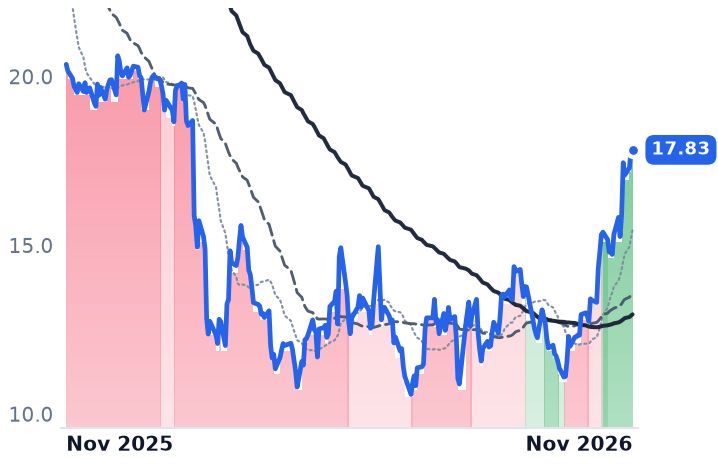
VERX | Vertex | Commerce & Digital Payments | 🌱 Emerging Bull | +40.0% | −12.4% |
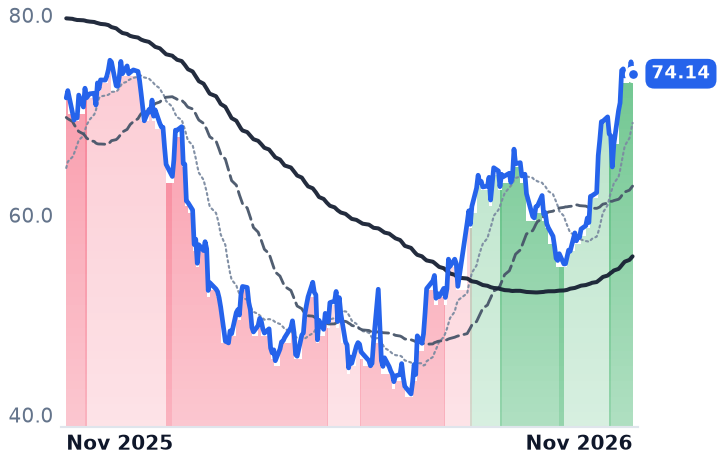
QTWO | Q2 | Commerce & Digital Payments | 🟢 Cont. Bull | +25.1% | +3.4% |
TYL | Tyler Technologies | Industry-Specific Platforms | 🌱 Emerging Bull | +22.2% | −8.8% |
NCNO | nCino | Commerce & Digital Payments | 🟢 Cont. Bull | +13.5% | −12.1% |
ALKT | Alkami Technology | Commerce & Digital Payments | 🔴 Cont. Bear | +1.5% | −29.9% |
GWRE | Guidewire Software | Industry-Specific Platforms | 🟢 Cont. Bull | −4.4% | −27.5% |
SSNC | SS&C Technologies | Enterprise Resource Planning | 🟢 Cont. Bull | −2.8% | −5.5% |
EFX | Equifax | Workforce Data & Analytics | 🌱 Emerging Bull | +27.1% | −8.1% |
TRU | TransUnion | Consumer Credit Reporting | 🌱 Emerging Bull | +23.1% | +0.4% |
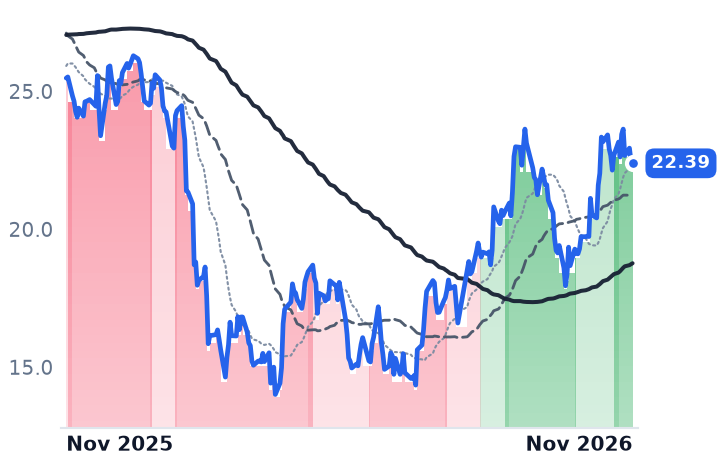
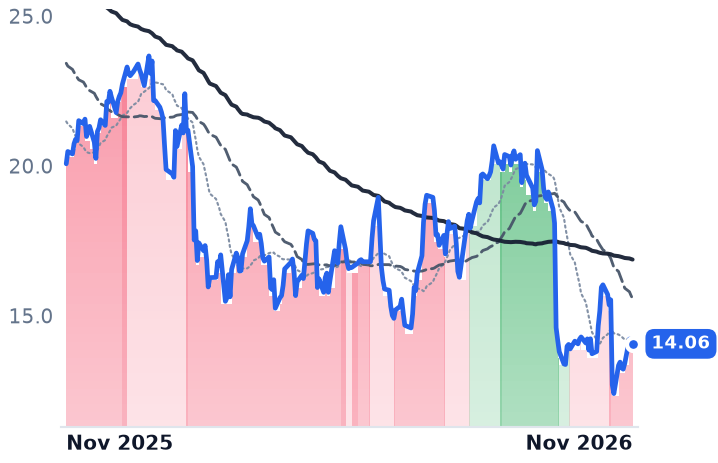
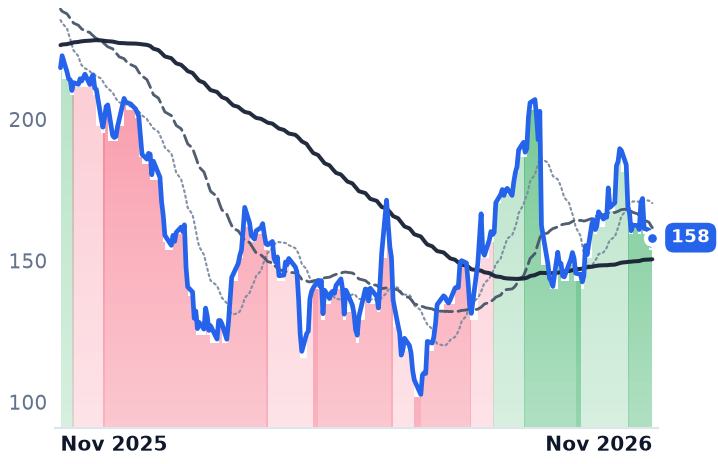
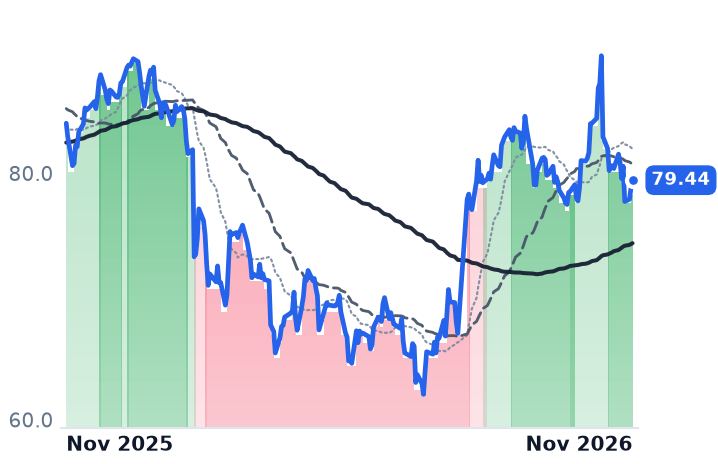
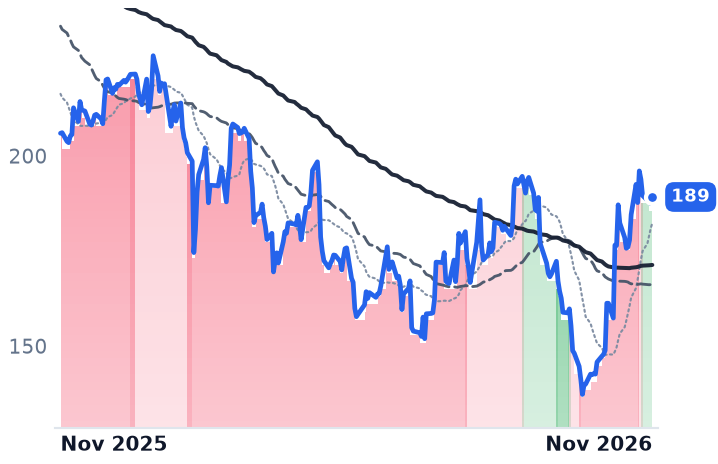
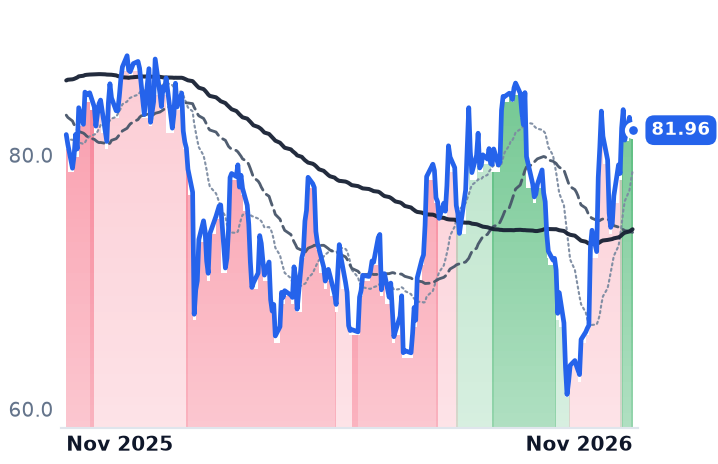
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FICO | $15.3B | 19.7x | 16.2x | 6.1x | 5.9x | 7.0x | 6.9x | 16.1x | 6.9% |
BL | $1.6B | 40.2x | 11.1x | 2.1x | 2.1x | 2.8x | 2.7x | 19.0x | 10.9% |
VERX | $2.9B | n/m | 21.1x | 3.6x | 3.5x | 5.7x | 5.6x | 55.8x | 2.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
QTWO | $4.7B | — | 26.9x | — | 5.2x | — | — | 27.6x | 4.9% |
TYL | $16.8B | 52.6x | 32.2x | 6.8x | 6.6x | 14.3x | 13.9x | 30.0x | 4.4% |
NCNO | $2.4B | — | 17.1x | — | 3.7x | — | — | 28.4x | 5.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ALKT | $1.5B | — | 16.9x | — | 2.9x | — | — | 286.0x | 3.6% |
GWRE | $12.8B | — | 37.4x | — | 7.5x | — | — | 61.6x | 2.3% |
SSNC | $18.5B | 22.1x | 11.0x | 2.8x | 2.7x | 5.7x | 5.7x | 11.4x | 9.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EFX | $17.7B | 26.2x | 17.6x | 2.7x | 2.6x | 4.9x | 4.7x | 12.1x | 6.3% |
TRU | $12.8B | 17.5x | 13.8x | 2.6x | 2.5x | 4.7x | 4.5x | 9.6x | 6.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
FICO | Revenue | +27.2% | +2.3% | +5.5% |
| EPS | +44.6% | +4.0% | +8.9% | |
BL | Revenue | +8.6% | +8.5% | +9.3% |
| EPS | +19.1% | +10.5% | +14.6% | |
VERX | Revenue | +10.9% | +10.5% | +10.8% |
| EPS | +32.5% | +22.8% | +20.4% | |
QTWO | Revenue | +12.5% | +10.2% | +10.0% |
| EPS | +17.9% | +23.8% | +17.2% | |
TYL | Revenue | +8.6% | +9.9% | +9.8% |
| EPS | +14.8% | +18.9% | +14.1% | |
NCNO | Revenue | +9.8% | +8.9% | +8.6% |
| EPS | +25.2% | +45.3% | +19.9% | |
ALKT | Revenue | +19.9% | +14.1% | +14.7% |
| EPS | +60.9% | +28.3% | +26.5% | |
GWRE | Revenue | +23.8% | +17.2% | +15.6% |
| EPS | +41.5% | +20.0% | +27.5% | |
SSNC | Revenue | +8.4% | +5.1% | +4.9% |
| EPS | +17.7% | +8.6% | +8.4% | |
EFX | Revenue | +11.2% | +8.3% | +9.7% |
| EPS | +11.8% | +17.4% | +21.0% | |
TRU | Revenue | +13.8% | +8.2% | +8.1% |
| EPS | +13.5% | +15.0% | +15.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Fair Isaac closed its fiscal year on 30 September with what its chief executive called the most successful twelve months in the company's history, and then declined to tell investors what the next twelve would look like. On the 4 November call the company withheld fiscal-2027 revenue and earnings guidance altogether, citing mortgage pricing programs still being finalized with lenders, elevated rates suppressing volumes, and a fiscal year that begins in October while mortgage score pricing resets in January.
Fair Isaac licenses the FICO credit score, which lenders buy through the three bureaus and their resellers, and sells the FICO Platform decisioning software to banks. The market had treated the first business as a toll whose price the company sets at will. The year just filed shows that the toll was the entire growth story — and that its price is now fixed.
Seventy-two percent more mortgage revenue on fewer pulls
The fourth-quarter release states the mechanism in the company's own words: business-to-business Scores revenue rose 39% "primarily attributable to a higher mortgage origination scores unit price, partially offset by a decline in mortgage originations volume." Mortgage origination revenue grew 72% in the quarter while score volumes fell high single digits. Auto originations added 11% and card and personal loan 12%. Scores revenue of $1.652bn for the year was 65% of the $2.535bn group total, up from roughly 59% a year earlier.
The price behind that did roughly double, from $4.95 a mortgage score to $10. Under the FICO Preferred Program launched in October, it holds flat at $10 for 2027 — available to lenders and brokers buying tri-merge reports through resellers that commit to pulling FICO on 100% of applications. That is pull-through insurance bought with price certainty. Mizuho's Sean Kennedy cut his target to $986 from $1,063 on flat mortgage score pricing in 2027.
The separate Mortgage Direct License Program routes around the bureaus, letting resellers calculate and distribute scores themselves; FICO has signed resellers representing about 73% of mortgage reseller volume, including Xactus. Its Performance Model — a $4.95 royalty plus a $33 fee per borrower when the loan closes — remains pending certification by the government-sponsored enterprises, so the half of the economics tied to closings is not usable in the conforming market.
Someone else sets the units
The Federal Housing Finance Agency directed Fannie Mae and Freddie Mac to price loans on a single adjustment grid whether scored with Classic FICO or VantageScore 4.0, removing the 20-point penalty previously applied to the rival. TransUnion extended $0.99 VantageScore pricing through 2028 and counts more than 1,100 mortgage lenders using it. And the Mortgage Bankers Association expects 5.0 million loans in 2027, down 5.6%.
Chief executive William Lansing's answer is the newer model. "10T is the best score available," he said on 4 November. "All the trend and momentum is in the direction of 10T adoption, and I think 2027 will be a big year for 10T." Eighty-four lenders representing $684bn of eligible annual originations have joined its adopter program, and the Federal Housing Administration will accept it from 1 January 2027. Conforming certification is still outstanding.
The software book is compounding underneath
Software annual recurring revenue reached $851m, up 14%, with platform ARR of $453m up 72%. "Our dollar-based net retention rate in the quarter was 112%," chief financial officer Steven Weber told investors. "Platform NRR was 156%." The non-platform book retained 82%, shrinking at an 18% annual rate, and segment operating margin reached 61% from 55%.
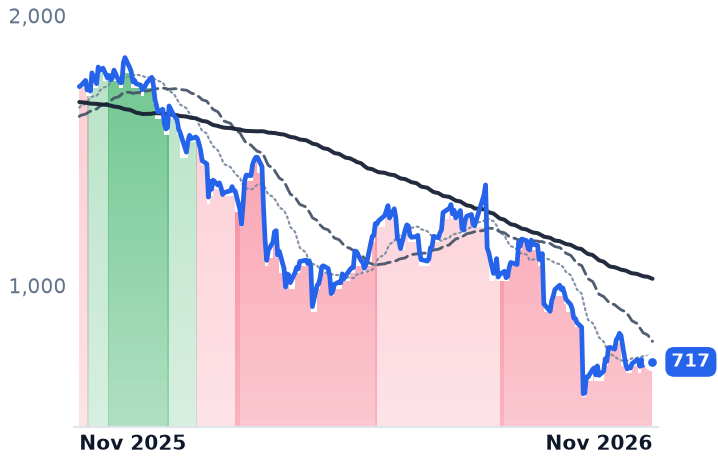
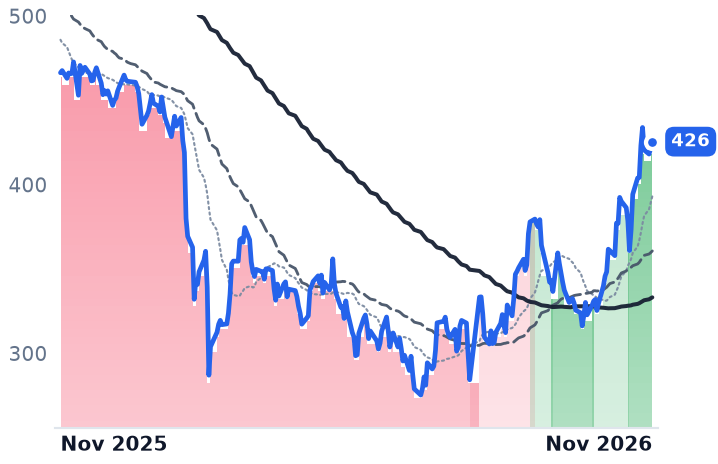
The shares are down 59.7% over twelve months. The two worst sessions were regulatory, not operational: down 29.2% on 29 September on the FHFA grid decision and TransUnion's pricing, and 13.2% on 26 October when the flat $10 was announced. The 4 November print itself moved them 3.2%.
What the compression is actually paying for
Fiscal 2026 contradicts the markdown on reported numbers — revenue up 27.3%, gross margin from 82.2% to 86.1%, free cash flow of $1.034bn — and supports it on forward ones. Consensus has fiscal-2027 revenue growing 2.3% and net income falling 3.7%, with earnings per share still up 4.0% because the diluted count fell 13.2% in two years on $3.028bn of buybacks, now paused for term-loan repayment at 3.29x leverage. At the 12 December 2025 peak of $1,844.98 the shares carried roughly 69x trailing earnings; today's $717.38 is 19.7x, and 7.0x trailing gross profit against about 27x then. The forward 16.2x rests on an estimate cut from $49.65 in mid-October to $44.35 — a denominator the company itself will not stand behind.
Lansing was explicit about why. "We were attacked because we're transparent and clear about our score price," he said on 4 November. "We're not going to share what the prices are." The toll becomes a private matter between Fair Isaac and the resellers, and the only public read on it will be a revenue line whose two drivers are now pulling in opposite directions.