

Microchip Guided December Down on High-Margin Orders It Cannot Ship Until March
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
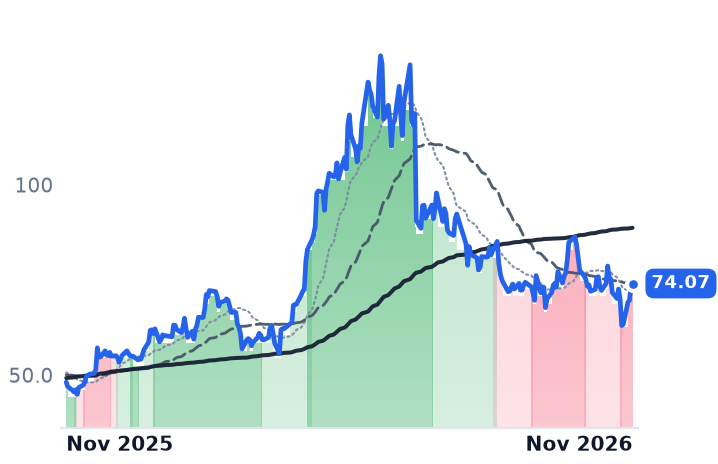
Microchip's December guidance reads like a demand break, and its own order book says the reverse. The company reported September revenue of $1.62bn, up 42.2% year on year and a fifth consecutive quarterly acceleration, then guided December revenue to between -3% and +1% sequentially with adjusted gross margin of 64–65% against 66.5%.
Management itemised the step-down: $53m of one-time items booked at 100% gross margin, lower utilisation, and high-margin backlog pushed to March because there is no capacity to build it. Book-to-bill was described as well above one, with backlog building through October.
Texas Instruments and Analog Devices sit on the other side of the same quarter, gross margins at 64.2% and 67.3%. The margin markdown at Microchip is earned. The broken-demand reading underneath it is not in the filings.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
MCHP | Microchip Technology Incorporated | Processors & Accelerators | 🔴 Cont. Bear | −12.8% | +15.0% |
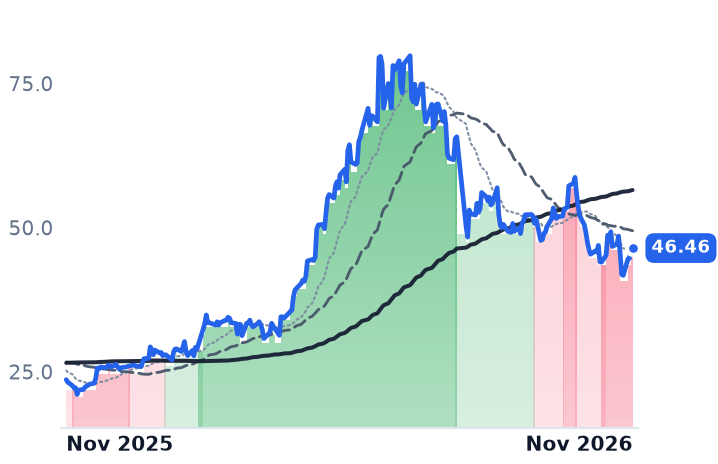
TXN | Texas Instruments Incorporated | Analog & Power Management | 🟢 Cont. Bull | +11.1% | +94.9% |
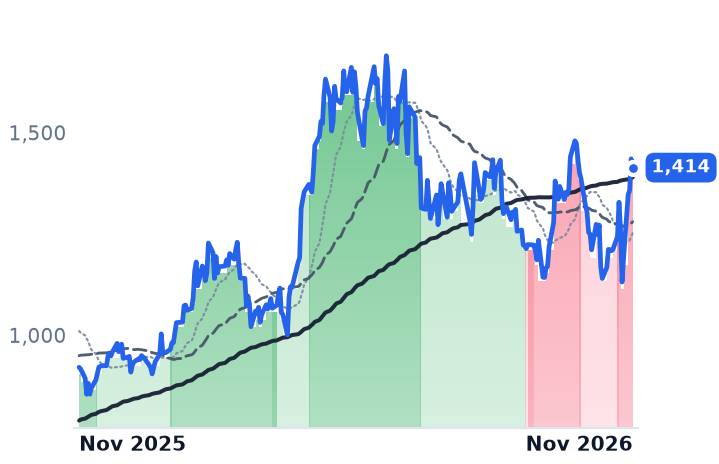
ADI | Analog Devices | Analog & Power Management | 🟢 Cont. Bull | +1.1% | +73.5% |
| Compared against · context, not the story | |||||
NXPI | NXP Semiconductors | Processors & Accelerators | 🔴 Cont. Bear | +21.7% | +34.6% |
ON | ON Semiconductor | Analog & Power Management | 🔴 Cont. Bear | +1.0% | +53.9% |
STM | STMicroelectronics | Processors & Accelerators | ⚠️ Emerging Bear | −2.1% | +96.6% |
MPWR | Monolithic Power Systems | Analog & Power Management | ⚠️ Emerging Bear | +12.7% | +53.5% |
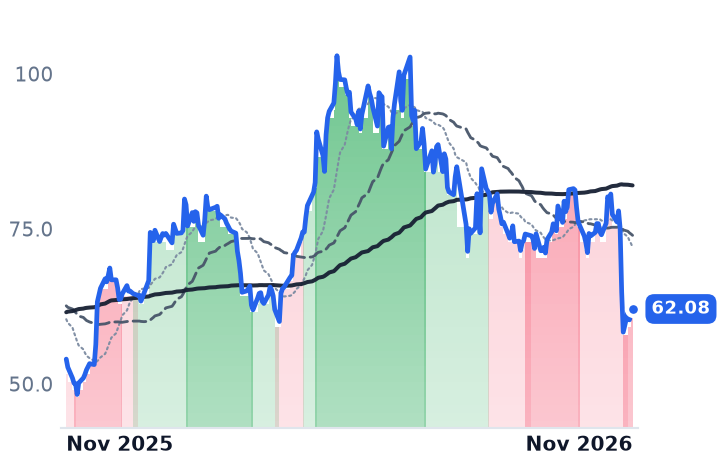
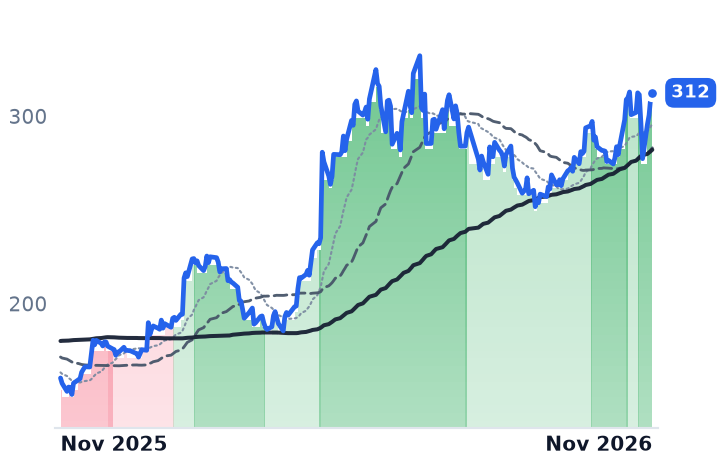
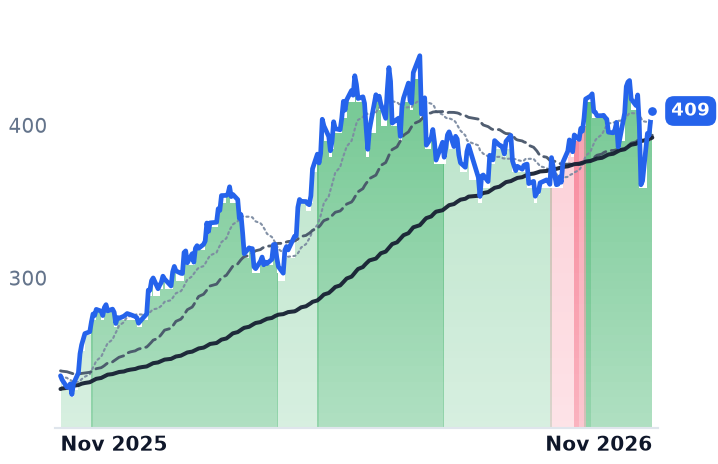
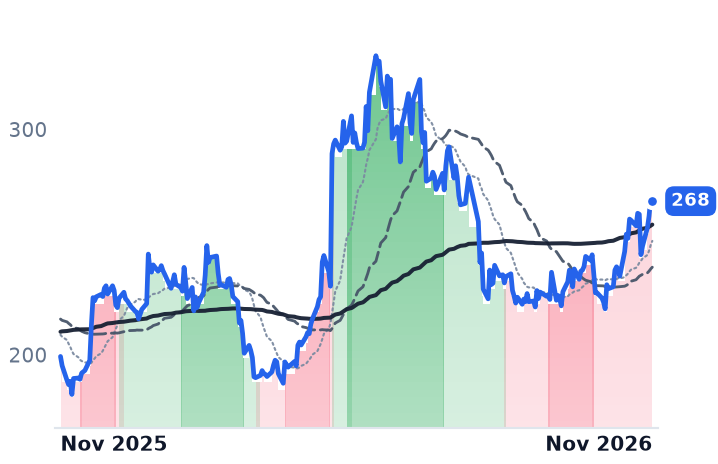
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MCHP | $33.8B | 46.5x | 17.2x | 6.0x | 5.3x | 9.6x | 8.4x | 19.0x | 4.3% |
TXN | $285.5B | 40.4x | 34.6x | 13.8x | 12.8x | 22.8x | 21.2x | 26.9x | 2.6% |
ADI | $198.3B | 48.3x | 24.3x | 14.3x | 10.7x | 21.7x | 16.2x | 29.2x | 2.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NXPI | $62.6B | 19.4x | 16.3x | 4.5x | 4.4x | 8.1x | 7.8x | 13.4x | 5.8% |
ON | $24.6B | 36.0x | 19.3x | 3.9x | 3.7x | 10.1x | 9.7x | 15.2x | 6.6% |
STM | $42.0B | 79.8x | 35.0x | 3.0x | 2.9x | 8.4x | 8.2x | 17.7x | 1.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MPWR | $65.7B | 73.9x | 46.2x | 17.6x | 15.2x | 31.8x | 27.4x | 54.2x | 0.9% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
MCHP | Revenue | +6.2% | +36.8% | +15.5% |
| EPS | +20.7% | +130.6% | +22.0% | |
TXN | Revenue | +26.4% | +17.7% | +11.3% |
| EPS | +65.2% | +28.4% | +16.3% | |
ADI | Revenue | +38.1% | +22.9% | +12.0% |
| EPS | +65.9% | +30.6% | +18.5% | |
NXPI | Revenue | +17.0% | +12.3% | +9.3% |
| EPS | +29.2% | +20.5% | +17.3% | |
ON | Revenue | +10.1% | +14.9% | +12.4% |
| EPS | +40.9% | +44.3% | +27.1% | |
STM | Revenue | +23.2% | +20.4% | +12.7% |
| EPS | +105.5% | +102.7% | +45.9% | |
MPWR | Revenue | +55.8% | +51.2% | +24.7% |
| EPS | +64.5% | +58.9% | +25.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Microchip Technology told investors on 5 November that it had orders it could not ship, and guided the December quarter lower. The company, which sells 8- to 32-bit microcontrollers along with analog, interface and timing parts to industrial, automotive, computing and aerospace customers, had just reported September-quarter revenue of $1.6215bn, up 42.2% year on year and 9.2% sequentially, its fifth consecutive quarter of accelerating growth. December revenue was guided to between -3% and +1% sequentially. The shares fell 13.6% that session and a further 10.0% the next, from $75.07 on 4 November to $58.35 on 6 November, a 22.3% fall across the two days.
The print was read as the analog recovery giving out. What the disclosures describe is a shortage: bookings "very strong with book-to-bill well above one," backlog building through October and into the first days of November, distributor inventory at 25 days, flat sequentially and at the lower end of its historical range, and lead times stretched to 6–32 weeks from a historical 4–8 as foundry, outsourced assembly and test, and internal fab capacity is crowded out by artificial-intelligence orders.
The inventory is accumulating on Microchip's own balance sheet: company stock rose nine days in the quarter to 184 days, or $1.117bn.
The $53m that does not come back
The December margin step has an itemised cause. Microchip loses $53m of one-time items booked at 100% gross margin — $21m of distribution inventory pricing, $22m of licensing, $10m of customer contract recognition — on top of high-margin backlog pushed into March and beyond and lower utilisation, taking adjusted gross margin to 64–65% from 66.5%. Strip the one-timers out and the guidance midpoint is 5–7% better than normal seasonality, with March backlog described as much better than December's was at the same point.
The sell side's 6 November response was arithmetic rather than a change of mind. Evercore ISI cut its target to $75 from $117 and kept Outperform; Needham went to $85 from $120 at Buy, Wells Fargo to $70 from $80 at Equal-Weight. Microchip now trades at 17.2x forward earnings against 46.5x trailing, and 8.4x forward gross profit against 10.65x in early October. Its capital return is the weakest of the three: net debt at 2.36x EBITDA, buybacks awaiting further deleveraging, the dividend held flat.
Texas Instruments is collecting on fabs built ahead of demand
The depreciation drag that was supposed to sit on Texas Instruments, whose 300mm plants were tooled for a demand level that had not arrived, has gone the other way. Gross margin ran 55.9%, 58.0%, 61.4% and 64.2% across four quarters, against an annual trough of 57.0% in 2025, while operating margin moved from 33.3% to 47.5%. Capital expenditure was $463m in the quarter and $2.6bn over twelve months against a 2026 guide of $2–3bn, with 2027 detail deferred to a February update even as consensus models a 48.0% operating margin for that year.
"Revenue was $6.1 billion an increase of 11% sequentially and an increase of 28% year over year," chief executive Haviv Ilan said on 21 October. Data centre is now roughly 13% of revenue and grew about 95%; automotive, the end market this layer is supposed to live on, grew mid-teens. At 34.6x forward earnings against 40.4x trailing — barely a 14% compression — and 21.2x forward gross profit, Texas Instruments is the dearest of the three, having been recorded at 31.3x forward in September.
Analog Devices shows the same shape without the sunk plant. August-quarter revenue was $4.02bn, up 39.6%, gross margin 67.3% against 59.0% in January 2025, and communications revenue of $654.5m rose 84%, of which data centre is 80%, against automotive of $998.2m up 16%. Management expects the higher utilisation of its own factories to persist through the upcycle and guided fiscal fourth-quarter adjusted gross margin to about 74%. It trades at 24.3x forward against 48.3x trailing, the widest expectation gap of the three, and reports on 24 November.
What else happened on 5 November
Microchip's first down leg was not its own. The iShares Semiconductor ETF fell as much as 11% that day after senior Democrats called for a national data-centre moratorium following the midterms, with UBS strategists estimating roughly 30% of expected 2028 data-centre additions could slip. That lands on the fastest-growing end market at all three of these companies, including the one whose chief executive, Steve Sanghi, said that day: "I have been saying it, that data center is in the bubble."
Across fourteen US-listed analog and mixed-signal names the median move over the past thirty days is 2.3%, NXP Semiconductors up 20.0% at one end and Microchip down 14.7% at the other. So the guide-down is real, the margin step is earned, and the demand collapse implied by a fifth of Microchip's equity value is absent from the order book. What is genuinely open is the second derivative Sanghi was pointing at, and whether a backlog held up by shortages survives it.
Microchip's foundry and assembly partners put through new price increases in January, and management has said it will not raise customer prices again so soon, having done so in August: "we don't want to push the luck." Capacity arrives only incrementally through mid-2027. The orders pushed into March are at once the evidence of demand and the thing that cannot be delivered.