

One Federal Factory Credit Lifted Nextpower's Gross Margin Nine Points and Cut Array's
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Both big US solar tracker makers book the federal advanced-manufacturing credit as a reduction to cost of sales, which means their reported gross margins measure a subsidy as much as a price — and in the September quarter the line moved in opposite directions.
Nextpower, formerly Nextracker, recognized $192.3m of the credit in the fiscal first half, about 28% of first-half gross profit, and its quarterly gross margin still fell to 31.1% from 32.2%. Array took a $10.9m provision against a credit receivable, which pushed its margin down to 21.0% from 26.9% on revenue that fell 16.1%.
Order books grew in dollars at both — Nextpower above $6bn, Array a record $2.6bn — but neither discloses megawatts, so no one outside can check what a tracked megawatt earns. The shares' five-session jump came from a broker pick, the midterms and Array's merger with Shoals, none of them orders.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
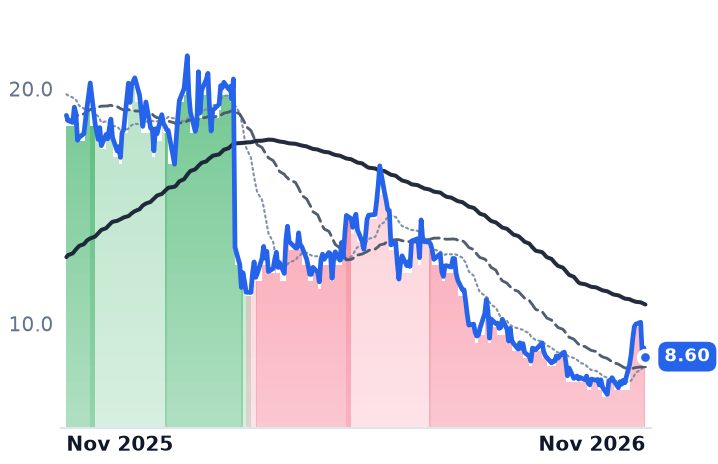
NXT | Nextpower | Tracking Systems | 🔴 Cont. Bear | +14.7% | +10.0% |
ARRY | Array Technologies | Tracking Systems | 🔴 Cont. Bear | +49.5% | −34.0% |
| Compared against · context, not the story | |||||
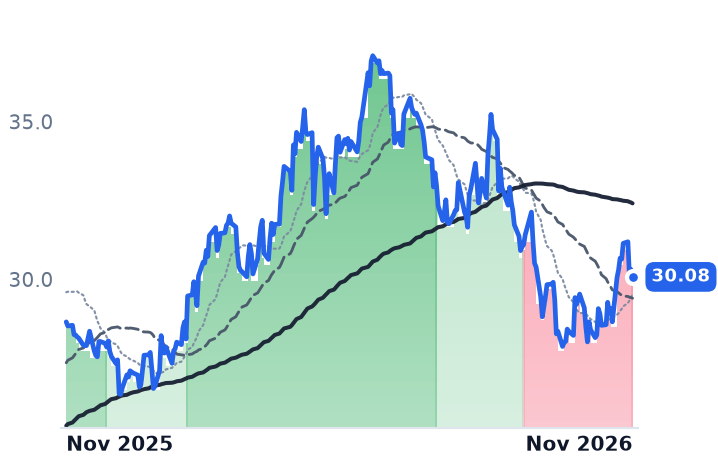
SHLS | Shoals Technologies | Balance Of System | ⚠️ Emerging Bear | +4.5% | +4.8% |
FSLR | First Solar | Modules | 🔴 Cont. Bear | −4.1% | −32.6% |
RUN | Sunrun | Residential Services | 🔴 Cont. Bear | +16.3% | −54.5% |
BEP | Brookfield Renewable Partners | Diversified Generators | ⚠️ Emerging Bear | +7.4% | +5.0% |
12-month price & trend
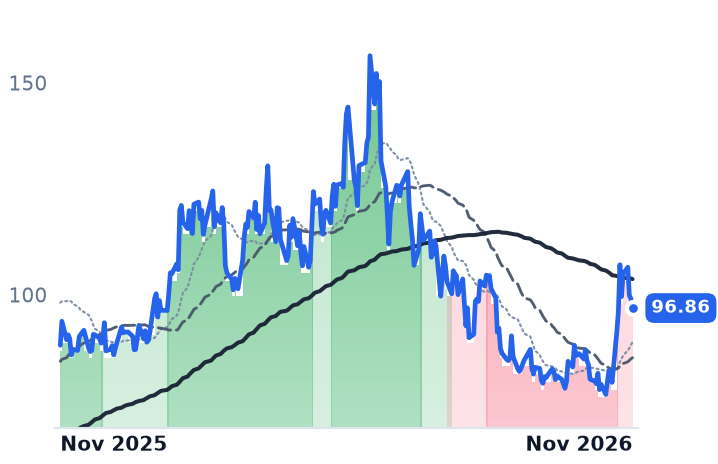
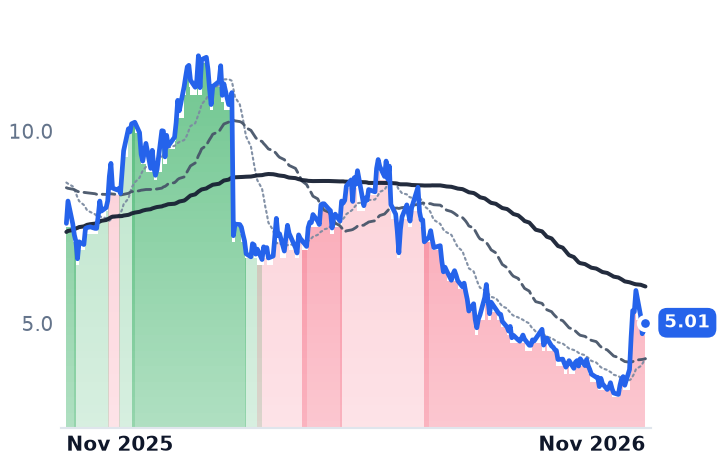
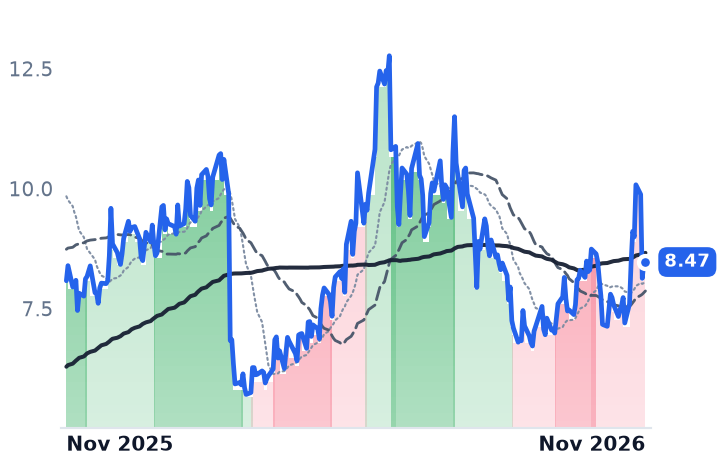
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NXT | $14.3B | 22.9x | 19.6x | 3.7x | 3.3x | 11.3x | 9.9x | 16.7x | 3.6% |
ARRY | $739.2M | n/m | 7.0x | 0.7x | 0.5x | 2.9x | 2.4x | n/m | 15.1% |
SHLS | $1.4B | 35.6x | 17.9x | 2.1x | 2.1x | 6.8x | 6.7x | 18.6x | -2.5% |
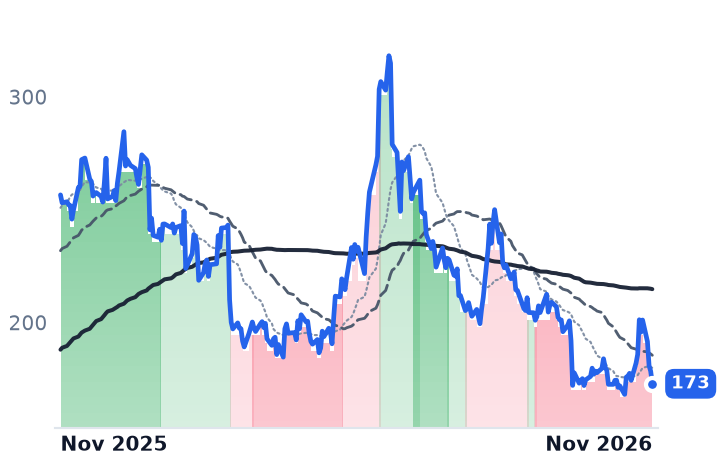
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FSLR | $18.5B | 9.9x | 9.8x | 3.7x | 3.9x | 7.5x | 7.9x | 6.8x | 1.3% |
RUN | $1.8B | 4.4x | 6.2x | 0.5x | 0.6x | 1.5x | 1.7x | 18.4x | -75.2% |
BEP | $8.7B | 62.8x | — | 1.4x | 1.3x | 5.6x | 5.3x | 9.6x | -54.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
NXT | Revenue | +22.3% | +24.8% | +19.2% |
| EPS | +13.8% | +9.3% | +20.6% | |
ARRY | Revenue | +10.1% | +14.5% | +5.7% |
| EPS | +2.6% | +28.8% | +7.9% | |
SHLS | Revenue | +38.9% | +9.3% | +8.5% |
| EPS | +15.9% | +26.8% | +14.0% | |
FSLR | Revenue | −6.3% | +19.4% | +12.9% |
| EPS | +20.7% | +31.7% | +20.0% | |
RUN | Revenue | +27.9% | +2.6% | +12.9% |
| EPS | −11.4% | −54.4% | +7.2% | |
BEP | Revenue | +3.4% | +9.5% | −3.3% |
| EPS | +11.4% | −10.5% | +9.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Nextpower, the Fremont company formerly called Nextracker that sells the steel, actuators and control software pointing utility-scale solar panels at the sun, reported record revenue of $1.11bn in the September quarter and a thinner gross margin than a year earlier. The reason those two facts sit together is an accounting line: the federal advanced-manufacturing credit for US-made components, which both big American tracker makers subtract from cost of sales, where a tax subsidy becomes indistinguishable from a better price.
The five-session leap in the tracker shares in early November was read as the cycle turning. The September-quarter filings say something narrower. Order books are growing in dollars at both companies, the price of a tracker per watt is still falling, and the margin line that would normally settle the argument is partly a function of who collected a credit and who wrote one off.
$192.3m that never came from a price
Nextpower recognized roughly $192.3m from the Section 45X credit as a reduction to cost of sales in the first half of fiscal 2027, worth 9.4 points of the half's 33.3% gross margin and about 28% of its $681.2m of first-half gross profit, according to its results filing. Strip it out and the half runs near 24%. The quarter-level disclosure is coarser still: about $99m of credits, vendor rebates and tariffs, net, with the subsidy and the tariff drag inside one number.
And the reported margin fell anyway, to 31.1% from 32.2%, with operating income up 12.8% on revenue up 22.5%. Management guided second-half adjusted gross margin to the high 20s, citing diesel costs up 80% year to date, elevated steel and freight, and initially lower margins on newly added products. "We are increasing our fiscal year 2027 outlook. We expect revenue of $4.2 billion to $4.45 billion, adjusted EBITDA of $890 million to $940 million and adjusted diluted EPS of $4.61 to $4.87 per share," chief financial officer Charles Boynton told investors on October 28.
Array booked the same credit backwards
Array Technologies, the Albuquerque maker of single-axis trackers and SmarTrack control software, took the mirror image. Its gross margin dropped to 21.0% from 26.9%, which the quarterly filing attributes primarily to a $10.9m provision against a 45X credit receivable; on the call the same-sized charge was described as a long-dated supplier rebate reserve. Revenue fell 16.1% to $330.2m, operating income nearly vanished at $3.6m, and full-year guidance came down to $1.34bn–$1.40bn from $1.4bn–$1.5bn, the company said, on shifts in delivery timing. Array has pointed to trade policy, permitting reviews and higher rates pushing projects back rather than away: its order book hit a record $2.6bn, up 42%, at a book-to-bill of 1.6 times.
Nextpower's book passed $6bn on more than $1bn of quarterly bookings, per its results release. Neither discloses backlog in megawatts, so the one number that would settle what a tracked megawatt earns cannot be computed from outside. Array's management supplied the only arithmetic on offer: a gigawatt of additional tracker sales is roughly $100m of revenue and about $30m of EBITDA.
Content attach is what both are actually buying
Tracker pricing per watt "continues to align with the broader solar cost reduction curve," Nextpower's team said on its call, with overall average selling price up only modestly on higher attach of non-tracker products, per the transcript. Non-tracker reached about 22% of revenue from roughly 14%. "Non-tracker bookings in the quarter were greater than 20%," president Howard Wenger said on October 28, including more than $100m of electrical balance-of-system orders.
Array bought the same thing in one move, agreeing on November 4 to an all-stock merger with Shoals Technologies, which makes the cable assemblies, combiners and wire management that wire a solar field, valued at about $1.32bn with Shoals holders ending up with roughly 65% of the combined company and closing expected in the first quarter of 2027, per the merger filing. "About 80% of the projects only had one of our products between the two company. So that unlocks a marketplace, a cross-sell marketplace opportunity of $2.5 billion, which is larger than the combined revenue of the two companies today," Shoals chief executive Brandon Moss said on November 4.
Five sessions, three catalysts, no orders
Nextpower rose about 15% on November 2 after Jefferies named it a Franchise Pick; the group then rose on Democratic congressional wins, with First Solar and Sunrun each up about 6%; Array added the merger. Roughly a third came back on November 10 as October inflation pushed the 10-year yield toward 5%. Over the full 30 days First Solar, the cadmium-telluride module maker, fell 6.0% and Shoals was flat, so this was not a repricing of US solar.
What the order books do not settle
The records are real and the margins are not yet. Nextpower's revenue has compounded from $1.46bn in fiscal 2022 to $3.56bn in fiscal 2026, which makes 19.6 times forward earnings against 22.9 times trailing a defensible price for a business whose guidance went up. Array at about 7 times forward earnings has no usable trailing multiple, because trailing earnings are negative, and the cheapness partly reflects more than $317m of preferred stock the sales multiple does not see. What neither price settles is the demand shape behind the credit deadline: First Solar has said developers are prioritizing 2028 safe-harbor dates while deferring procurement for 2029 and later, and those who missed the July 4, 2026 begin-construction test face a December 31, 2027 placed-in-service cliff.
A tracker sold into that rush is revenue now and a hole later. The honest reading of both order books is that they are full of projects racing a date, and that the margin they will print depends on a credit one of these two companies has already decided it may not collect.