

Building AI Racks Pays Sanmina Better Than Designing Them Pays Celestica
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Assembling racks for the AI buildout is supposed to be thin work: the customer's silicon, memory and power gear book as the builder's own revenue at little markup, so the top line multiplies while gross profit barely moves. On the latest quarters that describes one of these companies and not the other two.
Sanmina, which paid Advanced Micro Devices $2.55bn for ZT Systems' factories, lifted gross margin to 11.3% of revenue from 9.1% as rack volume scaled, and guided fiscal 2027 revenue to $17.5-19.5bn. Celestica, which designs what it builds, saw gross margin fall to 11.0% from 13.0% on 82.5% revenue growth, and discloses three customers at 66% of revenue combined. Jabil's gross line was flat.
The one-month markdown hit all six names in the group by 15% to 28% regardless.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
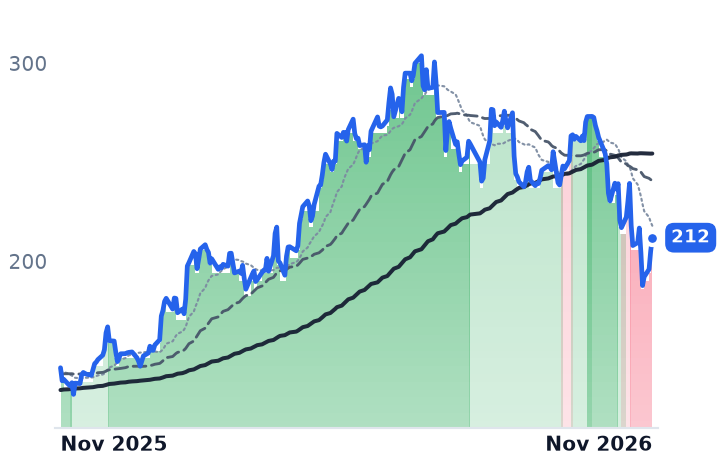
SANM | Sanmina | Contract Manufacturing | 🟢 Cont. Bull | −22.5% | −5.7% |
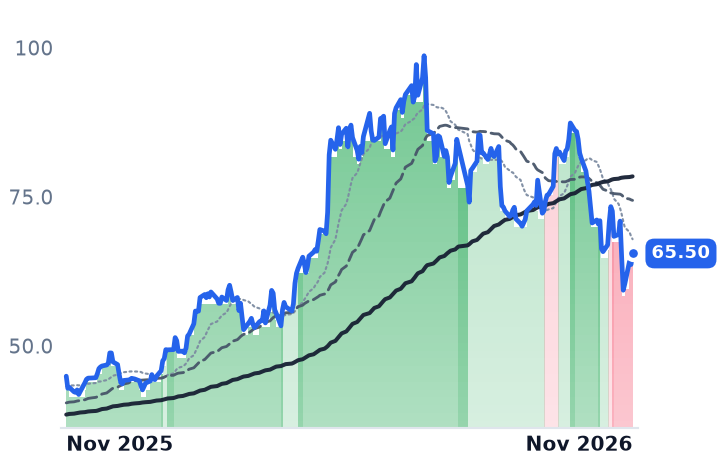
CLS | Celestica | Contract Manufacturing | ⚠️ Emerging Bear | −25.3% | −24.5% |
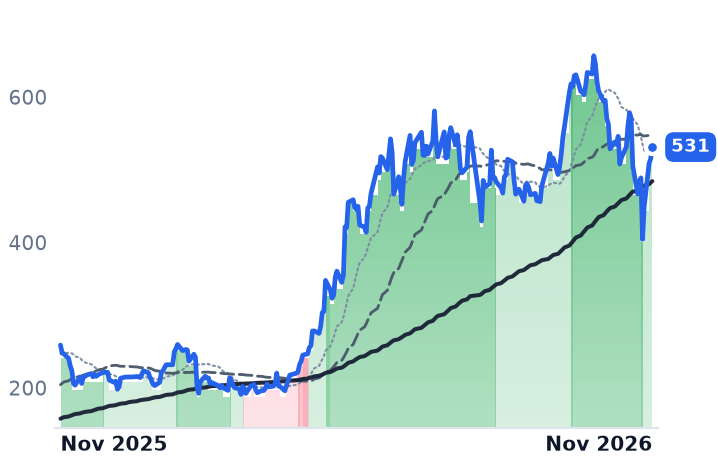
JBL | Jabil | Contract Manufacturing | ⚠️ Emerging Bear | −16.6% | +21.0% |
| Compared against · context, not the story | |||||
FLEX | Flex | Contract Manufacturing | ⚠️ Emerging Bear | −28.1% | +25.8% |
PLXS | Plexus | Other | 🟢 Cont. Bull | −16.7% | +44.9% |
BHE | Benchmark Electronics | Contract Manufacturing | 🟢 Cont. Bull | −15.5% | +45.8% |
AMD | Advanced Micro Devices | Processors & Accelerators | 🟢 Cont. Bull | −10.8% | +105.2% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SANM | $8.6B | 22.9x | 9.5x | 0.6x | 0.5x | 6.1x | 4.8x | 10.3x | 6.3% |
CLS | $31.9B | 23.6x | 22.2x | 1.7x | 1.5x | 15.3x | 13.5x | 16.8x | 1.7% |
JBL | $26.6B | 26.2x | 14.6x | 0.7x | 0.6x | 8.0x | 6.5x | 12.8x | 5.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FLEX | $28.9B | 28.2x | 15.6x | 0.9x | 0.8x | 9.7x | 8.5x | 14.8x | 3.6% |
PLXS | $5.5B | 27.1x | 19.1x | 1.1x | 0.9x | 10.9x | 9.2x | 17.1x | -0.5% |
BHE | $2.3B | 40.6x | 20.8x | 0.8x | 0.7x | 7.4x | 7.1x | 14.9x | 5.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AMD | $1.0T | 156.2x | 80.7x | 24.3x | 19.7x | 45.7x | 37.0x | 93.6x | 0.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
SANM | Revenue | +74.9% | +30.7% | +19.7% |
| EPS | +103.5% | +39.0% | +18.5% | |
CLS | Revenue | +67.7% | +91.4% | +40.9% |
| EPS | +90.1% | +92.3% | +43.7% | |
JBL | Revenue | +20.3% | +27.7% | +15.5% |
| EPS | +36.0% | +38.5% | +24.7% | |
FLEX | Revenue | +6.8% | +29.5% | +30.6% |
| EPS | +24.2% | +54.8% | +54.1% | |
PLXS | Revenue | +21.6% | +19.8% | +9.0% |
| EPS | +21.0% | +23.8% | +14.4% | |
BHE | Revenue | +16.2% | +8.0% | +5.0% |
| EPS | +30.6% | +13.5% | +10.7% | |
AMD | Revenue | +49.4% | +75.5% | +37.7% |
| EPS | +92.6% | +108.1% | +44.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The contract manufacturer that bought Advanced Micro Devices' server-assembly plants reported on 9 November that its heaviest quarter of rack output was also its richest. Sanmina, a San Jose builder of electronics for industrial, medical, defense, telecom and cloud customers, converted 11.3% of revenue into gross profit in the quarter ended 3 October, against 9.1% a year earlier, while revenue grew 84%.
That is not how assembly work for the AI buildout is supposed to behave. A manufacturing contract books the customer's bought-in processors, memory and power equipment as the vendor's own revenue at thin or no markup, so revenue per rack can multiply while gross profit per rack barely stirs. Memory makes the inflation vivid: conventional DRAM contract prices rose roughly 90-95% in the first quarter of 2026 as makers shifted wafers to high-bandwidth memory for accelerators. Each rack shipped now carries a far larger bill of materials. The mechanism is real; it simply does not describe every company doing the work.
Sanmina bought the build and left the design with AMD
Sanmina paid AMD $2.55bn in cash for ZT Systems' manufacturing arm while the chipmaker kept the design business, so it competes for build volume rather than design content. Those plants contributed $884m of the $3.08bn Integrated Manufacturing Solutions segment last quarter, while the legacy factories in that segment grew 13.8% to $2.2bn. Derived from the reported lines, each incremental revenue dollar carried about 13.9 cents of gross profit, above the company's own 11.3% average, and still above it after stripping a disclosed one-time $30m tariff recovery.
"Non-GAAP operating margin expanded from 5.7% operating margin to 7.4% operating margin year-over-year," chairman and chief executive Jure Sola told investors on 9 November, on fiscal 2026 revenue of $14.53bn. Management then guided fiscal 2027 revenue to $17.5-19.5bn with operating margin of 7.0-7.5%, flat at the midpoint against what it just delivered. The gross line is rising; the line below it is guided sideways.
Celestica designs the racks and keeps less of each new dollar
Celestica, the Toronto company that designs and builds switches, optical interconnect, servers and storage for hyperscalers, grew revenue 82.5% to $5.83bn in its September quarter and saw gross margin fall to 11.0% from 13.0%. The incremental dollar carried 8.5 cents of gross profit, well under the average dollar. Hardware Platform Solutions, the design-led line, reached $2.3bn and grew 70%, slower than the 102% growth of the segment containing it, so design content is shrinking as a share of mix even while it expands.
Management guides 2027 gross margins "in the low 11s" with operating margin of 9.0% reached through operating leverage, which concedes that the new revenue arrives at roughly today's gross margin. Celestica's 10-Q for the quarter discloses three customers at 35%, 17% and 14% of revenue. It cut 2026 free-cash-flow guidance to $460m from $600m, set 2027 capital spending at $1.5-2.0bn, and told investors 2027 would be a net use of cash.
The split has an arithmetic cause. Rack work landing near 11% of revenue dilutes a book that was earning 13% and lifts one that troughed at 7.6% in the December 2025 quarter.
Jabil moved the line below the gross line
Jabil's August quarter held gross margin at 9.4% against 9.5%, while operating margin expanded to 5.7% from 4.1%. It guides fiscal 2027 revenue of $44.5bn with AI-related revenue of $22.1bn, up from $14.4bn, and roughly $18.9bn of the group, about 42%, sitting in automotive, healthcare, energy and devices. "Most of our AI business supports everyday AI usage rather than frontier model training," Matt Crowley, president of its Intelligent Infrastructure segment, said on 30 September. Inventory days ran at 64 against a 55-60 target, the one disclosed figure in the group supporting the pre-bought-material story.
The markdown did not read any of this
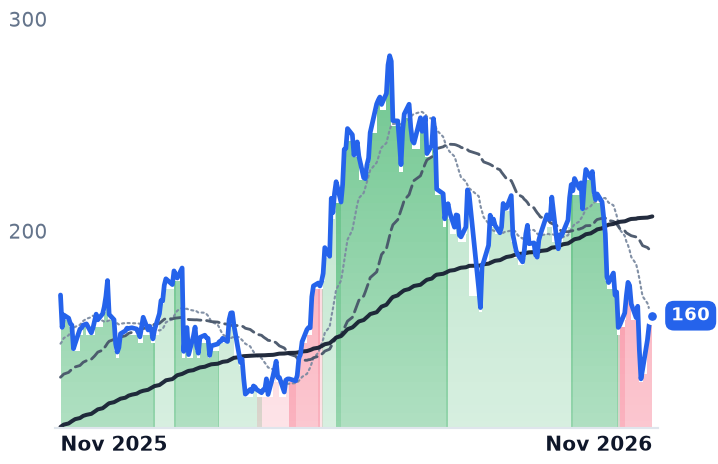
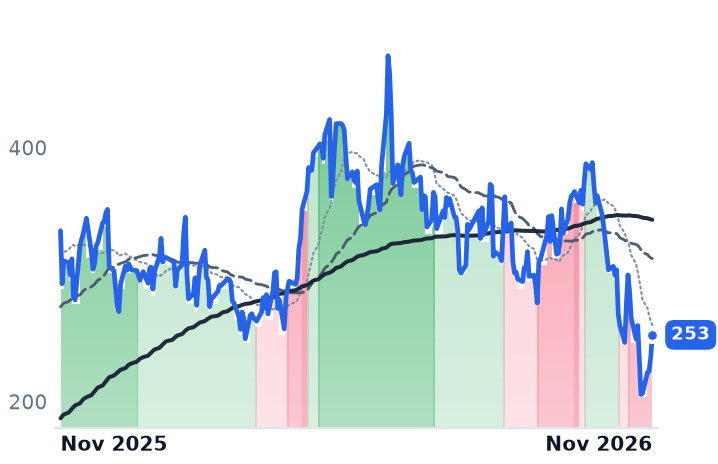
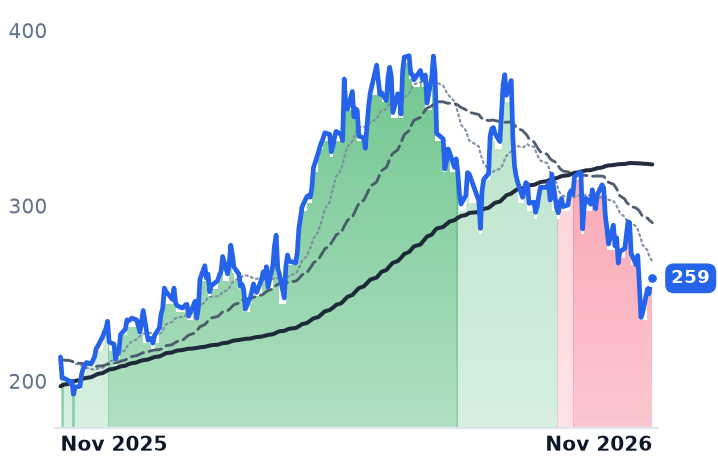
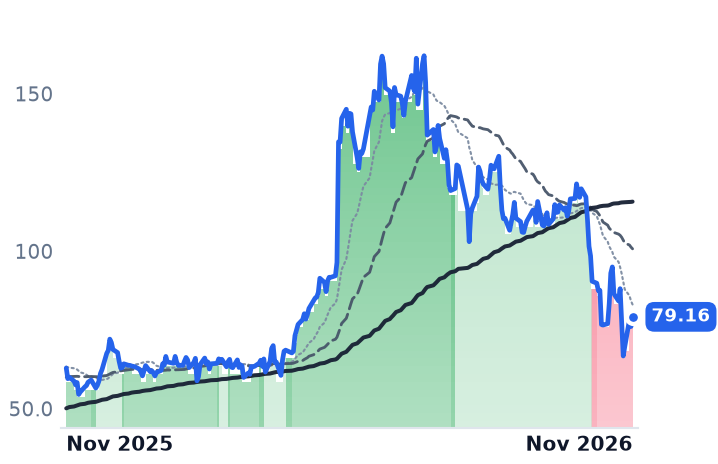
Over the 30 days to 12 November the six-name group fell between 15.5% and 28.1%, and the deepest fall belonged to Flex, whose own 10-Q reported gross margin up 60 basis points to 9.6%. The 5 November session was the biggest technology selloff since the Covid crash, two days after voters backed candidates and measures curbing US data-center construction; Celestica fell 12.66% that day with no company announcement, its most recent update having beaten and raised. All three have rebounded since, Sanmina 22.9% and Celestica 22.8% in five sessions.
So the quarters account for almost none of the move. On the same forward year, Sanmina trades at 9.5 times consensus earnings, Celestica at 11.6 and Jabil at 14.6, and each dollar of Sanmina's trailing gross profit costs $6.15 against $15.25 at Celestica, down from roughly $26 in May. The only disclosed deterioration anywhere in the group is Celestica's gross margin and its cash guidance, and that company is the one the market had re-rated hardest first. Where the business actually improved, the repricing was indiscriminate.
Sanmina's flagship program is barely under way. "We've now begun to ship the Helios product, albeit in small quantities," chief financial officer Jonathan Faust said on 9 November, of the AMD rack platform the whole acquisition was built around. The margin it reported last quarter was earned before that volume arrived.