

Only nVent Has Disclosed Slowing Data-Center Orders; Its Two Grid Peers' Backlogs Grew
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Three US-listed makers of the switchgear, transformers and enclosures a data center cannot be energized without were marked down together after the November midterms, and only one of them had already told investors its order book was cooling. nVent's organic orders grew low double digits in the September quarter, against roughly 40% in the March quarter, and its gross margin fell 161 basis points to 35.8% even as revenue rose 44% organically and it raised full-year adjusted earnings guidance to $5.36-$5.39 a share.
The other two books went the other way: Powell's backlog reached $2.4bn, up 69%, and GE Vernova's Electrification equipment backlog hit $42bn, up 60%. The split has a cause in how long each book is. nVent ships in about five months, so its orders read the present; Powell's book is roughly two years of revenue at prices fixed when each order was signed, which is why its gross margin sat flat at 30.6% through a record order quarter.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
POWL | Powell Industries | Power Distribution Systems | 🔴 Cont. Bear | −20.8% | +20.7% |
GEV | GE Vernova | Power Generation & Propulsion | ⚠️ Emerging Bear | −16.7% | +43.3% |
NVT | nVent Electric | Power Distribution Systems | 🟢 Cont. Bull | −28.9% | +2.2% |
| Compared against · context, not the story | |||||
ETN | Eaton | Power Distribution Systems | 🟢 Cont. Bull | −14.8% | −2.1% |
HUBB | Hubbell Incorporated | Power Distribution Systems | 🔴 Cont. Bear | −5.3% | −1.5% |
AMSC | American Superconductor | Power Distribution Systems | 🔴 Cont. Bear | −13.4% | −29.0% |
ESE | ESCO Technologies | Specialty Systems & Components | ⚠️ Emerging Bear | −7.3% | +8.3% |
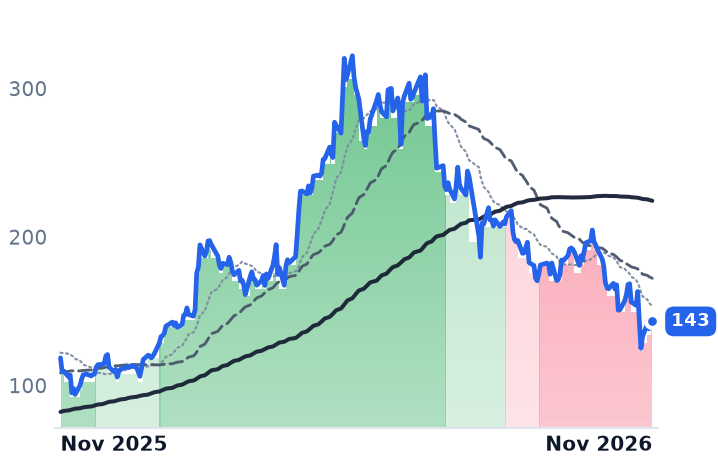
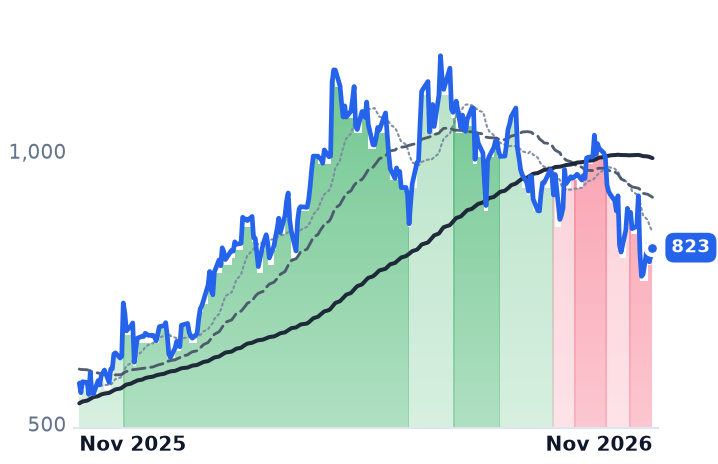
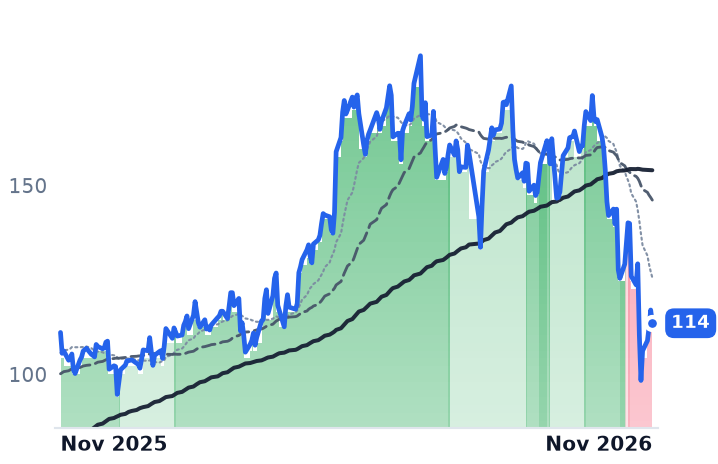
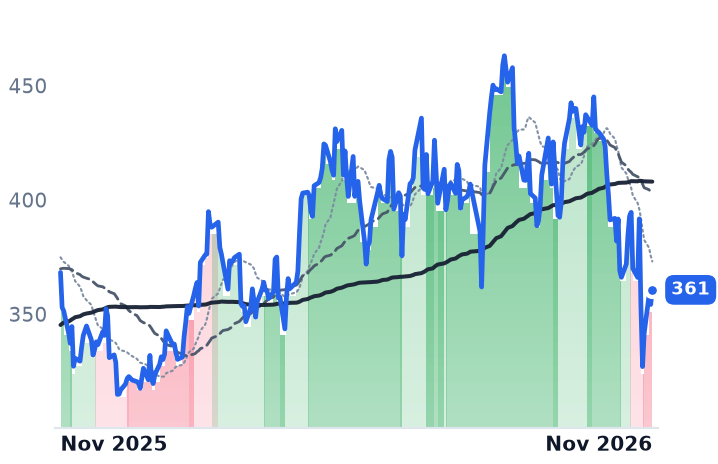
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
POWL | $5.2B | 27.2x | 20.8x | 4.5x | 3.5x | 15.0x | 11.5x | 18.4x | 4.7% |
GEV | $218.7B | 21.5x | 26.1x | 5.0x | 4.7x | 22.9x | 21.4x | 19.8x | 7.8% |
NVT | $18.8B | 27.7x | 21.6x | 3.6x | 3.3x | 9.7x | 8.9x | 17.0x | 3.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ETN | $132.7B | 34.1x | 24.9x | 4.1x | 3.9x | 11.8x | 11.3x | 23.8x | 3.3% |
HUBB | $22.7B | 25.1x | 20.9x | 3.4x | 3.3x | 9.7x | 9.3x | 17.3x | 4.1% |
AMSC | $1.5B | 9.7x | 34.2x | 4.5x | 4.0x | 16.1x | 14.0x | 45.2x | 1.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ESE | $7.1B | 22.6x | 29.8x | 5.5x | 4.6x | 13.1x | 10.9x | 25.7x | 2.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
POWL | Revenue | +8.8% | +25.8% | +14.4% |
| EPS | +12.1% | +27.8% | +19.8% | |
GEV | Revenue | +25.9% | +14.1% | +15.7% |
| EPS | +335.1% | −18.6% | +38.8% | |
NVT | Revenue | +51.0% | +30.6% | +14.3% |
| EPS | +61.3% | +30.2% | +20.4% | |
ETN | Revenue | +22.4% | +11.6% | +10.4% |
| EPS | +13.9% | +18.9% | +16.8% | |
HUBB | Revenue | +18.5% | +11.2% | +6.3% |
| EPS | +13.2% | +11.9% | +11.8% | |
AMSC | Revenue | +36.2% | +24.9% | +14.6% |
| EPS | +470.9% | −74.6% | +46.7% | |
ESE | Revenue | +17.8% | +18.4% | +11.9% |
| EPS | +43.0% | +10.4% | +15.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The companies that make the switchgear, transformers and enclosures an AI data center needs before it can be energized lost between a sixth and a quarter of their value in the two weeks after 3 November. Only one of the three had already told investors its orders were cooling. nVent Electric, which sells electrical enclosures, server-rack infrastructure and heat tracing under the HOFFMAN, SCHROFF and RAYCHEM brands, disclosed in late October that organic orders grew only low double digits in the September quarter, against roughly 40% in the March quarter and about 65% a year earlier.
The markdown treated all three as one bet on AI power demand, after restrictions won 46 of 47 data-center ballot measures on 3 November and SoftBank on 10 November wrote down $3.7bn of data-center projects, including $2.85bn of non-refundable advances already paid to equipment companies. What a single bet obscures is that these three books convert at completely different speeds, and the contested capacity sits in 2028: Nomura's post-midterm read is that 2027 construction schedules are largely locked and that moratoria push back 2028 starts.
The five-month book is the one that moved
nVent's backlog of $2.6bn is about five months of shipments at the September quarter's $1.515bn of revenue, so its orders are a present-tense reading. That quarter was strong by every reported measure: revenue up 44% organically, return on sales of 22.1%, and full-year adjusted earnings guidance raised to $5.36-$5.39 a share from $5.00-$5.10. Underneath it, gross margin fell 161 basis points to 35.8% while operating margin rose 286 basis points, which is scale offsetting price and mix, not pricing power widening. Infrastructure is now 60% of year-to-date sales against 45% in 2025. "We expect the infrastructure vertical to deliver record double-digit organic growth this year with data center expansion, and the need for power," chief executive Beth Wozniak said on 30 October. At 21.6x this year's consensus earnings, against roughly 30x forward in May, the de-rating is doing rational work.
Powell books the price, then waits two years
Powell Industries, a Houston maker of custom switchgear and modular E-House substations, recognizes engineered-to-order work over time at prices fixed when the order was signed. Its backlog reached $2.4bn at 30 June, up 69%, on bookings of $934.2m against $311.7m of revenue. Chairman and chief executive Brett Cope said the quarter "elevated our backlog to over $2 billion for the first time in our 79-year history." Gross margin was 30.57%, versus 30.70% a year earlier. That is the mechanism in one line: a record order book and no incremental margin, because the margin was set at signing. The $2.4bn is roughly 2.1 years of revenue at the trailing rate. Powell trades at 20.8x fiscal 2027 consensus earnings and 27.2x trailing, against the 35x forward and 58x trailing flagged in May.
Vintage, not volume, at GE Vernova
GE Vernova's third-quarter orders rose 96% organically to $29bn and backlog reached $197bn, with Electrification equipment backlog at $42bn, up 60%, and segment margin up 470 basis points to 19.1%. The company attributes the improvement to "favorable price and disciplined underwriting" as older work rolls off. Yet its Electrification orders themselves fell 9% organically to $5.4bn against a prior-year synchronous-condenser comparison, with book-to-bill near 1.4x, and chief executive Scott Strazik told investors on 28 October that gas turbine orders and slot reservations have slowed while the company takes reservations for 2032 delivery. Revenue growth accelerated across the year to 27%; the shares fell 18% in 30 days. On 2027 consensus earnings the multiple is about 31.9x, against the roughly 50x Rajiv Jain called unsustainable in July.
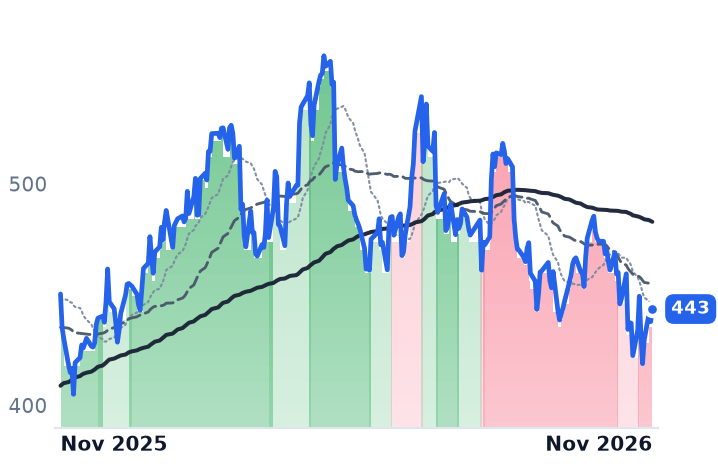
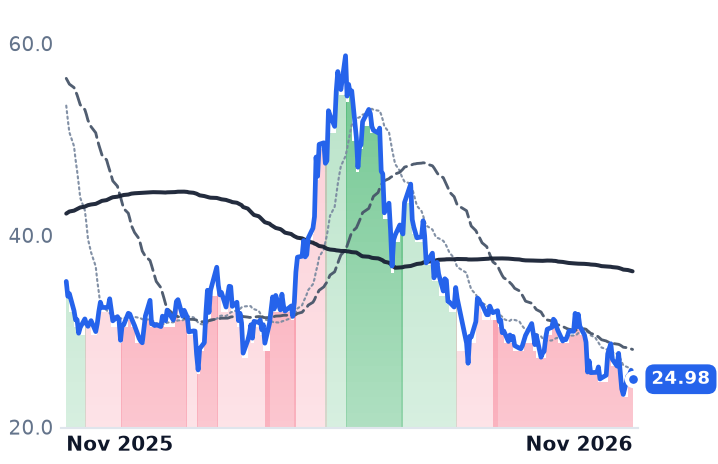
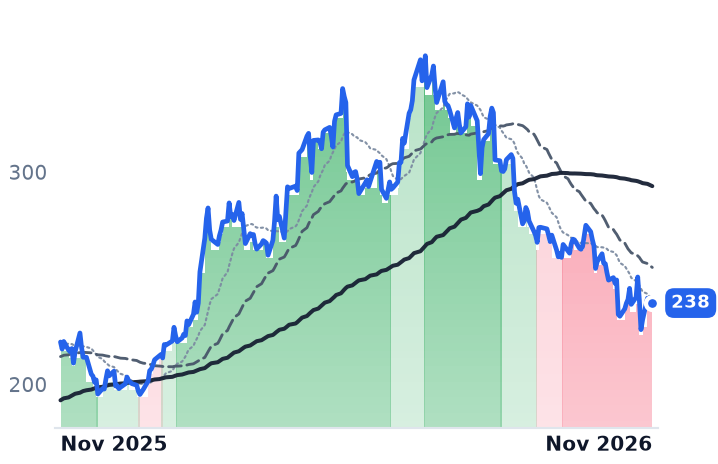
All three peaked on 3 November and gave up most of the decline in the two sessions of 4-5 November. Over twelve months GE Vernova is still up 43% and Powell 21%, while nVent has given back its year at up 1.9%. Eaton fell 14.8% over the same 30 days and Hubbell 5.3%, so the three carried the group's move.
The quarters account for one of the three declines. nVent's own disclosures show the deceleration its risk list anticipated, and its short book means a 2028 slowdown reaches it fast. For Powell and GE Vernova the next several quarters of revenue are already contracted at prices set before any of this, and the physical queue has not loosened: large power transformers still run 30 to 36 months and 38kV switchgear 78 to 104 weeks, with roughly $1.8bn of announced North American transformer capacity not operating until 2028. The exposure the ballot measures created and the cash SoftBank wrote off belong to the same window, the one past the contracted book.
Powell's September-quarter numbers do not exist yet. The company said on 3 November it would report fiscal fourth-quarter results after the close on 16 November, which makes it the first of the three to describe an order book assembled before the vote to a market that has already decided what the vote meant.