

ChipMOS Hit a Four-Year Margin High Testing the Memory That AI Chips Crowded Out
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
The packaging-and-test house with no accelerator content on its shelf turns out to be the clearest reading of the AI cycle on it, and it was marked down alongside the names that do the accelerator work.
ChipMOS, which assembles and tests memory and display-driver chips in Hsinchu, earned a 21.67% gross margin in the September quarter against 12.37% a year earlier, and its October revenue rose 30.9% from a year before. ASE's assembly-and-test arm earned 30.6%, and its October revenue rose 47.1%. Both disclosures were published on 10 November, after the fall.
Only Amkor's book deteriorated: revenue was flat year over year as memory and component shortages starved its phone module business. The same scarcity that lifts ChipMOS's test pricing is what empties Amkor's conventional lines.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
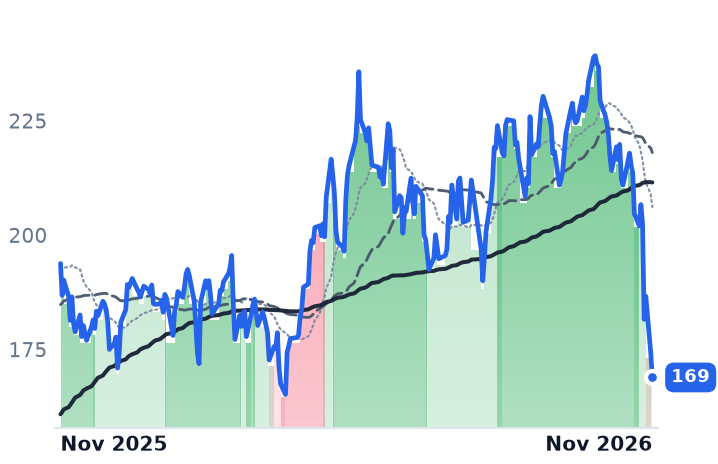
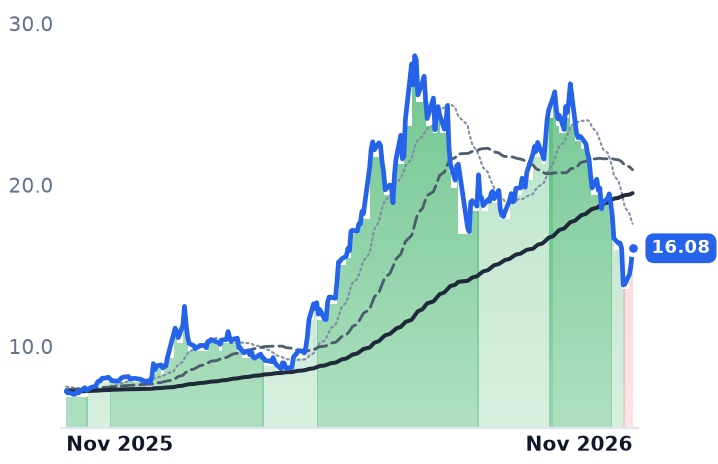
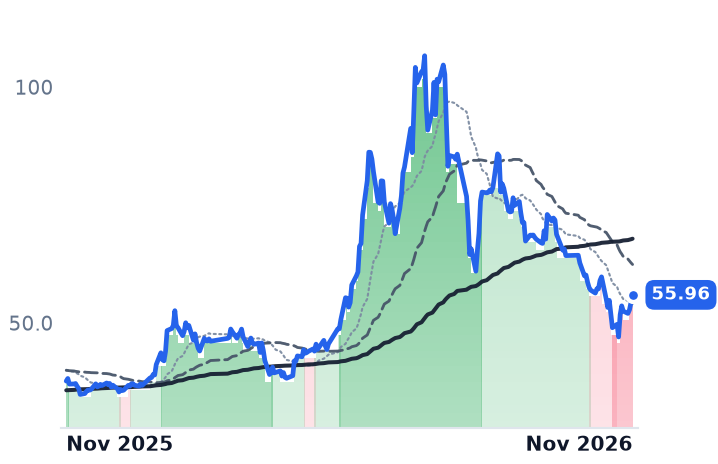
IMOS | ChipMOS TECHNOLOGIES | Test & Assembly Services | 🟢 Cont. Bull | −26.4% | +104.9% |
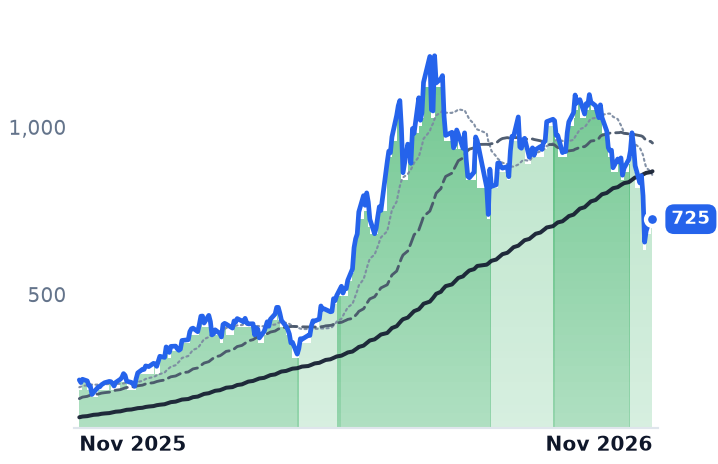
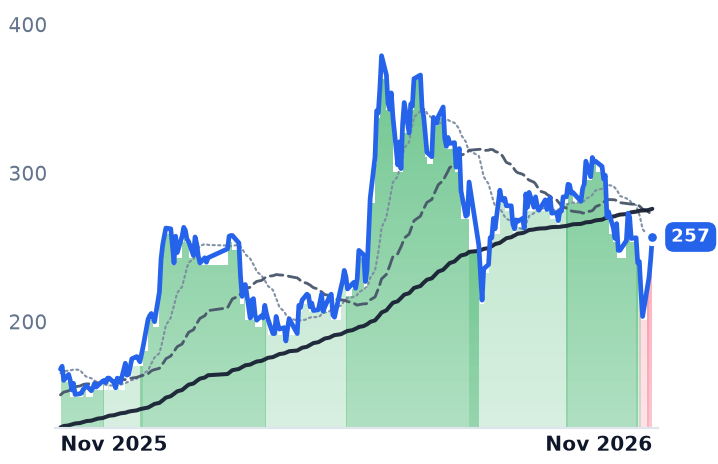
ASX | ASE Technology | Test & Assembly Services | 🟢 Cont. Bull | −18.9% | +152.3% |
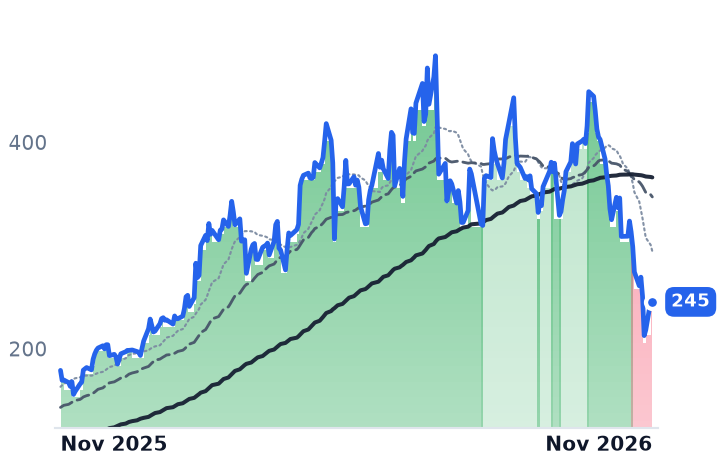
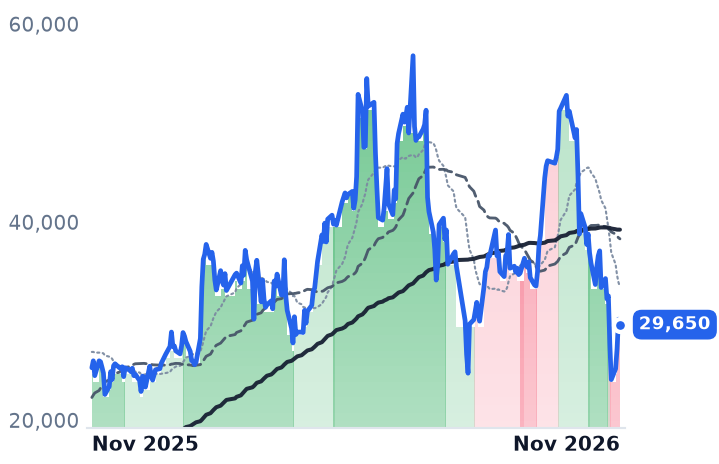
AMKR | Amkor Technology | Test & Assembly Services | 🔴 Cont. Bear | −18.8% | +11.0% |
| Compared against · context, not the story | |||||
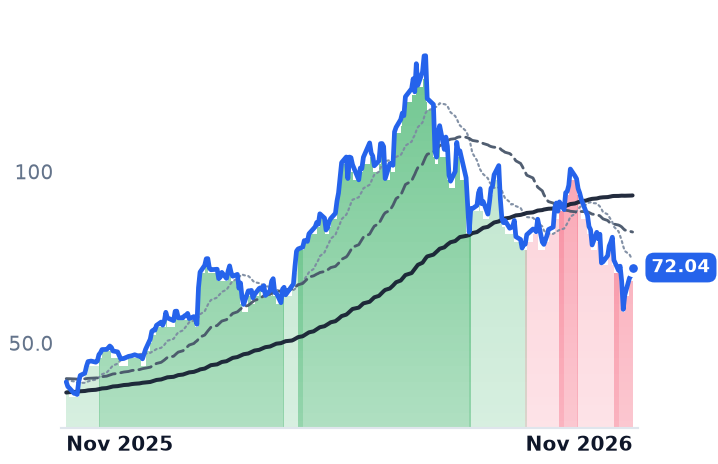
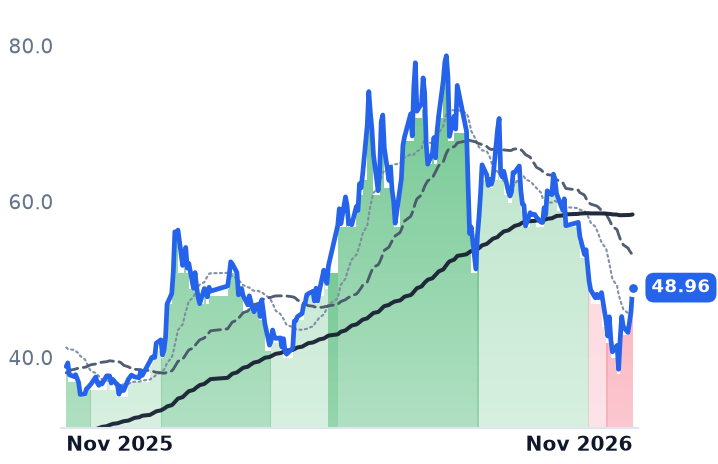
TSM | Taiwan Semiconductor Manufacturing | Foundries | 🟢 Cont. Bull | −6.4% | +43.0% |
NVDA | NVIDIA | Processors & Accelerators | 🟢 Cont. Bull | −22.7% | −10.4% |
MU | Micron Technology | Memory & Storage | 🟢 Cont. Bull | −13.6% | +231.6% |
TER | Teradyne | Test & Assembly Services | 🟢 Cont. Bull | −28.0% | +48.4% |
KLIC | Kulicke and Soffa Industries | Test & Assembly Services | ⚠️ Emerging Bear | −17.5% | +86.1% |
UMC | United Microelectronics | Foundries | 🟢 Cont. Bull | −26.9% | +122.1% |
6239.TW | Powertech Technology | Semiconductors | 🟢 Cont. Bull | −13.2% | +53.0% |
067310.KQ | HANA Micron | Semiconductors | ⚠️ Emerging Bear | −39.9% | +17.2% |
002156.SZ | Tongfu Microelectronics Co.,Ltd | Semiconductors | ⚠️ Emerging Bear | −9.0% | +26.1% |
600584.SS | JCET | Semiconductors | ⚠️ Emerging Bear | −7.0% | +48.5% |
12-month price & trend
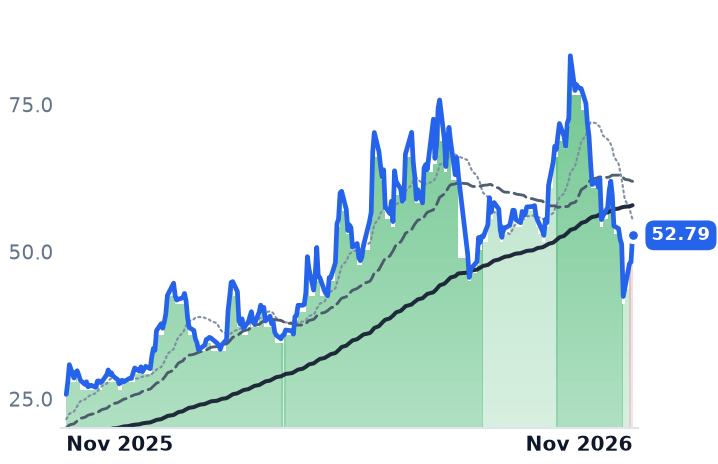
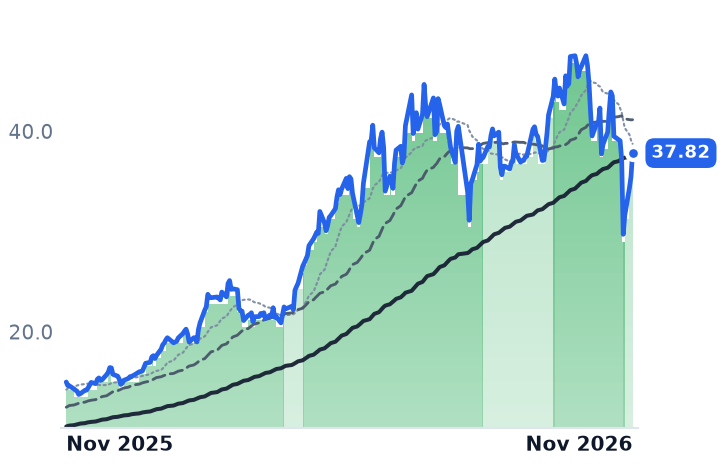
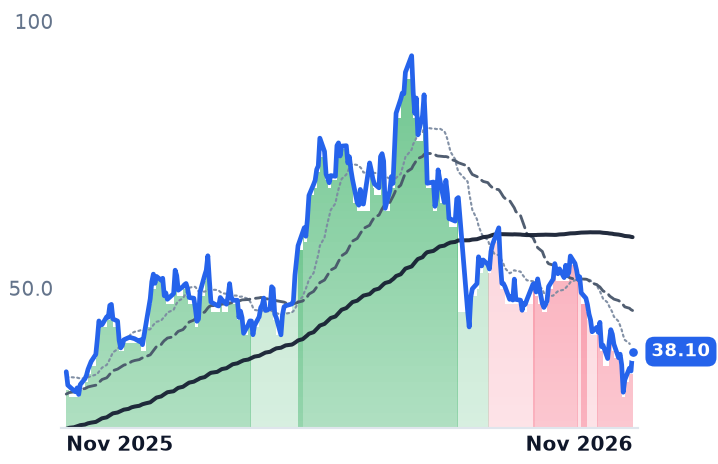
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
IMOS | $1.8B | 18.3x | — | 2.0x | — | 11.6x | — | 8.6x | -0.9% |
ASX | $83.2B | 33.4x | — | 3.3x | — | 15.8x | — | 16.4x | -2.8% |
AMKR | $9.4B | 15.2x | 15.1x | 1.3x | 1.2x | 7.6x | 7.5x | 7.0x | -1.7% |
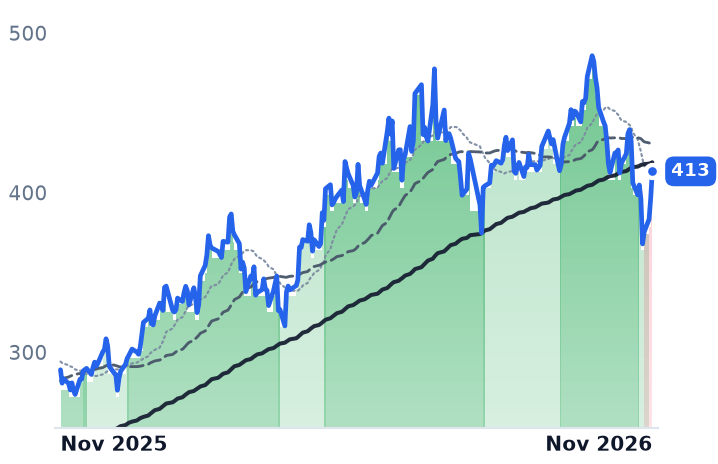
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TSM | $2.1T | 23.8x | — | 12.3x | — | 18.6x | — | 15.8x | 2.5% |
NVDA | $5.5T | 34.3x | 25.0x | 21.5x | 13.9x | 29.0x | 18.7x | 28.3x | 2.2% |
MU | $1.0T | 19.9x | 12.2x | 11.2x | 7.8x | 15.4x | 10.7x | 14.5x | 2.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TER | $33.4B | 24.4x | 22.5x | 6.7x | 6.4x | 11.3x | 10.8x | 18.5x | 3.1% |
KLIC | $5.3B | 46.0x | 29.8x | 5.6x | 4.9x | 11.6x | 10.2x | 31.1x | 0.8% |
UMC | $40.1B | 14.8x | — | 4.8x | — | 15.2x | — | 7.4x | 5.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
6239.TW | $198.4B | 26.6x | 21.1x | 2.3x | 2.1x | 12.3x | 11.2x | 8.8x | -5.5% |
067310.KQ | $2.4T | 22.5x | 15.5x | 1.4x | 1.1x | 8.1x | 6.1x | 9.1x | 2.3% |
002156.SZ | $95.5B | 66.3x | 53.9x | 3.3x | 2.9x | 22.6x | 20.0x | 20.0x | -1.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
600584.SS | $140.8B | 85.6x | 62.3x | 3.6x | 3.2x | 25.7x | 22.7x | 27.3x | -1.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
IMOS | Revenue | +26.1% | +14.8% | +13.7% |
| EPS | +834.7% | +38.4% | +22.1% | |
ASX | Revenue | +30.6% | +29.8% | +19.2% |
| EPS | +130.6% | +62.0% | +31.9% | |
AMKR | Revenue | +13.5% | +13.3% | +11.1% |
| EPS | +100.7% | +9.1% | +16.5% | |
TSM | Revenue | +43.8% | +38.6% | +26.1% |
| EPS | +68.6% | +34.6% | +27.4% | |
NVDA | Revenue | +65.1% | +84.2% | +43.2% |
| EPS | +59.0% | +91.7% | +42.0% | |
MU | Revenue | +248.0% | +92.8% | +11.4% |
| EPS | +804.9% | +111.2% | +7.9% | |
TER | Revenue | +69.7% | +24.6% | +22.3% |
| EPS | +167.0% | +30.0% | +30.9% | |
KLIC | Revenue | +66.9% | +19.5% | +6.4% |
| EPS | +2317.8% | +29.8% | +1.7% | |
UMC | Revenue | +16.3% | +25.2% | +16.3% |
| EPS | +112.4% | −1.4% | +25.1% | |
6239.TW | Revenue | +26.5% | +21.5% | +11.9% |
| EPS | +75.7% | +45.6% | +12.2% | |
067310.KQ | Revenue | +55.3% | +15.1% | +9.0% |
| EPS | +603.4% | +17.7% | +16.6% | |
002156.SZ | Revenue | +18.7% | +14.4% | +12.2% |
| EPS | +39.9% | +5.3% | +22.6% | |
600584.SS | Revenue | +10.4% | +14.7% | +12.8% |
| EPS | +44.7% | +34.6% | +26.7% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Two of the three listed subcontractors that package and test other companies' chips published October revenue on 10 November, and both numbers accelerated. ChipMOS, the Hsinchu house that assembles and tests memory chips and the driver chips behind LCD and OLED panels, reported NT$2,850.6m for the month, up 30.9% from a year earlier, and said it continues to add capacity against customer forecasts and long-term supply agreements.
The shelf these names sit on was assembled as a spillover bet: contract packaging at TSMC is the bottleneck in accelerator output, so the merchant subcontractors that take its overflow were the cheap way to own the shortage. November tested that belief crudely, knocking 20% to 30% off all three inside a month. What the September-quarter and October disclosures show is that the member with no accelerator packaging whatsoever posted the widest margin gain of the three.
The AI content ChipMOS never packages
ChipMOS's September-quarter revenue was TWD 8.4008bn, up 36.7% year over year, with gross margin of 21.67% against 12.37% a year earlier — 930 basis points, the largest expansion on the shelf. Operating margin went to 19.73% from 6.02%, and net income more than tripled. Digitimes reported earnings of NT$1.89 a share, the company's highest quarterly profit since 2022.
That is a loading-and-pricing story, and the company said so in its own words, attributing record quarterly revenue to "sustained AI-related demand outpacing available memory supply." The likelier reading is that memory capacity pulled toward high-bandwidth parts tightens conventional DRAM and NAND, which fills back-end test floors and firms per-unit prices. The base was low: annual gross margin had fallen from 26.47% in 2021 to 10.83% in 2025. There is also headroom — the June quarter put overall utilisation at 78%, memory at 65%, with memory 51% of revenue, and no comparable September figure has been filed. ChipMOS trades at 18.3x trailing earnings and 2.25x book; its forward consensus rests on a single analyst and is indicative at best.
ASE's margin ceiling became its floor
ASE Technology, the largest merchant packager outside TSMC, earned a 30.6% gross margin in its assembly, test and materials arm last quarter, which threw off 91% of group operating profit on 62% of consolidated revenue. Group revenue rose 44.8% year over year. October revenue was NT$88.62bn, up 47.1%, with the packaging arm up 57.7%.
"The so-called structural margin ceiling has now become the base for us," chief financial officer Joseph Tung told investors on 29 October, guiding sequential improvement from a 30% base through next year. Management raised 2026 leading-edge advanced packaging revenue guidance mid-call to over $4bn from $3.7bn, and says utilisation is at or near 100% with space, not demand, binding. Investor relations head Kenneth Hsiang put the dependency precisely: "The capacities we are putting in place are not specifically made for AI. AI products just so happen to need the performance benefits LEAP interconnections provide." The cost is visible: capex raised to $11.5bn, net debt at 66% of equity, trailing free cash flow negative at -2.8% of market value. The shares have de-rated from about 42x trailing earnings in August to 33.4x, roughly 28x on 2026 consensus.
The one book that actually got worse
Amkor is the exception, and its problem is the same scarcity from the other side. September-quarter revenue of $1.9906bn was up 0.18% year over year, after +25.6% in June, because communications revenue fell 8% sequentially on memory constraints, component shortages and the move of system-in-package work to Vietnam. Computing rose 25% sequentially to a record on high-density fan-out processor programs. Gross profit still rose 27.8% and margin widened 394 basis points to 18.26%; December-quarter guidance is $1.9-2.0bn of sales at 18.0-19.0% gross margin, on roughly $2.5bn of 2026 capex.
Amkor's spending runs years ahead of its revenue: a $12bn Arizona campus whose first phase completes at the end of 2027, funded partly by about $3bn of advance payments from a dozen customers. "Customers are not only planning further ahead, but are also making long-term commitments and providing advance payments tied to future capacity requirements," chief executive Kevin Engel said on 26 October. Concentration remains the risk the build is meant to outgrow: the top ten customers were 66% of quarterly sales, down from 73%. At 15.1x forward earnings against 22.3x in early August, it is the cheapest of the three on that measure while consensus has 2026 earnings doubling.
One session down, four back
Almost the entire monthly markdown happened on 5 November, when data-center siting politics hit the chip complex and the Philadelphia Semiconductor Index fell 12.2%: ASE dropped 20.1% that day, Amkor 14.5%, ChipMOS 17.3%, against TSMC's 7.0%. By 11 November, after CoreWeave's results revived the trade, all three had recovered roughly a quarter off that close. Teradyne fell 30.8% over the same thirty days and Micron 18.0%, so the selling was not a judgment on packaging in particular.
The disclosed meters account for none of the decline and much of the rebound. Two of the three accelerated into October with margins at or near records, and the third is cheaper than at any point recorded this year while its gross profit grows. Where the shelf splits, the cause is mix: ASE and ChipMOS are paid per unit on floors running flat out, one on interposers and the other on memory test, while roughly half of Amkor's book is conventional phone packaging that cannot ship modules it has no memory to fill. TSMC, meanwhile, has widened its outsourcing of the chip-on-wafer step to ASE and Amkor, which argues the merchants are gaining that work rather than losing it to in-house lines.
The cycle's clearest beneficiary on this shelf has never packaged an accelerator and does not plan to. It tests the ordinary memory that everything else needs, and there is less of that than the world wants.