

The AI Data Center Pays Cognex, Ambarella and Ceva Nothing and Bills Them for Memory
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
A fight over where to put American data centers knocked down three companies that sell into factories, warehouses, cars and cameras. Between 3 and 5 November, Cognex fell 18.3%, Ceva 16.0% and Ambarella 11.0% as Democratic midterm gains and a call for a national data-center moratorium hit the whole chip complex.
The quarters they had just reported argue three different things. Cognex posted record revenue of $313.4m, lifted gross margin to 70.8% from 67.6% and raised full-year guidance; its trailing price-to-earnings has halved to 36.2x from 78.7x in May because the earnings arrived, not because the price fell. Ambarella's revenue growth has decelerated five straight quarters and the October quarter is guided to about 10%. Ceva's gross profit shrank.
The one thing the buildout sends all three is a cost: memory.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
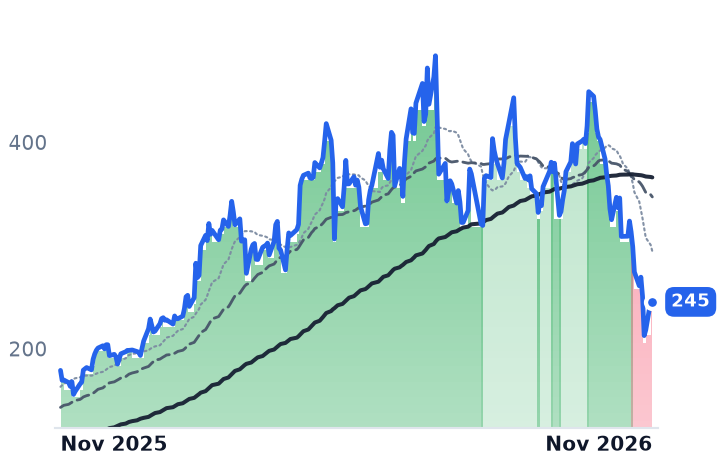
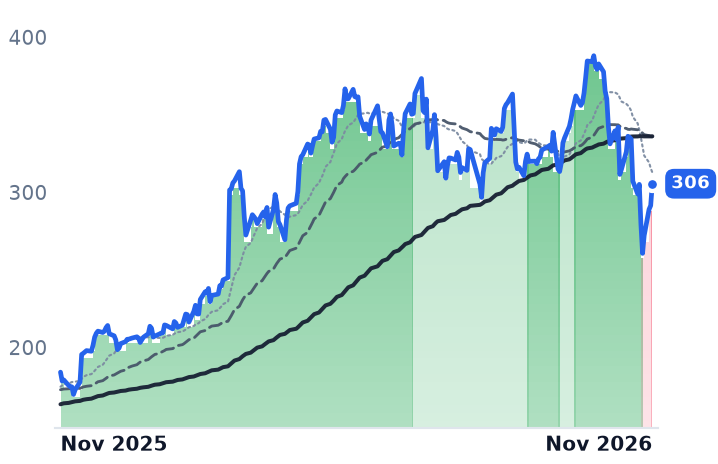
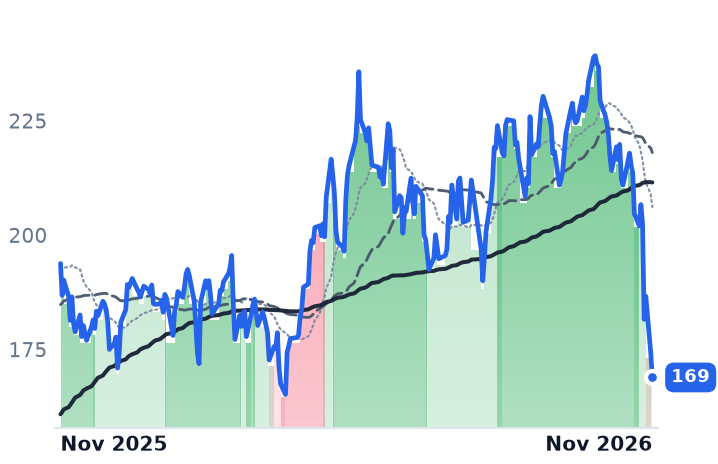
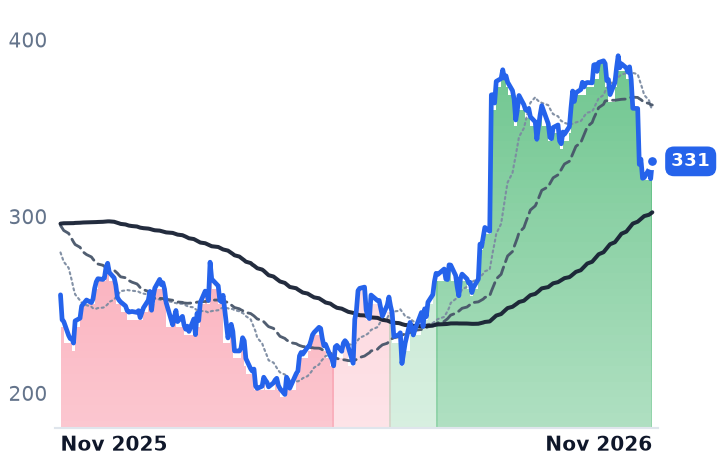
CGNX | Cognex | Test & Measurement | ⚠️ Emerging Bear | −11.5% | +39.4% |
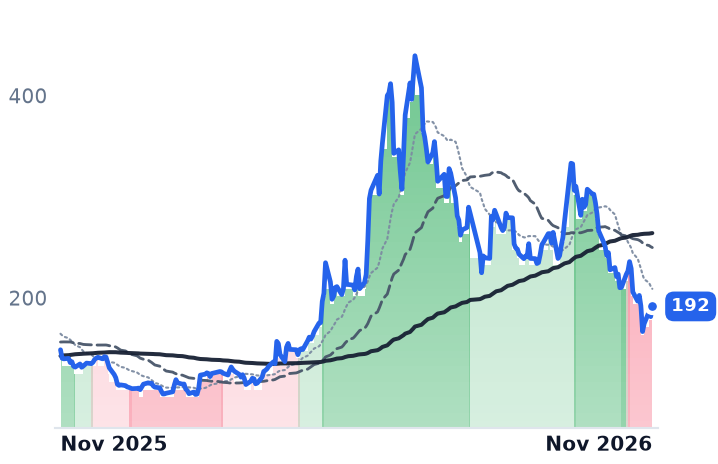
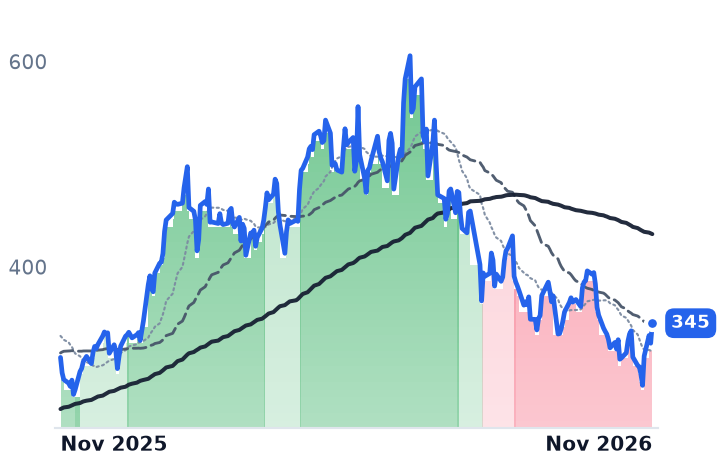
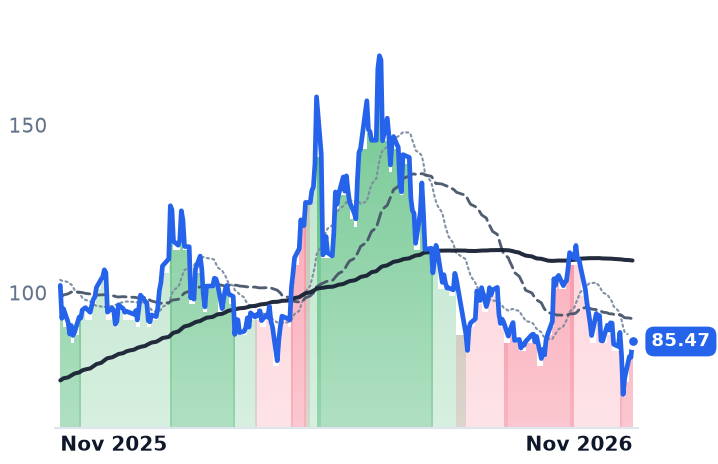
AMBA | Ambarella | Sensors & Specialized Semiconductors | 🔴 Cont. Bear | −3.0% | −34.8% |
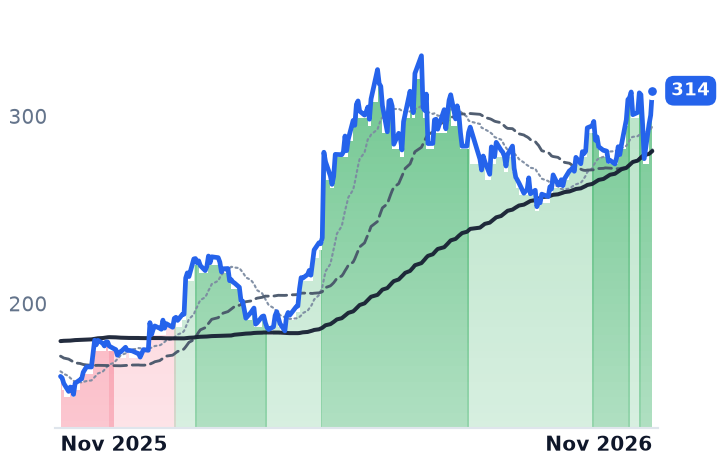
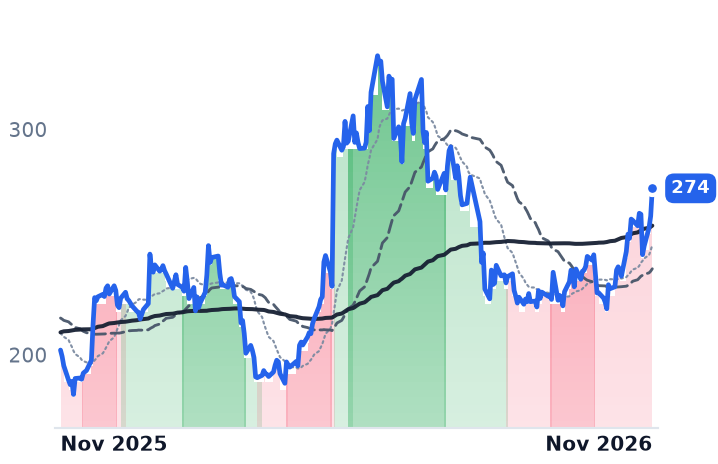
CEVA | CEVA | Sensors & Specialized Semiconductors | 🔴 Cont. Bear | −17.3% | −5.3% |
| Compared against · context, not the story | |||||
MU | Micron Technology | Memory & Storage | 🟢 Cont. Bull | −22.8% | +196.3% |
TER | Teradyne | Test & Assembly Services | 🟢 Cont. Bull | −33.5% | +37.0% |
ARM | Arm Holdings plc American Depositary Shares | Processors & Accelerators | 🟢 Cont. Bull | −23.6% | +28.8% |
ONTO | Onto Innovation | Fabrication Equipment & Materials | 🟢 Cont. Bull | −20.6% | +56.1% |
MCHP | Microchip Technology Incorporated | Processors & Accelerators | 🔴 Cont. Bear | −17.1% | +10.1% |
KEYS | Keysight Technologies | Test & Measurement | 🟢 Cont. Bull | −16.3% | +66.0% |
ROK | Rockwell Automation | Industrial Automation & Motion Control | ⚠️ Emerging Bear | −3.7% | +5.5% |
ADI | Analog Devices | Analog & Power Management | 🟢 Cont. Bull | −0.7% | +68.3% |
AVGO | Broadcom | Data Center & Networking | ⚠️ Emerging Bear | −7.1% | −6.2% |
NVDA | NVIDIA | Processors & Accelerators | 🟢 Cont. Bull | −24.9% | −12.9% |
NVMI | Nova | Fabrication Equipment & Materials | 🔴 Cont. Bear | +2.3% | +10.7% |
TXN | Texas Instruments Incorporated | Analog & Power Management | 🟢 Cont. Bull | +11.3% | +94.5% |
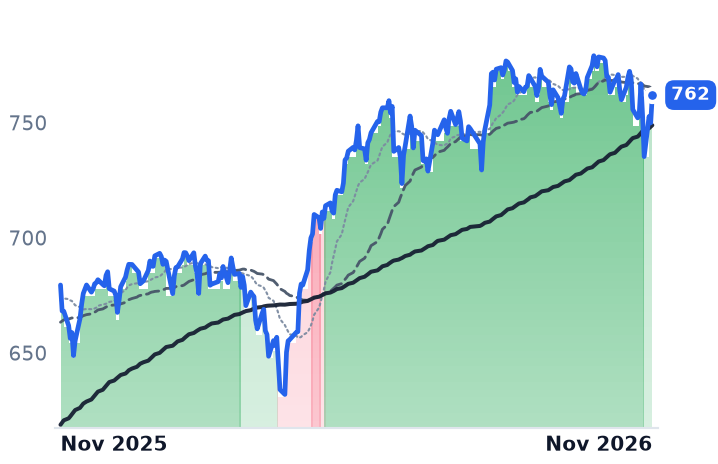
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −1.9% | +12.1% |
ZBRA | Zebra Technologies | Specialized Wireless & IoT | 🟢 Cont. Bull | −14.3% | +29.5% |
RMBS | Rambus | Memory & Storage | 🔴 Cont. Bear | −11.9% | −16.4% |
NXPI | NXP Semiconductors | Processors & Accelerators | 🔴 Cont. Bear | +22.6% | +35.5% |
QCOM | QUALCOMM Incorporated | Processors & Accelerators | ⚠️ Emerging Bear | +0.9% | +1.9% |
MBLY | Mobileye Global | Autonomous Driving & Electronics | 🔴 Cont. Bear | −19.6% | −54.9% |
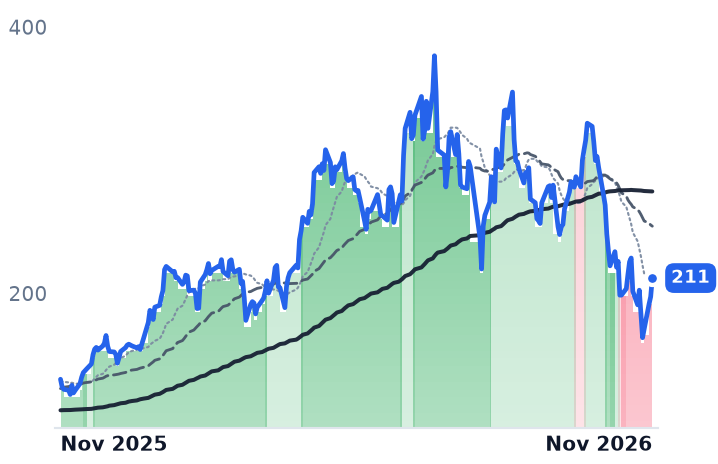
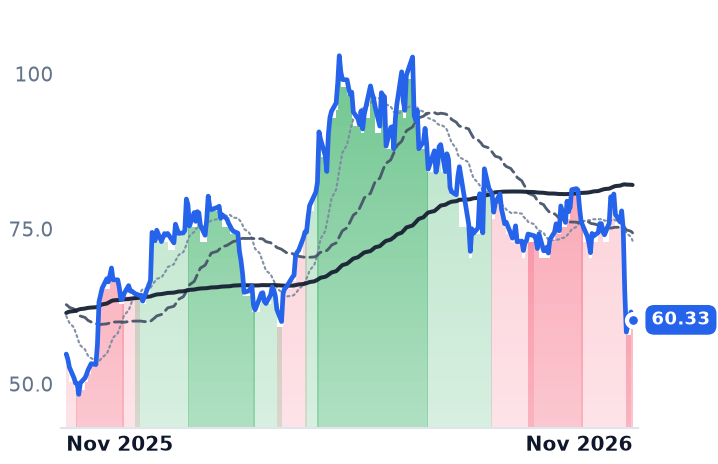
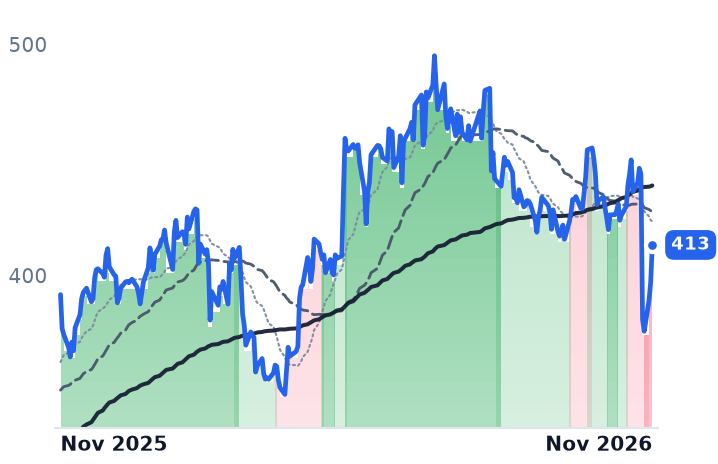
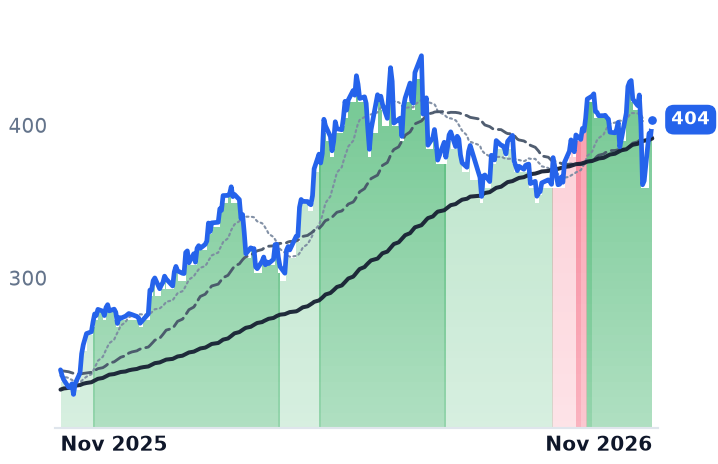
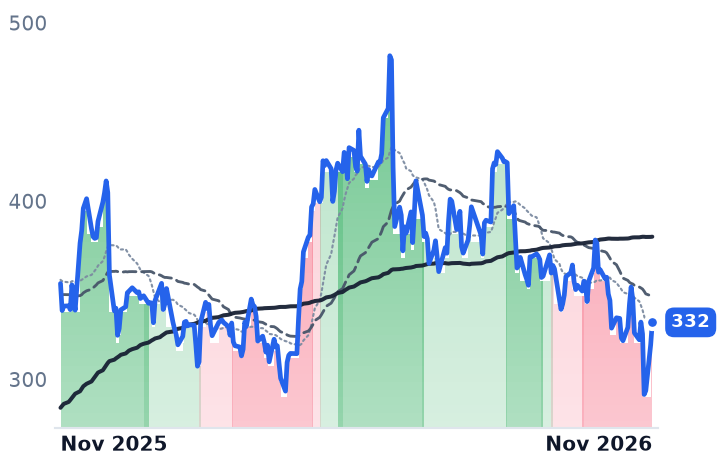
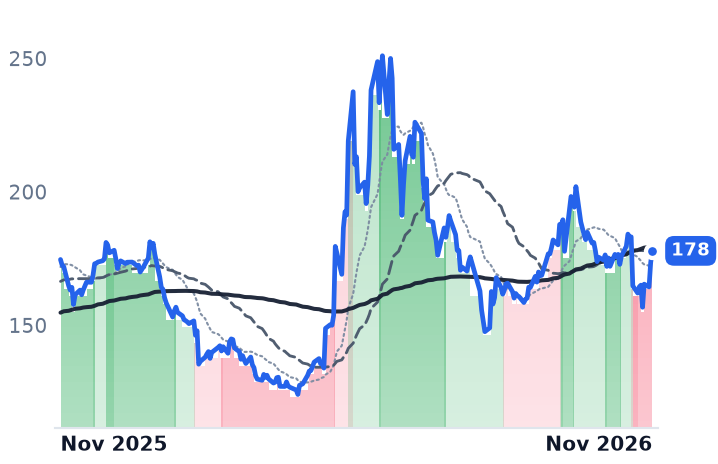
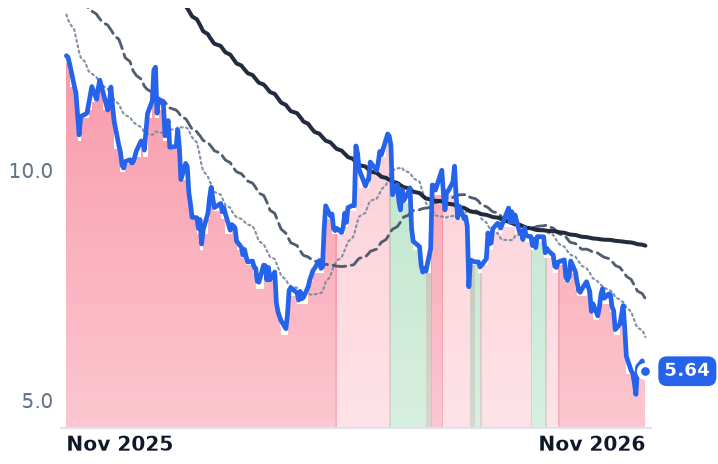
12-month price & trend
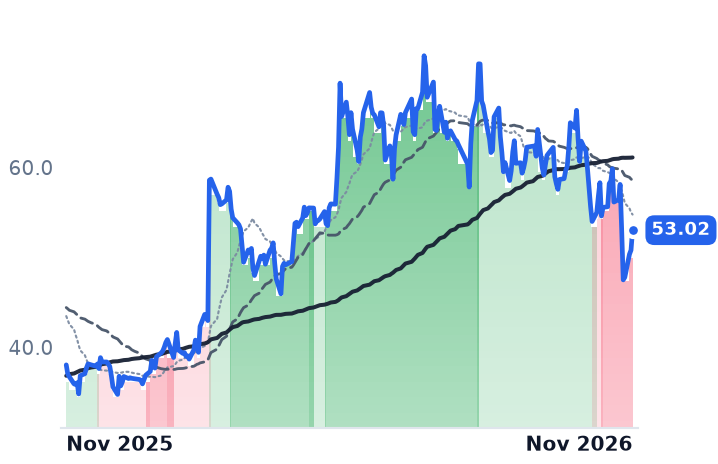
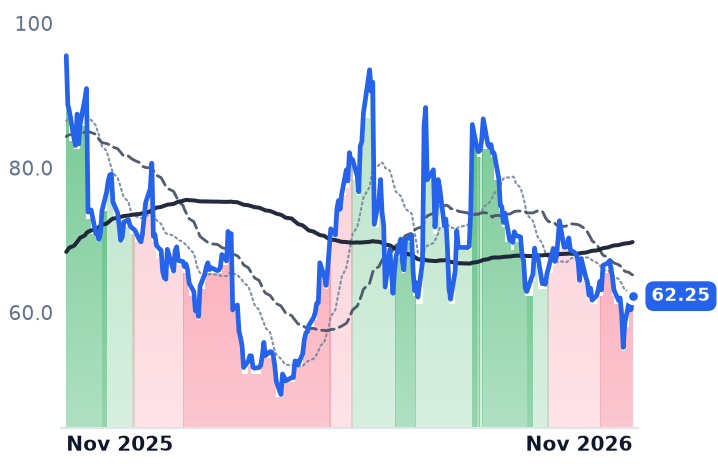
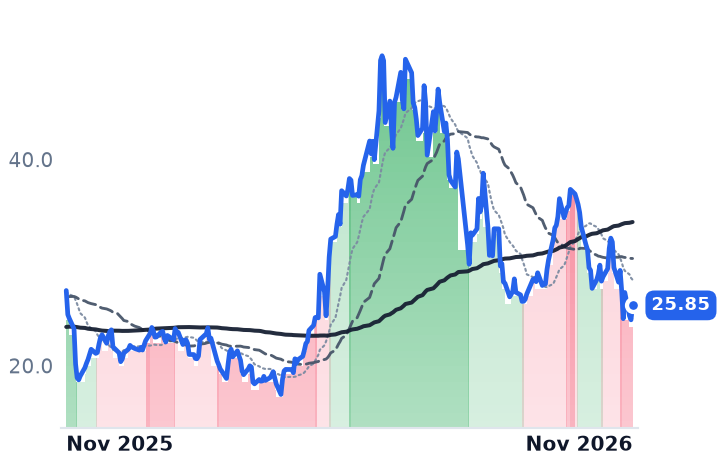
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CGNX | $8.8B | 36.2x | 30.6x | 7.8x | 7.6x | 11.2x | 10.9x | 26.1x | 3.3% |
AMBA | $2.8B | n/m | 77.9x | 6.6x | 6.3x | 11.3x | 10.8x | n/m | 0.3% |
CEVA | $746.4M | n/m | 50.4x | 6.4x | 6.1x | 7.4x | 7.1x | n/m | 0.8% |
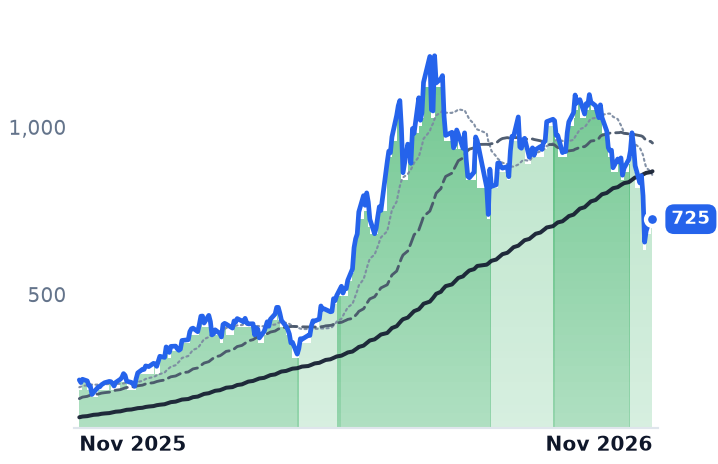
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MU | $1.0T | 19.9x | 12.2x | 11.2x | 7.8x | 15.4x | 10.7x | 14.5x | 2.6% |
TER | $33.4B | 24.4x | 22.5x | 6.7x | 6.4x | 11.3x | 10.8x | 18.5x | 3.1% |
ARM | $186.5B | 200.7x | 78.7x | 34.1x | 30.6x | 35.8x | 32.0x | 141.6x | 0.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ONTO | $8.5B | 64.7x | 21.4x | 7.6x | 5.9x | 15.1x | 11.7x | 35.1x | 3.0% |
MCHP | $31.7B | 43.7x | 16.0x | 5.7x | 4.9x | 9.0x | 7.9x | 18.0x | 4.6% |
KEYS | $46.3B | 37.4x | 19.7x | 7.0x | 5.7x | 10.9x | 8.8x | 25.0x | 3.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ROK | $41.6B | 29.8x | 25.1x | 4.6x | 4.3x | 9.2x | 8.7x | 21.0x | 4.1% |
ADI | $176.2B | 42.9x | 21.6x | 12.7x | 9.5x | 19.3x | 14.4x | 26.1x | 2.8% |
AVGO | $1.6T | 40.8x | 28.2x | 17.6x | 14.8x | 25.6x | 21.6x | 30.7x | 2.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NVDA | $5.5T | 34.3x | 25.0x | 21.5x | 13.9x | 29.0x | 18.7x | 28.3x | 2.2% |
NVMI | $10.1B | 36.1x | 29.8x | 10.6x | 9.4x | 18.6x | 16.4x | 32.2x | 2.0% |
TXN | $286.5B | 40.6x | 34.7x | 13.8x | 12.8x | 22.9x | 21.3x | 27.0x | 2.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPY | $773.0B | — | — | — | — | — | — | — | — |
ZBRA | $15.2B | 26.5x | 15.2x | 2.5x | 2.4x | 5.1x | 5.0x | 15.9x | 6.5% |
RMBS | $8.0B | 30.3x | 23.9x | 10.0x | 9.5x | 12.7x | 12.1x | 21.8x | 3.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NXPI | $62.6B | 19.4x | 16.3x | 4.5x | 4.4x | 8.1x | 7.8x | 13.4x | 5.8% |
QCOM | $185.7B | 13.6x | 17.5x | 4.3x | 4.1x | 8.1x | 7.7x | 16.8x | 4.7% |
MBLY | $7.0B | n/m | 17.4x | 3.5x | 3.5x | 7.3x | 7.4x | n/m | 5.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CGNX | Revenue | +17.5% | +11.4% | +9.7% |
| EPS | +76.7% | +16.4% | +14.4% | |
AMBA | Revenue | +39.8% | +12.9% | +11.6% |
| EPS | −310.6% | +34.9% | +31.8% | |
CEVA | Revenue | +11.1% | +13.8% | +13.6% |
| EPS | +26.5% | +42.7% | +41.0% | |
MU | Revenue | +248.0% | +92.8% | +11.4% |
| EPS | +804.9% | +111.2% | +7.9% | |
TER | Revenue | +69.7% | +24.6% | +22.3% |
| EPS | +167.0% | +30.0% | +30.9% | |
ARM | Revenue | +22.5% | +24.5% | +36.8% |
| EPS | +7.9% | +26.6% | +35.9% | |
ONTO | Revenue | +2.2% | +43.1% | +30.8% |
| EPS | −5.1% | +63.3% | +44.9% | |
MCHP | Revenue | +6.2% | +37.3% | +16.6% |
| EPS | +20.7% | +132.9% | +25.7% | |
KEYS | Revenue | +33.3% | +14.7% | +8.3% |
| EPS | +61.9% | +20.2% | +11.8% | |
ROK | Revenue | +10.2% | +5.8% | +6.2% |
| EPS | +31.8% | +12.5% | +11.4% | |
ADI | Revenue | +38.1% | +22.9% | +12.0% |
| EPS | +65.9% | +30.6% | +18.5% | |
AVGO | Revenue | +67.2% | +64.4% | +61.7% |
| EPS | +73.0% | +65.2% | +58.8% | |
NVDA | Revenue | +65.1% | +84.2% | +43.2% |
| EPS | +59.0% | +91.7% | +42.0% | |
NVMI | Revenue | +22.6% | +26.2% | +17.4% |
| EPS | +23.1% | +28.0% | +21.4% | |
TXN | Revenue | +26.4% | +17.7% | +11.3% |
| EPS | +65.2% | +28.4% | +16.3% | |
ZBRA | Revenue | +16.5% | +6.6% | +4.6% |
| EPS | +34.1% | +5.7% | +8.3% | |
RMBS | Revenue | +18.8% | +20.9% | +25.4% |
| EPS | +24.8% | +24.6% | +25.8% | |
NXPI | Revenue | +17.0% | +12.3% | +9.3% |
| EPS | +29.2% | +20.5% | +17.3% | |
QCOM | Revenue | −1.6% | +5.0% | +15.9% |
| EPS | −11.6% | −5.9% | +26.7% | |
MBLY | Revenue | +6.3% | +9.5% | +22.5% |
| EPS | +37.4% | +2.4% | +39.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Cognex sells machine-vision systems — cameras, barcode readers and the software that interprets what they see — out of factory and warehouse capital budgets, and in the September quarter it sold a record $313.4m of them. Then American voters turned against data centers, and its shares fell 18.3% in two sessions.
Cognex, Ambarella and Ceva are traded as the listed way to own artificial intelligence running at the edge of the network rather than inside a server hall, and the belief inside that grouping is that edge inference is a derivative of the data-center buildout. Their own September-quarter disclosures describe a different relationship. Not one of the three books revenue from a data center being built. All three now pay for one.
A vote about power bills, priced as a chip story
The trigger was explicit. Chip and data-center stocks fell for a second day on 5 November as investors weighed whether Democratic midterm gains would slow construction, CNBC reported, after voters rebuffed data centers in every ballot measure except one and Senator Bernie Sanders and Representative Alexandria Ocasio-Cortez demanded a national construction moratorium. The Philadelphia Semiconductor Index fell about 9.75% that day, its steepest since March 2020, with over $2trn of value gone in the first hour. The S&P 500 tracking fund closed the two sessions down 0.15%. This was the chip complex, not the market.
Cognex's multiple halved while its price did not
Nothing in Cognex's quarter belongs in that selloff. Revenue grew 13.2% as reported and 19% excluding a prior-year one-time benefit from a medical lab automation partnership, the company said, with no meaningful currency effect. Operating margin reached 32.2% against 20.9%, free cash flow rose 21% to $104m, and full-year guidance went up to $1.14bn-$1.16bn with adjusted earnings of $1.68-$1.72 a share. "Q3 was a strong quarter for Cognex, with record revenue, a significant increase in profitability," chief executive Matt Moschner told investors on 5 November. Four of five end markets grew double digits; logistics did so for an eleventh straight quarter; automotive was flat on European weakness, with Europe down 15% while the Americas rose 42%.
Cognex's trailing price-to-earnings has fallen to 36.2x from 78.7x in early May, and its market value is roughly where it was, $8.77bn against $8.94bn. The entire de-rating came from earnings arriving, not from the price falling. Forward earnings of 30.6x rest on consensus of $1.70 a share for this year. Needham cut its target to $70 from $80, Stephens to $70 from $85 and HSBC moved to hold at $65, reading the print as positioning pressure around a quarter that met rather than beat.
Ceva is the only one that shows its invoice
Ceva licenses signal-processing and Bluetooth, Wi-Fi and cellular designs to chipmakers and collects a royalty when their parts ship, months later. Licensees shipped a record 623m devices last quarter for $12.7m of royalties, against 579m and $12.4m a year earlier — about 2.04 cents a unit now versus 2.14 cents then, on the two companies' figures. The mix explains it: Bluetooth shipments rose 9% to 329m while Wi-Fi volume fell 6%.
Revenue grew 2.4% and gross profit fell 0.7%, with margin down to 85.4% from 88.0% on smartphone, personal-computer and television memory pricing. Chief financial officer Yaniv Arieli guided to the opposite on 9 November: "We expect a fourth quarter strong fourth quarter with approximately 24% sequential revenue growth at the midpoint of our guidance. This would represent the highest quarterly revenues in CEVA's history." At 7.4x trailing gross profit it is the cheapest of the three; its trailing earnings multiple is negative and carries no information. Its artificial-intelligence cores, now licensed to more than 50 customers, do not pay a royalty until late this year at the earliest.
Ambarella reports no units at all
Ambarella's computer-vision chips go into driver-assistance systems, security cameras and robots, and edge AI was about 80% of last fiscal year's revenue. It discloses no quarterly shipments or average prices, only an installed base above 46m units and cumulative edge-AI revenue above $1bn. "Our edge AI revenue reached record levels in Q2," chief executive Fermi Wang said on 3 September. Growth has nonetheless slowed for five consecutive quarters, from 31.2% to 13.2%, and the quarter it reports on 24 November is guided to $115m-$124m, about 10.2% growth at the midpoint. The constraint is the same memory that Cognex offsets with price and Ceva absorbs in margin: device makers are receiving half to two-thirds of the memory volumes they order. Operating loss narrowed 63% to $8.1m on a flat 57.7% gross margin, but forward price-to-sales has barely moved, 6.27x against roughly 6.8x in July, because estimates fell with the price.
What the three quarters do and do not explain
Two of the three markdowns are doing rational work. Ambarella is guiding growth down into a loss-making cost base with no disclosed unit meter, and Ceva has just printed its first decline in gross profit. Cognex is the exception, and the reason is its own meter: it is paid by factory, semiconductor and warehouse capital spending, which has nothing to do with whether a data center gets permitted. The case against it is internal, not political — chief financial officer Dennis Fehr guided roughly 93% flow-through of incremental revenue to adjusted earnings this year against 60% indicated for next, logistics faces its hardest comparisons after eleven quarters, and rival Keyence has been growing faster in North America.
By 11 November the instrument and analog names had repaired the damage, Onto Innovation up 4.5% from 3 November and Nevamex up 14.0%, and Ambarella was back where it started. Cognex was still 8.8% lower and Ceva 11.6% lower. Over twelve months Cognex remains up 38.1%.
A moratorium on data-center construction would not remove a dollar of revenue from any of these three. It would, in time, loosen the memory market that is currently rationing Ambarella's customers and compressing Ceva's margin. The companies sold hardest on the buildout's political risk are the ones its reversal would pay.