

The Stopgap Pentagon Budget Is Paying Incumbents' Old Programs and Freezing New Awards
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Federal technology contractors have started showing money arriving again — and almost all of it is landing on contracts they already hold. Leidos took funded backlog, the portion Congress has actually appropriated cash for, up 22% to $11.1bn in the September quarter while the total backlog it sits inside grew 4%; CACI posted its seventh double-digit quarter of funded-backlog growth in eight.
None of this is new appropriations. Agencies have run since 1 October on a stopgap holding the Pentagon near $838.5bn against a $1.5 trillion fiscal 2027 request, and CACI's own management called the award pace sluggish.
The market has split the group anyway. SAIC, whose order book ran 0.8x over the trailing year, re-rated from roughly 11.6x trailing earnings to 17.3x; Leidos, raising guidance three quarters running, de-rated to 11.6x.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
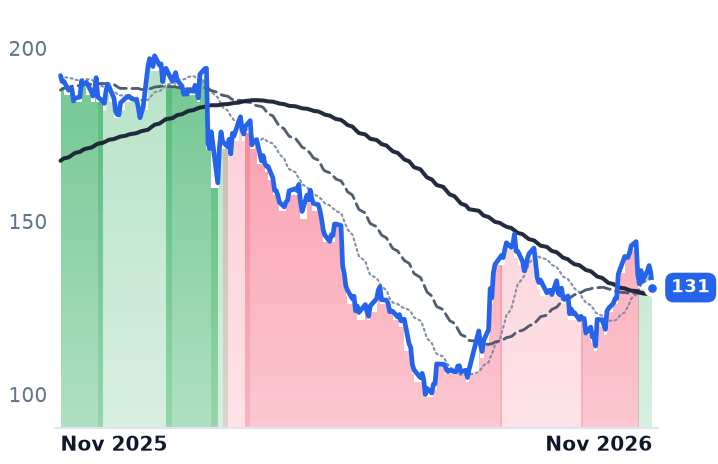
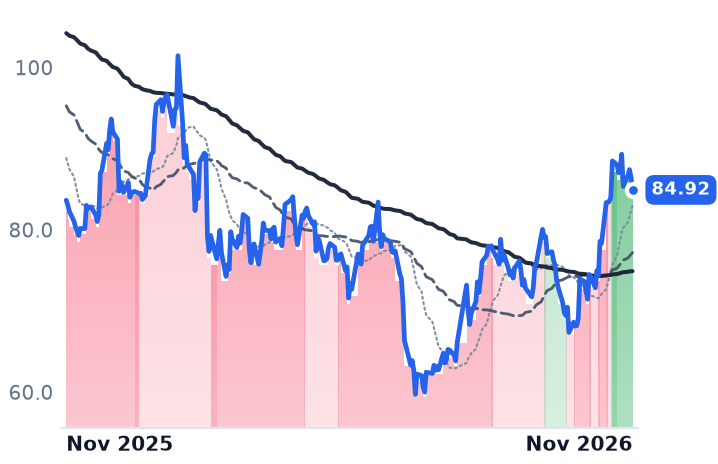
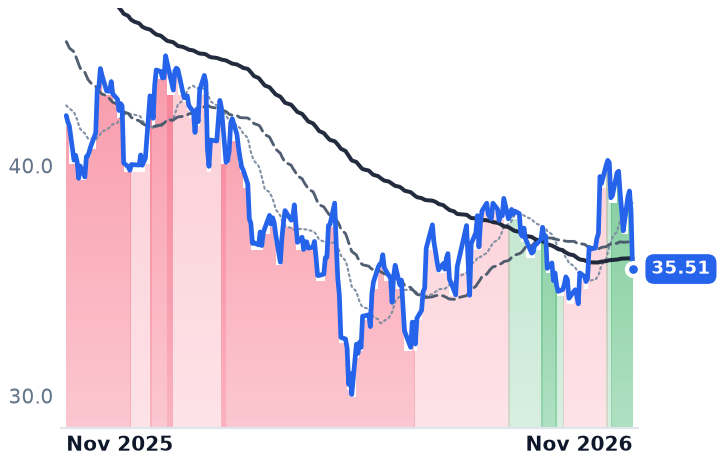
LDOS | Leidos | Defense & Government Services | 🔴 Cont. Bear | +8.9% | −31.9% |
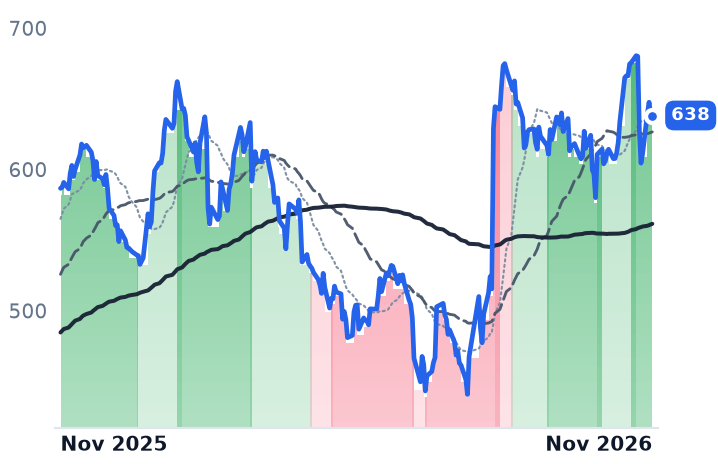
CACI | CACI International | Defense & Government Services | 🟢 Cont. Bull | +5.7% | +8.8% |
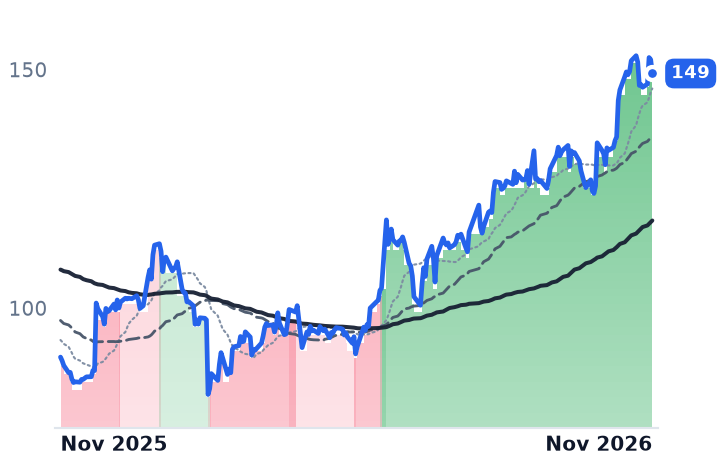
SAIC | Science Applications International | Defense & Government Services | 🟢 Cont. Bull | +12.7% | +66.3% |
| Compared against · context, not the story | |||||
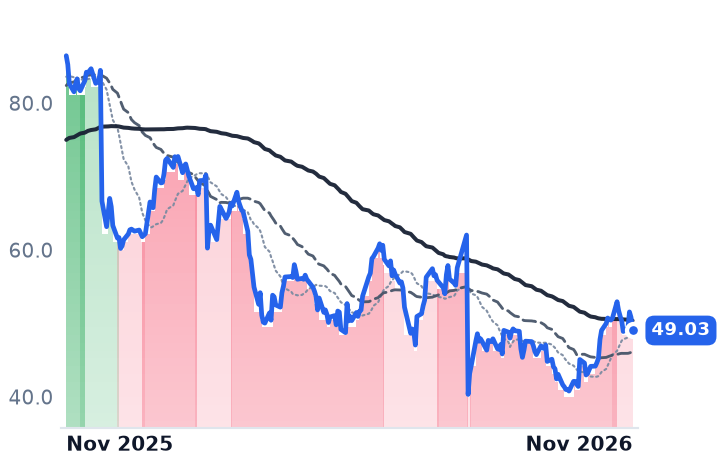
PSN | Parsons | Defense & Government Services | 🔴 Cont. Bear | +14.1% | −43.3% |
BAH | Booz Allen Hamilton | Government & Policy Advisory | 🔴 Cont. Bear | +17.3% | +1.5% |
KBR | KBR | Diversified Infrastructure | 🌱 Emerging Bull | +1.6% | −15.8% |
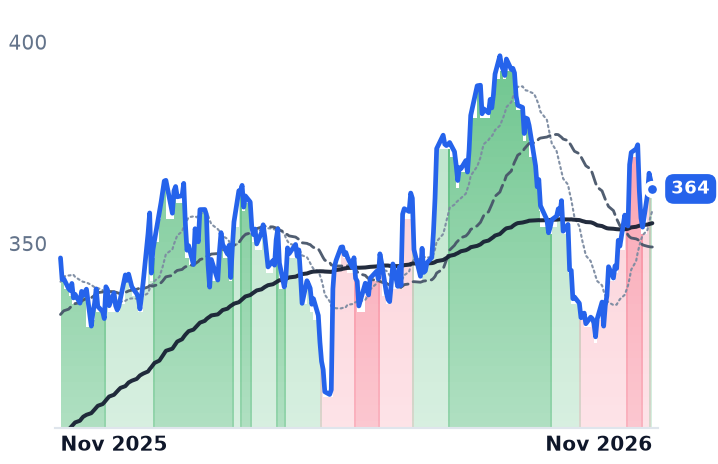
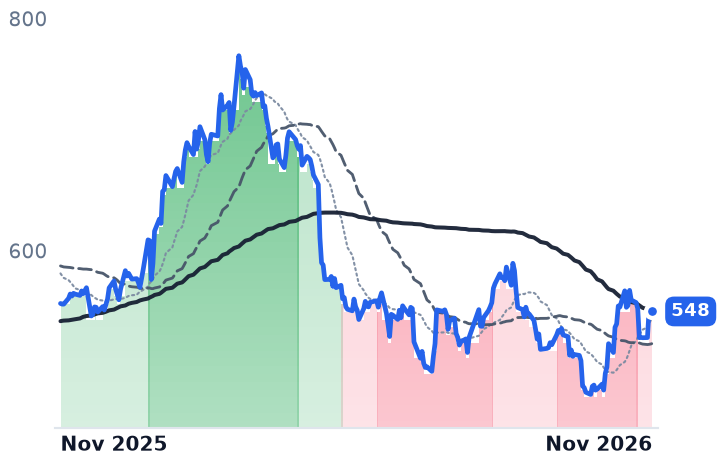
GD | General Dynamics | Integrated Defense Contractors | 🟢 Cont. Bull | +10.3% | +4.9% |
NOC | Northrop Grumman | Integrated Defense Contractors | 🔴 Cont. Bear | +14.1% | −1.2% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LDOS | $15.9B | 11.6x | 10.4x | 0.9x | 0.9x | 5.2x | 5.1x | 9.2x | 12.3% |
CACI | $14.2B | 26.2x | 19.1x | 1.5x | 1.3x | 6.7x | 6.1x | 16.7x | 9.0% |
SAIC | $6.3B | 17.3x | 13.8x | 0.8x | 0.9x | 6.7x | 6.8x | 11.8x | 9.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PSN | $5.3B | 36.0x | 20.2x | 0.8x | 0.8x | 3.8x | 3.8x | 13.9x | 7.8% |
BAH | $9.5B | 12.3x | 12.3x | 0.9x | 0.8x | 1.9x | 1.9x | 10.4x | 11.8% |
KBR | $4.9B | 11.8x | 9.8x | 0.6x | 0.6x | 4.4x | 4.2x | 8.8x | 7.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GD | $90.5B | 20.1x | 19.7x | 1.7x | 1.6x | 10.7x | 10.5x | 14.3x | 7.1% |
NOC | $70.4B | 15.7x | 17.1x | 1.6x | 1.6x | 8.2x | 8.0x | 11.3x | 5.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
LDOS | Revenue | +5.2% | +4.9% | +2.2% |
| EPS | +17.1% | +6.5% | −6.2% | |
CACI | Revenue | +10.9% | +13.1% | +6.7% |
| EPS | +14.2% | +19.9% | +13.5% | |
SAIC | Revenue | −2.4% | +0.4% | +1.3% |
| EPS | +15.3% | +7.2% | +6.2% | |
PSN | Revenue | −0.9% | +4.8% | +5.6% |
| EPS | −23.3% | +37.7% | +11.8% | |
BAH | Revenue | −6.1% | +0.7% | +4.2% |
| EPS | −4.3% | +5.1% | +5.1% | |
KBR | Revenue | +3.1% | +2.6% | +5.7% |
| EPS | +17.3% | +5.0% | +1.8% | |
GD | Revenue | +7.7% | +5.0% | +4.4% |
| EPS | +10.5% | +9.5% | +8.0% | |
NOC | Revenue | +5.3% | +6.9% | +6.2% |
| EPS | +11.0% | +5.0% | +8.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The money reaching federal technology contractors this autumn is arriving on contracts they already hold. Leidos, which integrates national-security systems for the Pentagon, runs air-traffic systems for the Federal Aviation Administration and manages federal health programs, booked $5.5bn of net orders in its September quarter. Its funded backlog — the slice of contract value for which Congress has actually released cash — rose 22%, to $11.1bn. The total backlog those orders sit inside grew 4%.
That gap between funded and total is the autumn's real finding, and it has been read as something else. Shares in the group rose over the past 30 days: SAIC 12.7%, Leidos 8.9%, CACI 5.7%. A single session on 9 October carried much of it, and it was confined to the services names — Leidos up 6.7%, SAIC 7.2%, Booz Allen 7.0% — while the hardware primes General Dynamics and Northrop Grumman moved 1.4% and 0.2%. No company-specific catalyst for that day was discoverable; the likelier reading is rotation into the cheapest contractor valuations.
Seventy-two days of money that starts nothing
Agencies have been funded since 1 October by a continuing resolution running to 11 December at largely prior-year levels, which holds the Pentagon at roughly $838.5bn against the $1.5 trillion it requested for fiscal 2027. A stopgap increments programs already running. It does not start new ones. What the funded-backlog growth records, then, is incumbency money rather than an awards recovery — and CACI's management said as much, calling the award pace sluggish and naming the December deadline as a headwind inside guidance.
CACI's margin arrived with an acquisition attached
CACI, which builds signals-intelligence, cyber and electronic-warfare systems for defense and intelligence agencies, had the loudest quarter. "We won $4.8 billion in awards, producing a 2x book to bill for the quarter," chief executive John Mengucci told investors on 22 October. Chief financial officer Jeffrey MacLauchlan added that "funded backlog increased by 15% year over year… the seventh time in the last 8 quarters we have delivered double digit year over year growth in funded backlog." Earnings before interest, taxes, depreciation and amortization reached 13.3% of revenue against 11.7%, and firm-fixed-price work — where a productivity gain stays with the vendor — rose to 33% of revenue from 27%, about half of that from the ARKA acquisition. Revenue grew 8.2%; organic growth was 2.1%. The shares carry 16.65x trailing EV/EBITDA, the dearest of the three, on 3.5x pro-forma leverage, and a trailing price/earnings ratio of 26.2x that is unchanged from a year ago.
Leidos is cheap for a reason with a date on it
Leidos raised full-year adjusted earnings guidance to $12.50-$12.70 from $12.20-$12.50, the third consecutive quarter of increases, and its shares are still down 32% over twelve months while trailing earnings grew. The overhang is one contract: the Health segment shrank 12%, to $1.07bn, on volumes tied to the Veterans Benefits Administration disability-examination program, now in recompete. "We believe it's highly likely our existing contracts will be extended through the first half of 2027, in line with the customers' planned new contract start date of July 1, 2027," chief executive Thomas Bell said on 3 November; a customer decision is expected around April or May. At 11.6x trailing and 10.4x forward earnings, against roughly 18x trailing a year ago, that single recompete is most of the de-rating.
SAIC's order book never joined the recovery
SAIC sells engineering, information-technology modernization and systems sustainment almost entirely to US government customers, and it is the one name where the awards story does not hold. Net bookings of about $1.2bn in the July quarter produced a 0.6x book-to-bill, with 0.8x over the trailing twelve months, against Leidos's 1.1x. It lost the RITS enterprise-information-technology recompete, worth about 350 basis points of second-half revenue, and the $1.4bn CASTLE-NET order went to Accenture Federal Services. "Our recompete win rate of over 90% this quarter creates an easier path to on-contract growth," chief executive James Reagan told investors on 31 August — a defense of retention, which is a different thing from winning new sockets. Reported revenue did inflect, up 6.3% in the quarter, but net income fell 19.7%.
The funding went one way and the valuations went another
The quarters account for the direction of the group and almost none of its ranking. Where Congress released cash — Leidos and CACI — the business improved measurably, and where the order book stayed under 1.0x, it did not. The market inverted that. SAIC's shares have gained 65% over twelve months, nearly all of it a move from about 11.6x trailing earnings to 17.3x, while consensus models fiscal 2027 revenue of $7.30bn against $7.26bn, growth of 0.6%. CACI, improving fastest in absolute terms, is priced for it: its 19.1x forward multiple needs roughly 40% earnings growth off a 2.1% organic base. Leidos, with the best conversion of funded dollars into revenue in the group, is the cheapest, because its problem has a hearing date rather than an open-ended one.
SAIC reports its third quarter around 3 December, a date the company has not confirmed. Whatever that print says about bookings, it lands eight days before the money underneath the whole group stops.