

NAPCO Makes Four-Fifths of Its Gross Profit on Fees for Radios It Already Sold
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
The most profitable revenue mix in NAPCO Security Technologies' history arrived in the same quarter the market decided the company had broken. Monthly alarm-service fees reached $26.1m at a gross margin above 90% and crossed half of total revenue, while the hardware line that seeds those subscriptions fell 7.3%.
Management blames two large locking distributors working down inventory, and says their customer sell-through still grew about 5%. The annuity side of the business is intact; the equipment side is the part the market can verify only one quarter at a time.
NAPCO now trades near 8.9x trailing gross profit against roughly 14.5x a year ago, even as trailing gross profit dollars grew 16.3%. Eight trading days earlier, Allegion was rewarded for the opposite quarter: volume and price together in non-residential locks.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
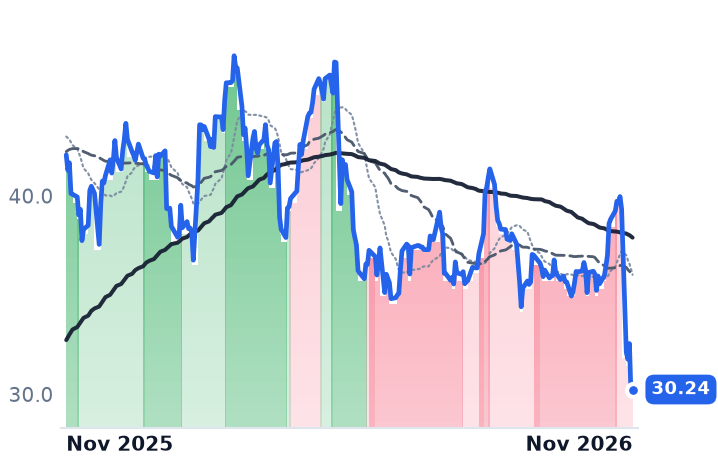
NSSC | Napco Security Technologies | Electronic Access Control | 🔴 Cont. Bear | −16.3% | −28.1% |
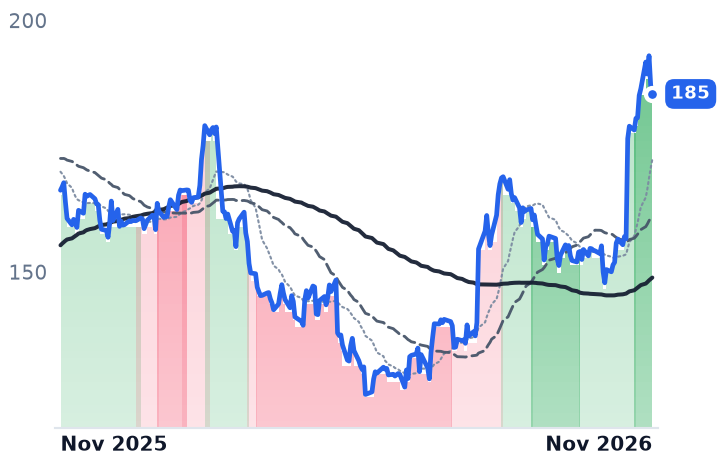
ALLE | Allegion | Electronic Access Control | 🟢 Cont. Bull | +23.2% | +11.5% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NSSC | $1.1B | 24.6x | 19.6x | 5.3x | 5.0x | 8.9x | 8.4x | 18.3x | 4.6% |
ALLE | $15.8B | 23.0x | 20.4x | 3.6x | 3.5x | 8.0x | 7.8x | 16.0x | 4.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
NSSC | Revenue | +13.5% | +8.0% | +8.0% |
| EPS | +31.0% | +3.6% | +13.2% | |
ALLE | Revenue | +10.1% | +6.0% | +5.0% |
| EPS | +11.1% | +11.7% | +9.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
NAPCO Security Technologies, which makes intrusion and fire alarms and the cellular radios that report them to monitoring stations, grew revenue just 1.7% in its September quarter, the slowest in two years of reported quarters. The same three months produced the most profitable revenue mix the company has ever had: recurring service fees of $26.1m at a gross margin of 90.1%, now 52% of the total, which lifted group gross margin to 58.7% from 56.6%.
Do the arithmetic the company's own disclosed margins allow and the subscription book throws off roughly $23.5m of the quarter's $29.35m of gross profit — about four-fifths of it. The quarter was read as evidence that the franchise is stalling. What stalled is the 24%-margin hardware line, and the question that matters is whether that line comes back, because the radios sold today are the fees billed for years.
The two distributors that stopped restocking
Equipment revenue fell 7.3% to $23.9m. Management attributes the decline to a prior-year comparison inflated by tariff-driven backlog and to two large locking distributors drawing down inventory, noting that those same distributors grew customer sell-through about 5% year on year and double digits sequentially, and that one resumed ordering in early October. Equipment gross margin slipped to 24.3% from 26.0% as the company's Section 301 tariff exposure rose from 10% to 12.5%; the full-year target is 26%-27%.
The annuity, meanwhile, rests on a legal requirement rather than a security budget. "Approximately 75% of our installed base is comprised of our Starlink fire radios, which are mandated in commercial buildings and it generates our most profitable recurring revenue," chief executive Kevin S. Buchel told investors on 2 November. The newer cloud access-control platform, MVP, bills $3 per door per month and signed its first national dealer in the quarter, though Buchel said adoption has been slower than he wanted, with dealer training the obstacle.
A cheaper annuity than a year ago
The shares fell about 17% in premarket trading on 2 November on revenue of $50.0m against $53.13m consensus, and kept falling for four sessions. Price-to-gross-profit is now near 8.9x, against about 11.8x a week before the print and roughly 14.5x a year ago, a de-rating of some 38% while trailing four-quarter gross profit dollars rose 16.3% to $121.3m. Trailing earnings understate the run rate: a $16m securities-litigation accrual produced a GAAP operating loss in the March quarter, and $15m was paid out in the September quarter, cutting free cash flow 79.8% to $2.3m against $134.6m of cash and no debt. The sell side cut targets without cutting ratings — DA Davidson to $45 from $52, Buy maintained.
Eight sessions earlier, the other meter was paid
Allegion, which sells Schlage locks, Von Duprin exit devices and electronic access-control systems through specialty distribution, reported revenue of $1,172.6m on 22 October, up 9.6% and 7.2% organically, with Americas non-residential up low double digits on volume and price together. It rose 12.7% in a session and 23.6% over the 30 days NAPCO fell 16.7%. "As we mentioned in second quarter, data centers were approaching 5% of our Non-Res business. I'd say it's there now, growing rapidly and has been a source of volume growth this year," chief executive John Stone said that day — narrow ground, given that US non-residential construction spending is on course to fall in 2026 for the first time since 2010 outside the pandemic year. Allegion now trades at 8.0x trailing gross profit against 6.5x at its April low, and 20.4x forward earnings against 23.0x trailing.
The split has a cause, and it is the point of sale. Allegion resets list prices several times a year — chief financial officer Michael Wagnes said on 22 October that "the days of just setting pricing once across the portfolio in early February, has kind of changed over the last couple of years" — and books the whole opening at once. NAPCO's hardware reaches the installer through distributors whose inventory decisions gate the radios, and each radio not shipped is a subscription not started. That is a timing risk on the annuity, not a margin risk; what the September quarter cannot settle is how many quarters of timing there are.
The de-rating is doing more work than the results support on the recurring side and less on the earnings side: consensus has NAPCO revenue up 8% in fiscal 2027 but earnings per share of $1.545 against $1.492, about 3.6% growth, so 19.6x forward is being paid for revenue analysts do not expect to drop through. Judge the business on the annuity and it compounded; judge it on next year's earnings and it did not.
The fee book NAPCO has built is the part no distributor can decline to restock. The radios that feed it still have to be bought by someone first.