

Dycom Guided Fiber Revenue Lower; ITG Beat Its Own Forecast and Fell Harder
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Two contractors do the same job — burying and splicing fiber for broadband, wireless and data-center customers — and the one whose results actually deteriorated is now the cheaper of the two.
Dycom's organic revenue growth halved to 16.7% in the quarter to 1 August as gross margin slipped to 16.2% from 17.9%, and it guided the October quarter below the quarter it had just reported. ITG, listed only since July, pre-announced third-quarter revenue of about $461.5m, some 5% above its own outlook, and has fallen harder than Dycom over the past month.
The mechanism both share is cost arriving before revenue: crews, subcontractors and fleet are paid to mobilize quarters before the miles bill. Dycom's markdown has a disclosed cause behind it. ITG's does not.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
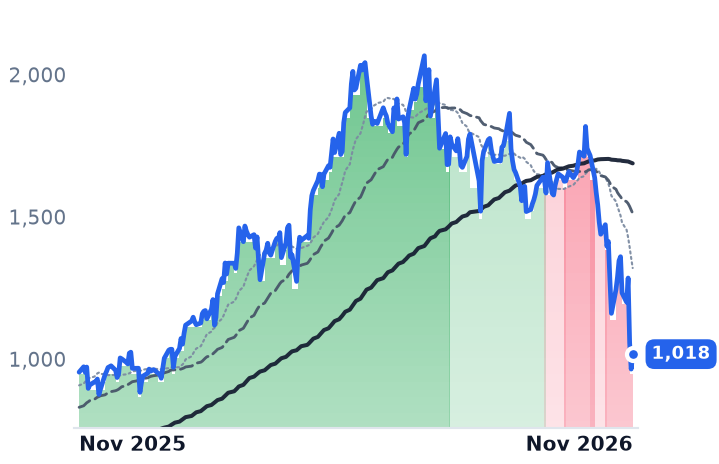
DY | Dycom Industries | Digital & Communications | ⚠️ Emerging Bear | −25.5% | −27.5% |
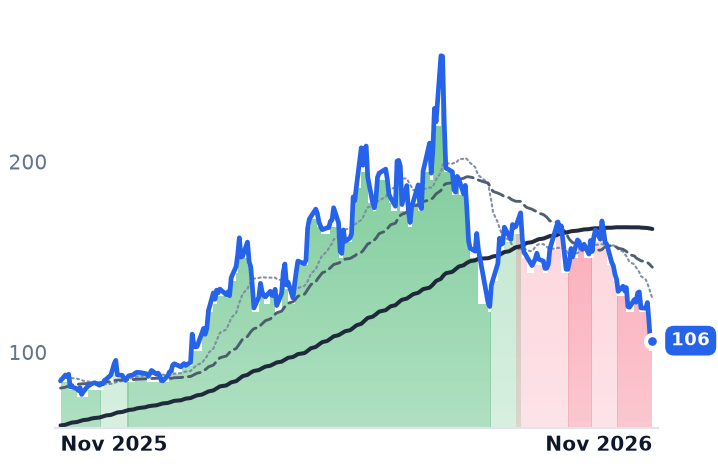
ITG | ITG | Digital & Communications | 🔴 Cont. Bear | −40.0% | −74.2% |
| Compared against · context, not the story | |||||
MTZ | MasTec | Energy Solutions | 🔴 Cont. Bear | −20.1% | −13.1% |
EME | EMCOR | Power Grid & Distribution | 🔴 Cont. Bear | −22.1% | −6.2% |
FIX | Comfort Systems USA | Building Systems | ⚠️ Emerging Bear | −41.1% | +6.6% |
GLW | Corning | Connectors & Substrates | ⚠️ Emerging Bear | −32.7% | +24.8% |
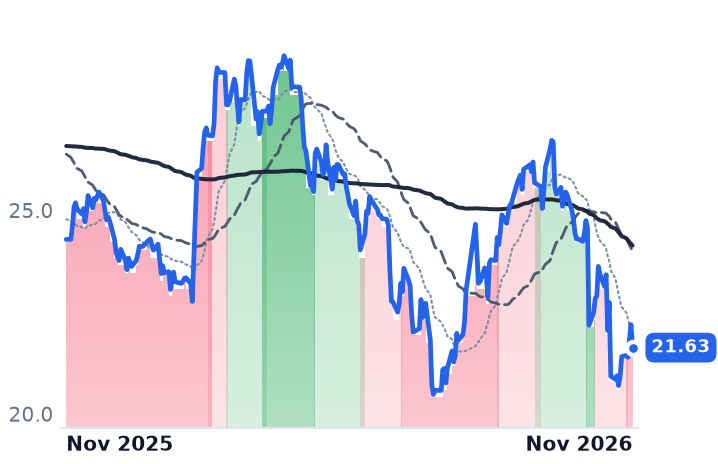
T | AT&T | US Tier-1 Wireless Carriers | 🔴 Cont. Bear | −12.0% | −10.9% |
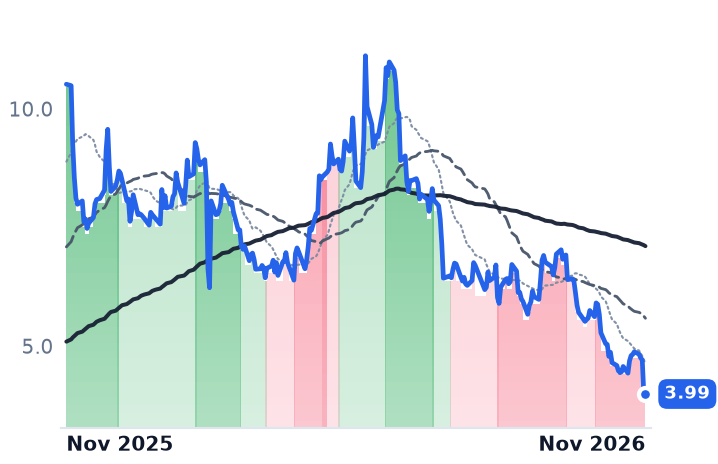
LUMN | Lumen Technologies | North American Cable & Broadband | 🔴 Cont. Bear | −29.6% | −62.1% |
VZ | Verizon Communications | US Tier-1 Wireless Carriers | ⚠️ Emerging Bear | −0.4% | +17.9% |
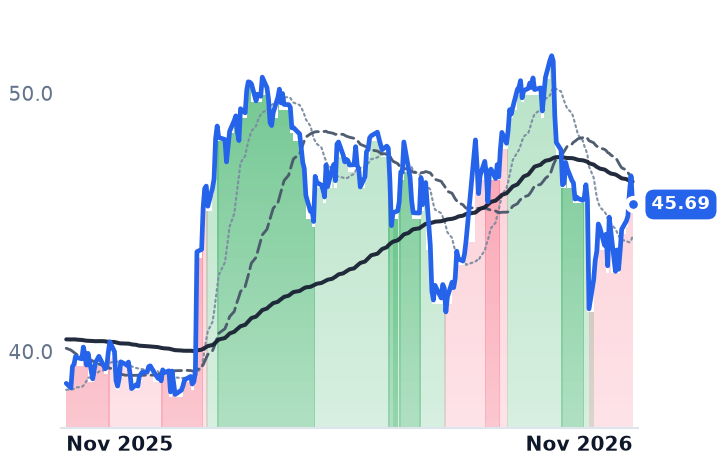
12-month price & trend
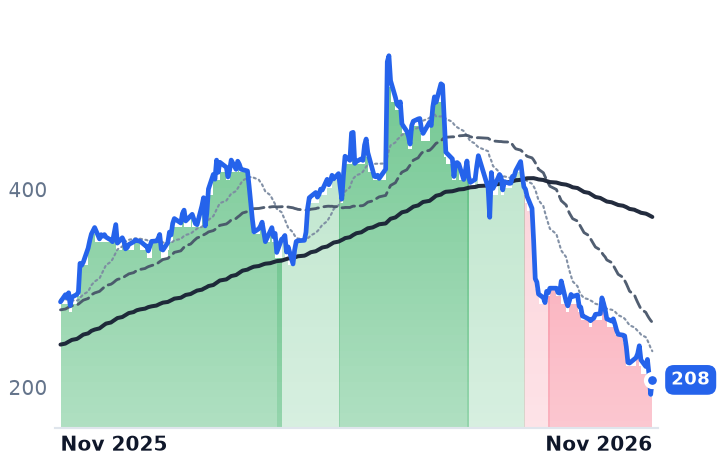
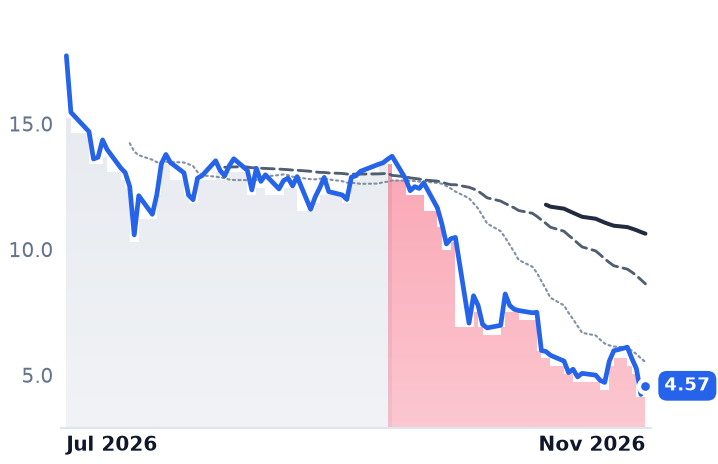
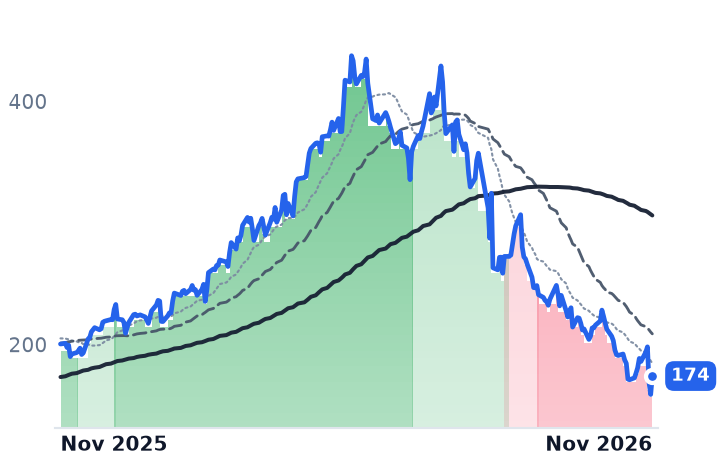
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DY | $6.3B | 18.7x | 12.2x | 0.9x | 0.8x | 4.8x | 4.3x | 7.7x | 7.5% |
ITG | $554.6M | n/m | 8.5x | 0.8x | 0.4x | 5.1x | 2.4x | 17.6x | -11.4% |
MTZ | $13.7B | 26.9x | 18.5x | 0.9x | 0.8x | 7.4x | 6.6x | 12.7x | 1.8% |
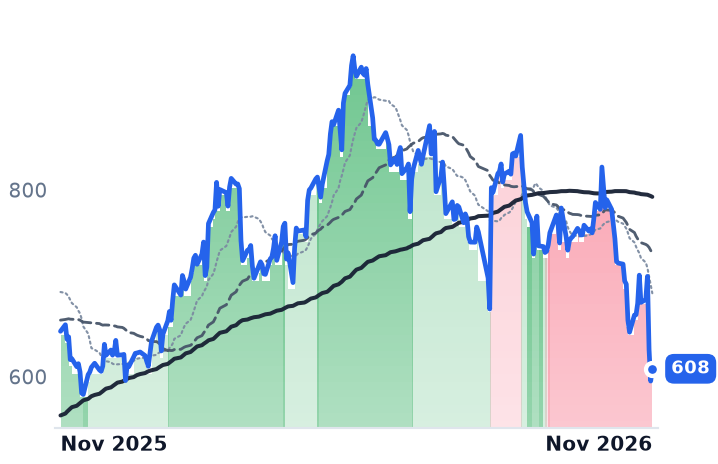
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EME | $26.1B | 17.2x | 17.1x | 1.3x | 1.2x | 6.6x | 6.3x | 10.8x | 5.7% |
FIX | $34.0B | 20.8x | 18.9x | 2.7x | 2.5x | 10.6x | 9.7x | 14.2x | 7.2% |
GLW | $90.5B | 42.1x | 31.3x | 5.1x | 4.7x | 14.0x | 12.8x | 20.4x | 2.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
T | $170.5B | 8.2x | 10.6x | 1.3x | 1.3x | 2.2x | 2.2x | 5.9x | 10.4% |
LUMN | $5.7B | n/m | — | 0.5x | 0.5x | 1.0x | 1.1x | 7.7x | 14.7% |
VZ | $202.4B | 12.6x | 9.7x | 1.5x | 1.4x | 2.5x | 2.4x | 8.1x | 10.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
DY | Revenue | +17.1% | +39.7% | +12.6% |
| EPS | +39.5% | +51.0% | +19.9% | |
ITG | Revenue | — | +21.3% | — |
| EPS | — | +70.4% | — | |
MTZ | Revenue | +29.3% | +18.3% | +14.7% |
| EPS | +44.4% | +33.2% | +31.1% | |
EME | Revenue | +24.5% | +14.1% | +8.9% |
| EPS | +37.3% | +17.5% | +13.9% | |
FIX | Revenue | +56.0% | +26.7% | +16.0% |
| EPS | +93.9% | +31.2% | +19.5% | |
GLW | Revenue | +18.6% | +20.6% | +21.4% |
| EPS | +33.2% | +34.1% | +37.0% | |
T | Revenue | +3.4% | +2.1% | +2.1% |
| EPS | +13.6% | +9.4% | +13.7% | |
LUMN | Revenue | −10.4% | −3.8% | −1.4% |
| EPS | +41.1% | −64.4% | −30.2% | |
VZ | Revenue | +2.3% | +1.7% | +1.1% |
| EPS | +6.8% | +4.7% | +7.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Dycom Industries, which engineers, buries and splices fiber for carriers including AT&T, Verizon and Lumen, told investors in August that its next quarter would bring in less revenue than the one it had just reported. The guide was $1.90–1.98bn against the $2.006bn delivered in the quarter to 1 August, with an adjusted earnings midpoint of $4.56 a share below the $4.79 consensus. ITG, a smaller contractor doing the same outside-plant work for regional fiber builders, pre-announced a third quarter above its own outlook on 22 October. Over the month to 6 November Dycom lost roughly a quarter of its market value and ITG two-fifths.
Both were bought as the ground crew of the AI interconnect buildout, on the belief that hyperscaler dark fiber and intercity routes were already landing in contractor revenue. Dycom's latest reported quarter says otherwise: it carried only "initial revenue contribution from fiber infrastructure programs for hyperscalers," while AT&T and Verizon each exceeded 10% of total revenues. Carrier access spending still sets the revenue line, and the cost of standing up crews sets the margin.
What a mobilized crew costs before it bills
Dycom's headline growth of 45.6% was flattered by purchases — Power Solutions in December 2025 and National Technology Integrators on 2 July 2026 for $275m, which contributed $22.9m in the quarter. Organic growth was 16.7%, down from 24.7% three months earlier. Gross margin fell to 16.20% from 17.90%, and the Communications segment margin dropped 134 basis points to 13.6% on expansion investment, deferred wireless work and fuel. The order book moved the other way: total backlog reached a record $12.242bn, up 53.2%, with $6.472bn due inside twelve months. Days sales outstanding improved to 101 from 108, so this is not cash trapped between digging and being paid.
ITG puts the same cost in plainer language. Its second-quarter adjusted EBITDA margin was 12.9% against 14.8% a year earlier, attributed primarily to "startup costs associated with onboarding and mobilizing employees and subcontractors, deploying fleet and equipment, establishing local operating infrastructure and preparing new programs for customer launch." Dycom's chief executive Dan Peyovich framed the payoff on the 26 August call: "We are comfortable scaling that business, and that is really where you see the margin raise, the high teens to low 20s as we go forward."
The carrier number behind the guide
MasTec supplied the read-across on 29 October. Its Communications revenue fell 12% to $807m and segment adjusted EBITDA fell 41% to $61m, because customers deferred second-half spending amid speculation about a potential fourth nationwide wireless carrier and announced reorganizations at major customers. MasTec expects a flattish Communications year in 2027, with carrier weakness offsetting hyperscaler and federally funded rural broadband growth. That last programme is not yet paying contractors either: more than $22bn of the $42.45bn Broadband Equity, Access and Deployment allocation sat at the Commerce Department as of June 2026, Texas paused disbursements in August, and most funded construction reaches end users in 2027 or 2028.
ITG's drop is not in its filings
ITG priced its initial public offering at $16.00 on 1 July, below its $19–22 range, and now trades at $4.575. Its next-twelve-months backlog rose to $1,517m from $1,259m on awards from Ziply Fiber and Intrepid Fiber Networks, and preliminary third-quarter adjusted EBITDA of about $64.5m beat its own $63.0m outlook. Its worst session was 28 September, a 32.5% fall with no discoverable company disclosure; short interest rose 209% between the 15 and 30 September settlement dates, to 1.76m shares. The likelier reading is a seller rather than a business break.
Price per dollar of Dycom's trailing gross profit is 4.80x, against 9.6x in late August and 12.05x in mid-May; forward earnings are 12.19x against 18.71x trailing, EV/EBITDA 7.68x and the trailing free-cash-flow yield 7.49%. ITG's trailing earnings are unusable on a small loss, leaving 8.47x forward earnings and 2.42x forward gross profit against 5.08x trailing — with a trailing free-cash-flow yield of minus 11.4%.
So the de-rating splits on cause. Dycom's August-to-October leg is explained by its own disclosures: halved organic growth, a compressed segment margin, a sequential guide down. Its last two sessions before 6 November, down 7.2% and 9.3% to new lows, carried no company news and coincided with voters approving data-center restrictions in 40 of 41 jurisdictions — the political risk that repriced power equipment this week. On ITG's side there is no reported deterioration at all, only mobilization costs the company has quantified and a guide it has now exceeded twice.
ITG publishes full third-quarter numbers after the close on 10 November; Dycom reports in mid-to-late November. One of them will show whether the crews hired this year have started to bill.