

AI Hardware Earns Computer Resellers a Thinner Margin, and Insight Is the Exception
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Four companies that buy computer hardware and sell it on reported inside nine days, and all four showed the same thing: sales inflating faster than gross profit for the third straight quarter. The memory shortage is reaching them as a bigger invoice, not a better spread.
CDW kept 12.8 cents of gross profit on each additional dollar of sales against 20.5 cents across its whole book. Ingram Micro kept 4.9 cents as its GPU and AI infrastructure revenue climbed to $1.8bn. Insight Enterprises is the only one whose new revenue was essentially non-dilutive, and roughly half its gross profit now comes from cloud and core services.
The earnings growth came from overhead cuts at all of them. The market has paid up for CDW, dearest of the four at 3.81x trailing gross profit, and marked down the two that raised guidance.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
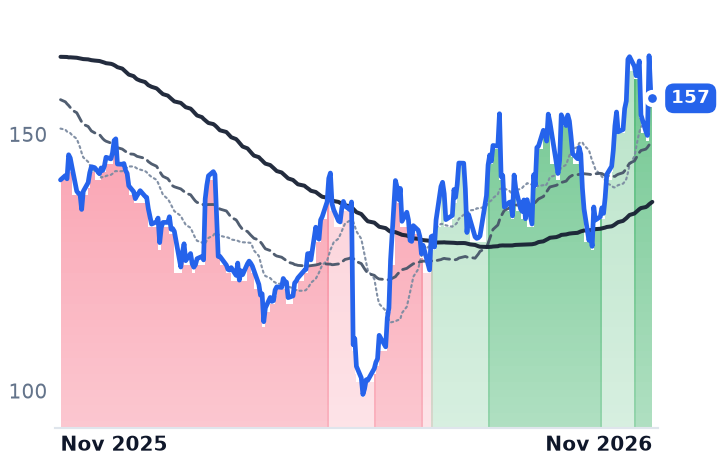
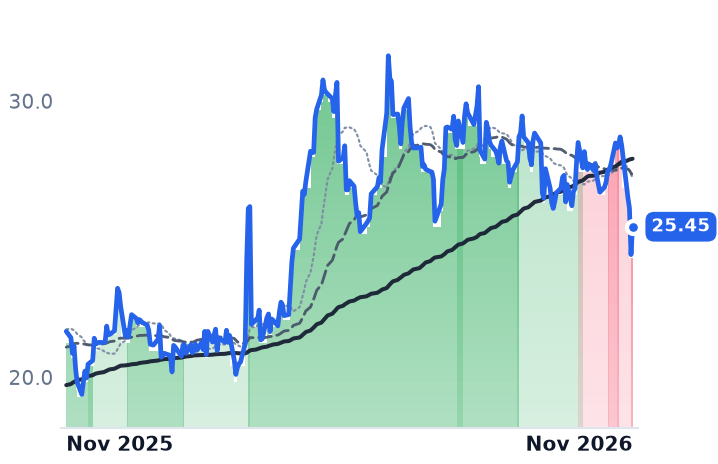
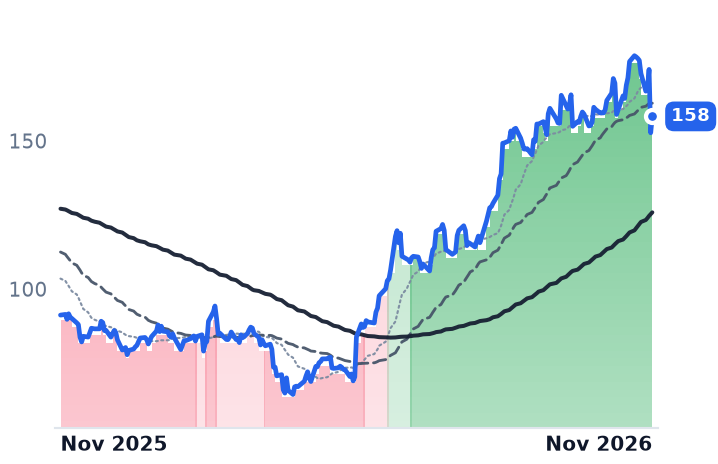
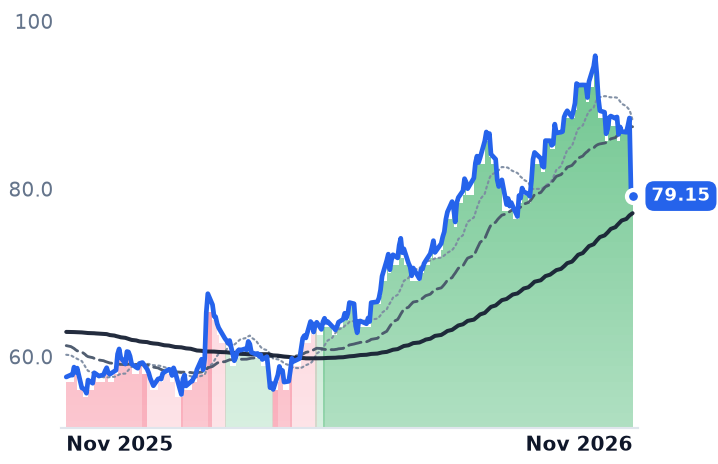
CDW | CDW | IT Infrastructure & Services | 🟢 Cont. Bull | +14.1% | +11.3% |
INGM | Ingram Micro | IT Infrastructure & Services | ⚠️ Emerging Bear | −7.5% | +17.5% |
NSIT | Insight Enterprises | IT Infrastructure & Services | 🟢 Cont. Bull | −1.4% | +73.5% |
DXC | DXC Technology | IT Infrastructure & Services | 🌱 Emerging Bull | +24.0% | +12.9% |
KD | Kyndryl | IT Infrastructure & Services | 🌱 Emerging Bull | +43.0% | −38.2% |
NABL | N-able | IT Infrastructure & Services | 🔴 Cont. Bear | +6.5% | −41.3% |
| Compared against · context, not the story | |||||
CNXN | PC Connection | Enterprise IT Distribution | 🟢 Cont. Bull | −12.9% | +37.5% |
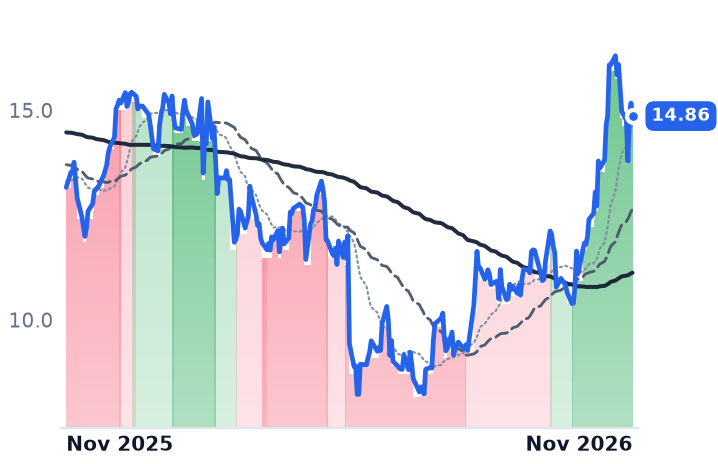
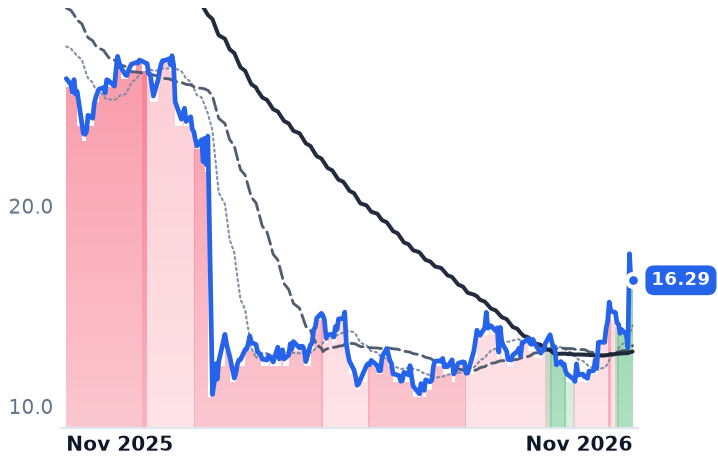
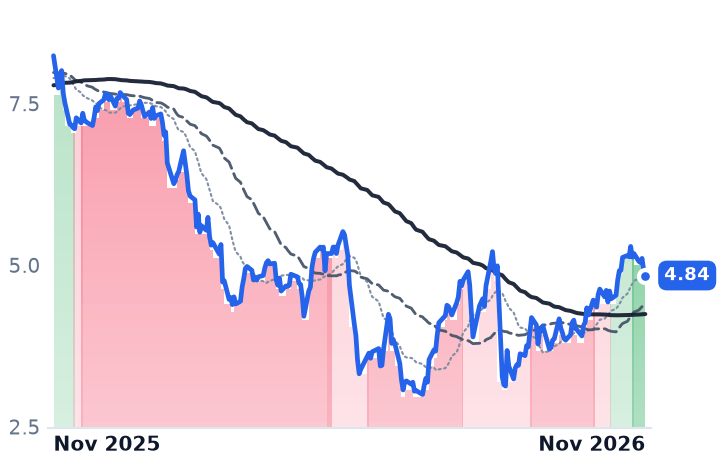
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CDW | $19.6B | 18.2x | 14.0x | 0.8x | 0.8x | 3.8x | 3.7x | 13.9x | 6.0% |
INGM | $5.9B | 12.8x | 7.1x | 0.1x | 0.1x | 1.5x | 1.5x | 7.0x | 2.6% |
NSIT | $4.6B | 26.4x | 12.7x | 0.5x | 0.5x | 2.3x | 2.4x | 12.4x | 5.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CNXN | $2.0B | 19.5x | 17.7x | 0.6x | 0.6x | 3.4x | 3.3x | 12.6x | -1.0% |
DXC | $2.3B | 20.9x | 6.2x | 0.2x | 0.2x | 1.2x | 1.3x | 3.0x | 44.6% |
KD | $3.5B | 11.1x | 8.8x | 0.1x | 0.2x | 0.6x | 1.1x | 3.2x | 2.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NABL | $914.3M | n/m | 12.4x | 1.7x | 1.7x | 2.2x | 2.2x | 17.2x | 8.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CDW | Revenue | +12.6% | +5.4% | +4.6% |
| EPS | +13.5% | +10.4% | +10.0% | |
INGM | Revenue | +17.8% | +3.7% | +4.9% |
| EPS | +25.8% | +8.6% | +12.5% | |
NSIT | Revenue | +6.7% | +3.8% | +6.2% |
| EPS | +28.5% | +6.0% | +16.6% | |
CNXN | Revenue | +13.6% | +3.7% | +6.8% |
| EPS | +31.2% | +7.1% | +7.9% | |
DXC | Revenue | −1.2% | −5.7% | −3.0% |
| EPS | −5.6% | −24.8% | +12.0% | |
KD | Revenue | +0.4% | −2.0% | −0.0% |
| EPS | +49.9% | +5.8% | +37.4% | |
NABL | Revenue | +6.4% | +6.1% | +9.1% |
| EPS | −7.9% | +11.2% | +11.6% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Between 28 October and 5 November, the four companies that buy computer hardware from manufacturers and sell it on to corporate, small-business and public-sector buyers each reported a record quarter and a thinner spread. Ingram Micro's net sales rose 20.8% to $15.2bn; its gross profit rose 14.6%. CDW, PC Connection and Insight Enterprises printed the same shape, and all four lost gross margin percentage year on year.
The quarters were read as AI demand finally arriving in the channel. What they document instead is a bill of materials inflating faster than the markup charged on it, with the earnings growth arriving from somewhere else entirely.
What one more dollar of hardware pays
CDW's net sales rose 17.7% to $6.75bn while gross profit rose 10.3% to $1.39bn. Netting the two quarters, $1,017m of additional revenue carried $130m of additional gross profit: 12.8 cents on the incremental dollar, against 20.5 cents across the whole book. Ingram Micro, the wholesale rung above the resellers, managed 4.9 cents against a 6.55-cent average, because its GPU and AI infrastructure revenue went from roughly $700m a year ago to $1.8bn. Strip those deals out and its gross margin was 7.06% against 7.10% — flat. PC Connection earned 14.1 cents against an 18.5-cent average.
The mechanism sits in the component. Memory and storage now run about 35% of a PC's bill-of-materials cost against a historical 15% to 18%, and more than half the materials cost of a traditional server. A reseller buys at the inflated component price and sells at a percentage markup that does not scale with it, so revenue rises by the full cost increase and gross profit only by the markup on that increase. Contract prices for conventional memory are expected to rise a further 10% to 20% quarter on quarter in the fourth quarter on the research firm TrendForce's projection, after 58% to 63% in the second.
The volume data make the point sharper. CDW reported client-device average selling prices up 19% even as units declined, attributing the rise to price increases and richer configurations with more processing power and memory. PC Connection's notebook revenue grew 30% while notebook units fell about 5%. Insight's devices revenue grew 30% on units up low single digit.
Demand itself is not the constraint. "Writings continue to outpace invoicing, and backlog is building, particularly in enterprise infrastructure," chief executive Chris Leahy told CDW investors on 4 November.
Insight's half-services book
Insight is the one name whose new revenue was essentially non-dilutive: 20.3 cents of gross profit per incremental dollar against a 21.4-cent average, on net revenue up 21.8% and gross profit up 20.5%. The reason is mix. Cloud gross profit reached $164m, up 26%, and core services $95m, up 21% — together roughly half the company's gross profit. Infrastructure hardware gross profit rose more than 50%, but hardware gross margin fell 100 basis points on device pricing and client mix.
"We are raising our gross profit growth expectations to 12.5% to 14%, and our gross margin will be approximately 21.5%," chief financial officer James Morgado said on 5 November.
The rescue came from overhead
At CDW, non-GAAP selling and administrative costs grew 5.6% against 10.3% gross profit growth, lifting non-GAAP operating income 17% to $620m; chief financial officer Al Miralles credited "Geared for Growth efforts kicking in." Ingram Micro cut operating expenses to 4.62% of sales from 5.13% and lifted adjusted operating income 25% to $322m. PC Connection improved overhead by 150 basis points of sales and grew operating income 35.4%. Carrying the bigger invoices costs cash: PC Connection burned $39.8m of operating cash over nine months on a $144.8m receivables increase.
Priced inversely to the gross profit
CDW has risen 15.6% in three months to 3.81x trailing gross profit, the dearest of the four and above the 3.74x at which PC Connection stood in September, on the second-thinnest incremental spread — while management guides full-year gross margin below 2025. Ingram Micro, which beat a $13.85bn consensus revenue estimate and cut net leverage to 1.9x, trades at 7.11x forward earnings and 1.34x book; it gave back a 6.1% after-hours gain the next session and is down 10.4% over three months. Insight sits at 12.66x forward earnings and fell 12.3% on the day it raised guidance — the same session the Nasdaq 100 fell 6.4% on fears of a slower data-center buildout, which also took PC Connection down 9.9%.
So the results account for the earnings growth. They do not account for the ranking.
Every one of these companies converted a slower-growing gross line into a faster-growing operating line, which is a cost story with a floor under it, and none of them captured the component inflation as margin: it was passed through to the customer and spent on the component. Insight's exception is structural, built out of cloud and core services gross profit that now carries half the book. Ingram Micro's discount contains a forward cycle call as well as a valuation: management has guided 2027 to moderate single-digit growth as the PC refresh ends and pricing moderates, so the cheapest name in the group also carries the clearest statement that the revenue wave stops.
Ingram Micro's fourth-quarter guidance assumes supply constraints add two to three percentage points to its sales. That is the trade these companies are in: the shortage is worth something real on the invoice, and so far almost nothing on the spread.