

Monolithic Power Books the Rack-Power Dollars While Its Rivals Announce 800-Volt Wins
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
The architectural shift that is supposed to multiply power-conversion silicon inside every AI rack has not paid anyone yet. Monolithic Power's Enterprise Data revenue reached $506.7m last quarter, 42.1% of the company, and none of it is high-voltage direct-current content: its gallium-nitride parts are only sampling, with revenue dated to late 2027.
Navitas, the pure-play that publicised the new architecture with Nvidia, guides December revenue to $16.0m, of which more than 40% is AI infrastructure — roughly $6.4m. Its gross margin did at least swing positive, to 39.3%.
The real challenge to Monolithic Power's socket is arriving by other routes: onsemi paid $600m in cash for Ferric's integrated voltage regulators, and Vicor is licensing vertical power delivery rather than selling it.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
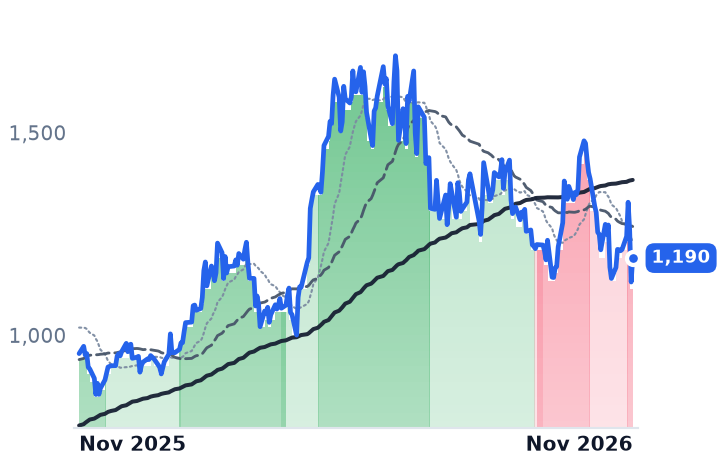
MPWR | Monolithic Power Systems | Analog & Power Management | ⚠️ Emerging Bear | −15.1% | +24.7% |
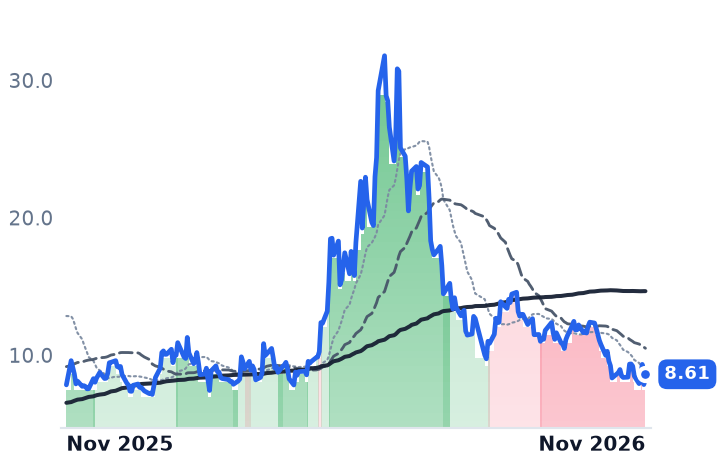
NVTS | Navitas Semiconductor | Analog & Power Management | 🔴 Cont. Bear | −22.3% | +9.8% |
| Compared against · context, not the story | |||||
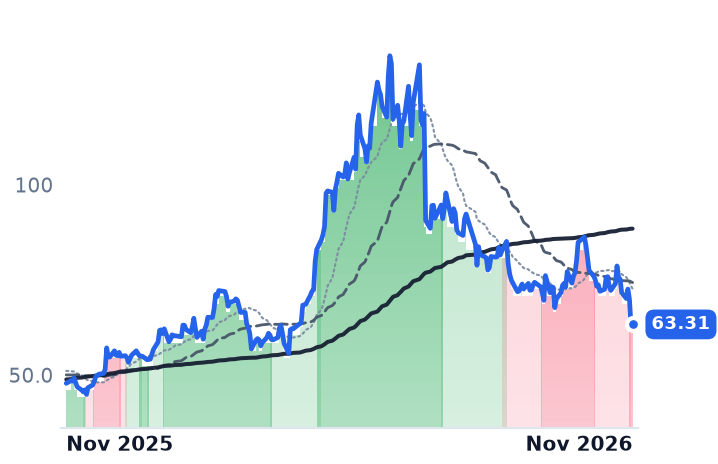
ON | ON Semiconductor | Analog & Power Management | ⚠️ Emerging Bear | −21.9% | +32.4% |
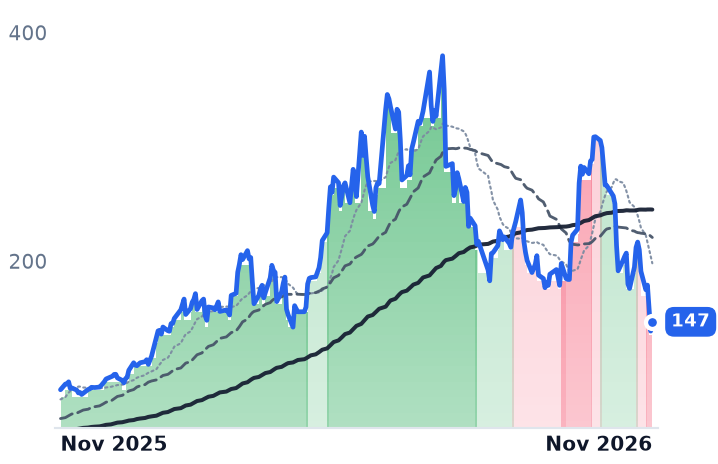
VICR | Vicor | Power Conversion & Control | ⚠️ Emerging Bear | −44.9% | +68.0% |
IFX.DE | Infineon Technologies | Semiconductors | ⚠️ Emerging Bear | −23.3% | +35.9% |
NVDA | NVIDIA | Processors & Accelerators | 🟢 Cont. Bull | −21.2% | −0.8% |
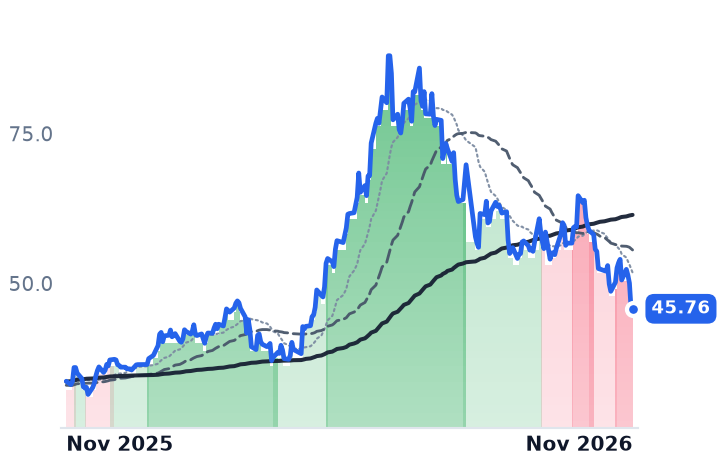
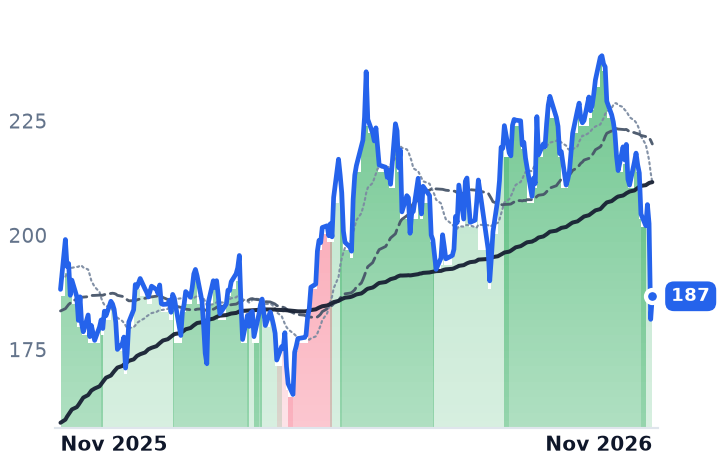
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MPWR | $58.1B | 65.4x | 40.9x | 15.5x | 13.4x | 28.1x | 24.3x | 48.3x | 1.0% |
NVTS | $2.2B | n/m | — | 55.6x | 45.9x | 388.3x | 320.6x | n/m | -3.4% |
ON | $24.6B | 36.0x | 19.3x | 3.9x | 3.7x | 10.1x | 9.7x | 15.2x | 6.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VICR | $8.3B | 45.5x | 43.2x | 14.7x | 12.9x | 24.3x | 21.2x | 44.8x | 0.6% |
IFX.DE | $77.5B | 70.8x | 35.7x | 5.1x | 4.9x | 13.0x | 12.4x | 22.0x | 1.5% |
NVDA | $5.5T | 34.3x | 25.0x | 21.5x | 13.9x | 29.0x | 18.7x | 28.3x | 2.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
MPWR | Revenue | +55.8% | +51.2% | +24.7% |
| EPS | +64.5% | +58.9% | +25.5% | |
NVTS | Revenue | +7.5% | +65.0% | +66.1% |
| EPS | −15.3% | +25.7% | −32.2% | |
ON | Revenue | +10.1% | +14.9% | +12.4% |
| EPS | +40.9% | +44.3% | +27.1% | |
VICR | Revenue | +41.7% | +46.9% | +25.4% |
| EPS | +91.8% | +53.2% | +33.3% | |
IFX.DE | Revenue | +8.5% | +14.3% | +11.4% |
| EPS | +15.2% | +43.7% | +21.9% | |
NVDA | Revenue | +65.1% | +84.2% | +43.2% |
| EPS | +59.0% | +91.7% | +42.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The change in rack power architecture that is meant to multiply the dollars of power silicon sitting beside every accelerator has so far paid its loudest advocates almost nothing. Monolithic Power Systems, which designs the direct-current-to-direct-current conversion chips that step voltages down for processors, booked $506.7m of Enterprise Data revenue in its September quarter, and by its own account none of that is 800-volt content: its gallium-nitride parts are sampling, with revenue dated to late 2027 and a material ramp to 2028.
The move from 12-volt to 48-volt in-rack distribution and now to 800-volt direct current was read as the reason to own the gallium-nitride specialists and to fear for the incumbent's position. What the last two prints show is the reverse order of payment. The incumbent's dollars are accelerating at today's architecture; the architectural pure-play is shipping single-digit millions; and the credible threat to the final conversion stage is being bought and litigated rather than engineered in 800 volts.
The socket that pays today
Monolithic Power's Enterprise Data line ran $262.8m, $380.6m and $506.7m through the first three quarters of 2026, reaching 42.1% of revenue in the September quarter, up 164.6% year on year — roughly a $2.0bn annualized rate out of the quarter just filed. Total revenue growth did not decelerate into that mix: 26.1%, then 47.6%, then 63.1%. Gross margin moved 20 basis points across four quarters, ending at 55.35%, and management raised its Enterprise Data growth floor to 150% from 130%.
The margin stability has a stated mechanism. Asked on 29 October about rising foundry wafer costs, chief executive Michael Hsing said: "We definitely absorb some of the cost increase. And not that we don't increase the price, okay? And we some -- we share the cost with -- the cost increase with our customers." He added: "During the capacity constraint, we don't gouge our customers." The company says existing capacity supports a $6bn annual rate, targets $8bn in the second half of 2027, and needs no significant capital spending to get there.
It is still the expensive name in its own complex: 40.9x forward earnings and 65.4x trailing, against 85.5x trailing in mid-August and 117.7x in May. onsemi, by contrast, trades at 19.3x forward earnings.
The 800-volt bill is not due yet
Industry work on the transition sizes the prize precisely: power-semiconductor content per rack is estimated to grow more than sixfold by 2027, reaching roughly $140,000 at today's prices from about $15,000, as rack power climbs from around 120kW toward 600kW and above.
Navitas, which sells gallium-nitride power chips and silicon-carbide devices and employs 190 people, is the purest listed claim on that chain. Its quarter inflected: revenue of $13.99m, up 38.4%, with reported gross margin swinging to 39.3% from -9.5% three months earlier, an operating loss narrowing to $10.9m excluding stock compensation and acquisition items against a reported loss of $34.4m. December revenue is guided to $16.0m with more than 40% from AI infrastructure, about $6.4m. Operating expense is guided to $25.0m.
Chief executive Chris Allexandre dated the compounding himself on 3 November: "it's not inconceivable to see the quarter-over-quarter compound growth to start to accelerate late '27 into '28 into '29." Breakeven, as management frames it, needs quarterly revenue in the low $60m range. The company ended September with $531.5m of cash and no debt, near $405m after the Claros acquisition, and has 45.9x forward sales to defend.
Cash and patents, not volts
The pressure on the last conversion stage is coming from buyers. onsemi agreed to pay $600m in cash plus $175m of earnouts for Ferric's integrated voltage regulators, and lifted its 2030 AI data-center target by $500m to above $3bn; its AI data-center revenue was $180m last quarter, roughly $620m expected for the year. "Ferric blows away everybody's z-height," chief executive Hassane El-Khoury said on 2 November.
Vicor is charging for permission instead of parts: $66.6m of its $197.1m quarter was patent royalties, gross margin reached 68.3%, and an International Trade Commission investigation seeks to exclude unlicensed vertical-power systems. Infineon, the German power-chip maker guiding to about €16.3bn for its fiscal year, announced a gallium-nitride intermediate-bus collaboration with Nvidia on 21 October.
What the selloff did and did not know
Monolithic Power fell 17.0% in the 30 sessions to 6 November and sits 29.6% below its 3 June close; Navitas fell 25.2% and is 72.9% below 26 May. Both lost most of it on 5 November, when the Philadelphia Semiconductor Index dropped 12.25% on Qualcomm's handset guidance, with incoming senators calling for brakes on data-center construction. No company-specific development for Monolithic Power surfaced that day, and it was the mildest faller in the group: Vicor lost 48.0%, Infineon 25.0%, onsemi 24.8%.
So the two markdowns do not mean the same thing. Monolithic Power's quarter accelerated and its margin held, which leaves sector-wide repricing and policy risk around AI capital spending as the likelier reading of its fall. Navitas's quarter also improved, but the decline is unwinding a May spike in a name still priced on 2029 volumes.
The open question is disclosure. Neither Monolithic Power nor its largest customer publishes per-platform power allocation; management quantifies the ramp only as content gains as new platforms arrive. Investors have been burned on exactly that gap before: in November 2024 a research note that Monolithic Power's Blackwell allocation was "at risk", with Renesas said to have taken part of it, cost the shares about a quarter of their value in a session.
When the rack power bill really arrives, it will be large enough that nobody will have to guess who won it. Until then the only names collecting are the ones selling into the architecture already installed.