

Fiserv Still Gets Paid for the Swipe; Toast and Square Are Taking the Software Invoice
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Clover's payment volume and its swipe pricing both held up last quarter. What shrank was the software and lending sold alongside the terminal, and that is where the margin lives: value-added services fell to 23% of Clover revenue from 26% a year earlier, which is why total Clover revenue grew 1% while its processing line grew 12%.
Earnings week was read as the payments group bottoming. It was not a group event. Two of the six names fell over 30 days, and Fiserv and NCR Voyix supplied 82% of the gain. The three bank-and-merchant processors gave three different answers: Fiserv's organic revenue was flat on a 53.1% gross margin, down 5.8 points; FIS cut 2026 guidance twice over and guided 2027 earnings lower; Jack Henry raised guidance on revenue up 8.8% with operating income up 12.5%. The business that is accelerating is also the most expensive on the group at 23.5x forward earnings.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
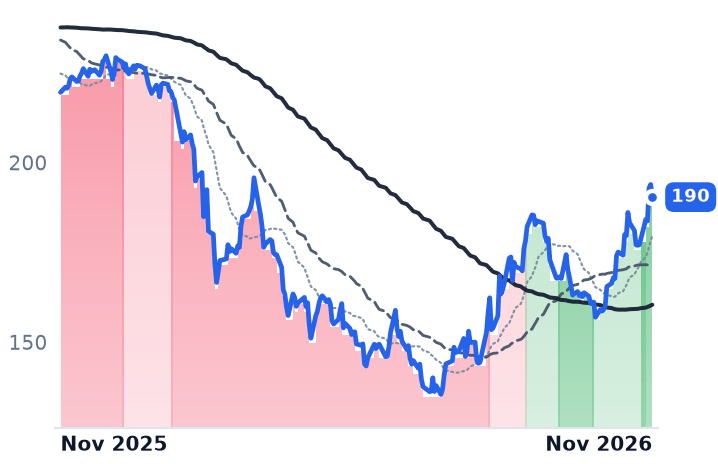
FISV | Fiserv | Fintech Solutions | 🔴 Cont. Bear | +36.9% | −1.3% |
FIS | Fidelity National Information Services | Fintech Solutions | 🔴 Cont. Bear | −16.3% | −55.0% |
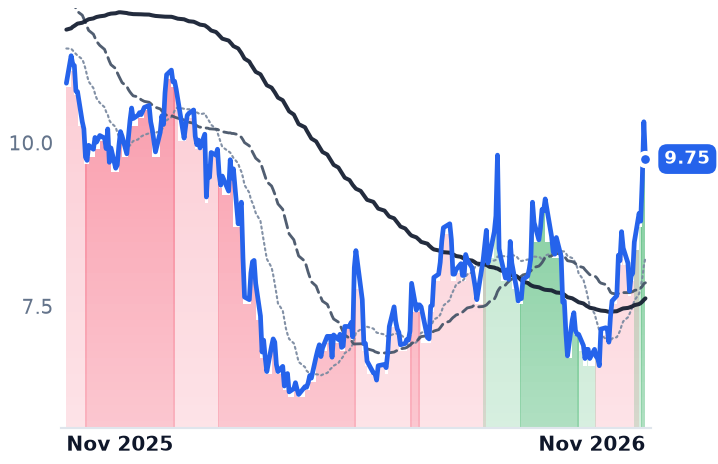
JKHY | Jack Henry & Associates | Fintech Solutions | 🌱 Emerging Bull | +16.2% | +8.5% |
WSE | Wise | Fintech Solutions | 🔴 Cont. Bear | −4.5% | −27.6% |
BR | Broadridge Financial Solutions | Fintech Solutions | 🌱 Emerging Bull | +19.0% | −13.3% |
VYX | NCR Voyix | Fintech Solutions | 🌱 Emerging Bull | +48.0% | −10.6% |
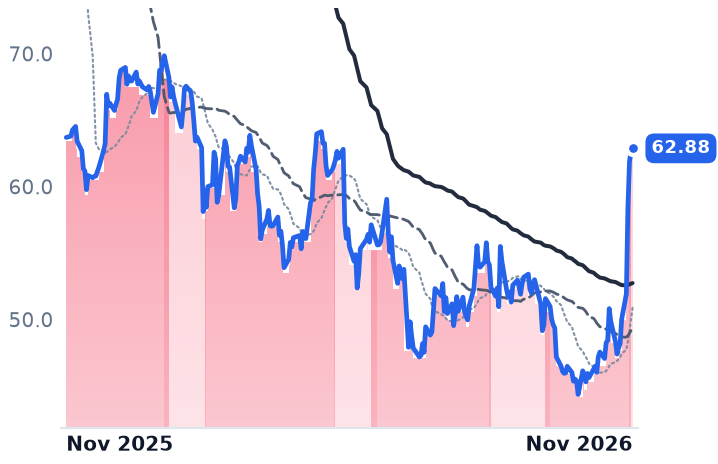
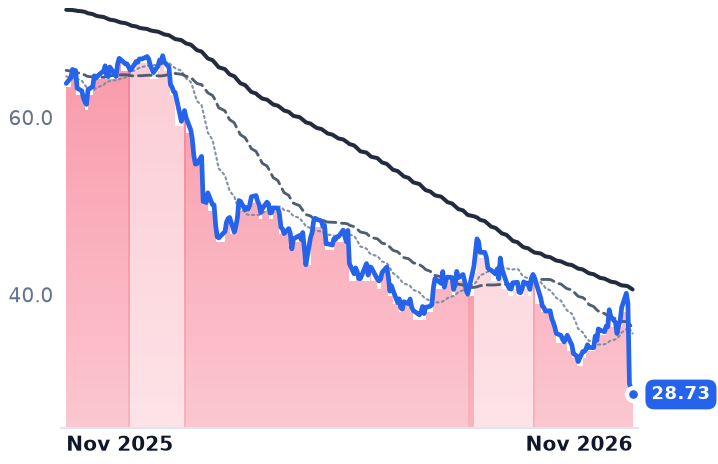
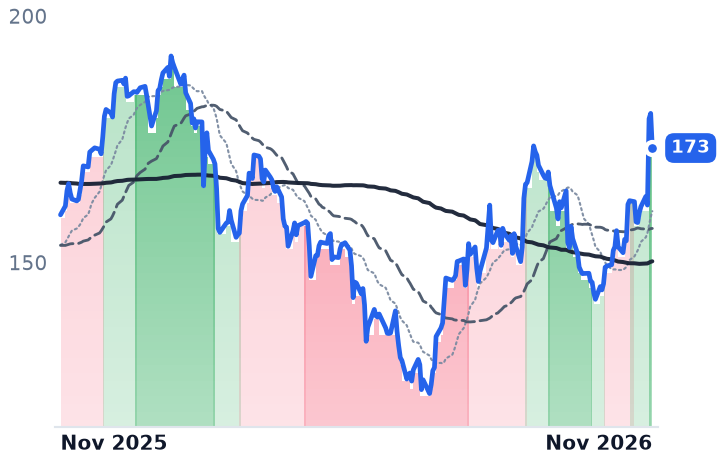
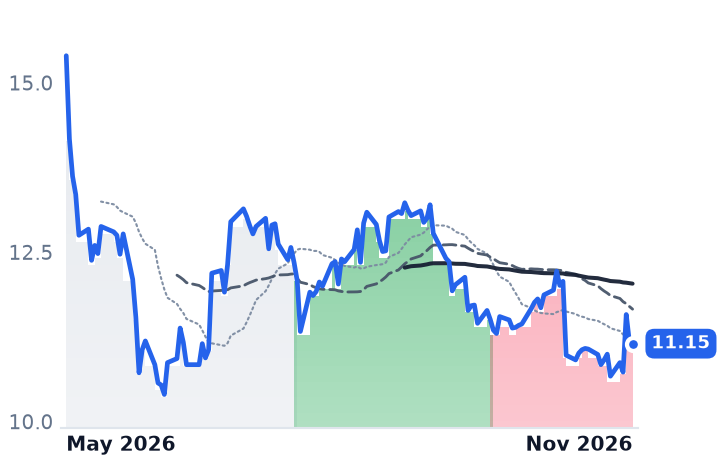
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FISV | $33.4B | n/m | 8.6x | 1.6x | 1.7x | 3.5x | 3.7x | 94.3x | 9.4% |
FIS | $14.8B | 4.3x | 4.6x | 1.1x | 1.1x | 3.2x | 3.0x | 7.4x | 16.2% |
JKHY | $12.1B | 23.8x | 23.5x | 4.7x | 4.5x | 10.7x | 10.3x | 13.8x | 5.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
WSE | $11.2B | 22.7x | 19.7x | 4.0x | 3.7x | 6.9x | 6.5x | n/m | 70.4% |
BR | $21.5B | 20.9x | 18.0x | 2.8x | 2.7x | 9.0x | 8.7x | 13.5x | 6.3% |
VYX | $1.3B | 13.4x | 10.6x | 0.6x | 0.6x | 2.1x | 2.3x | 9.6x | -10.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
FISV | Revenue | −1.4% | +3.3% | +3.5% |
| EPS | −15.0% | +9.2% | +13.1% | |
FIS | Revenue | +28.8% | +4.3% | +3.5% |
| EPS | +7.4% | +7.2% | +10.1% | |
JKHY | Revenue | +7.0% | +6.4% | +7.0% |
| EPS | +12.6% | +7.8% | +9.6% | |
WSE | Revenue | +39.3% | +18.6% | +18.6% |
| EPS | −7.1% | +15.1% | +18.1% | |
BR | Revenue | +8.0% | +5.8% | +4.8% |
| EPS | +12.5% | +10.6% | +9.4% | |
VYX | Revenue | −17.2% | −1.3% | +1.4% |
| EPS | +4.3% | +12.0% | +0.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The swipe held, the software did not
Fiserv's terminals processed more volume last quarter and the company earned almost nothing extra for it. Clover, the point-of-sale system Fiserv sells to roughly 700,000 businesses in eight countries, grew processing revenue 12% on gross payment volume up about 10%, while total Clover revenue grew 1%. The gap is the attach: value-added services, meaning software subscriptions and Clover Capital lending, declined 3% and fell to 23% of Clover revenue from 26%, after growing 18% at 27% of the mix in the first quarter.
The 30-day bounce in this corner of financial technology was read as payments bottoming, a year after investors began marking the sector down on the fear that stablecoin rails would disintermediate card settlement. The November prints point somewhere nearer and duller. The invoice is being reassembled one layer above the rail, by whoever sells the merchant its software, and in bank processing by whoever wins the renewal. Scale at the terminal is not the constraint: Clover's annualized volume of $272bn runs ahead of Square's $220bn and Toast's $135bn, and the same reporting has Clover losing to vertical specialists like Toast among the larger, more attractive small businesses.
Fiserv's group organic revenue was flat, with Merchant Solutions organic revenue down 2% and gross margin of 53.1% against 58.9% a year earlier. A $6.45bn non-cash goodwill impairment, triggered by the sustained decline in its own market capitalization, opened a $12.92 gap between GAAP earnings of -$11.17 a share and the adjusted $1.75. Year-to-date free cash flow conversion is running near 71% against a 90% full-year target. Management reaffirmed 2026 adjusted earnings of $7.20 to $7.40 and doubled its cost program. "We have identified a total of $1 billion in savings opportunities, up from the prior $500 million," chief financial officer Paul Todd told investors on November 3. At $62.88 the shares sit on 8.6x consensus 2026 earnings of $7.27 — the cheapest conventional multiple in the group — but forward price-to-gross-profit of 3.7x sits above the trailing 3.5x, which is the market saying gross profit shrinks from here.
A renewal business, not a price list
FIS, which hosts core processing for more than 90m bank accounts, shows the bank-side version. Reported revenue rose 27.1%, almost all of it the Worldpay and issuer-asset reshuffle; on a pro-forma basis revenue grew 3.7% and recurring revenue 2.5%, with Banking recurring revenue decelerating to 2.4% as fewer than ten large clients pushed contracted go-lives into late 2026 and 2027. Non-recurring revenue grew 22.8% on one-off distribution partnerships. Preliminary 2027 guidance strips that out: banking revenue flat to up 1%, adjusted earnings down high-single to low-double digits. "The massive swing factor is this 250 to 300 basis points on nonrecurring," chief financial officer James Kehoe said on November 4, the day before his departure took effect. "Simplistically, take 3% of 13.5 billion, that is a $400 million change."
Price itself is holding — renewal rates in the high 90s, up 100 basis points, with 72% of issuing revenue contracted through 2029 or beyond. The account base is the problem, shrunk by bank consolidation that paid FIS termination fees on the way out. The shares fell 23.2% on November 4 as J.P. Morgan cut its rating to Neutral and its target to $38 from $53. Against $20.8bn of debt at 3.5x leverage and a suspended buyback, 7.4x trailing EV/EBITDA and 0.91x book are doing rational work; the 16.2% trailing equity free-cash-flow yield compresses to roughly 6% measured on enterprise value.
Jack Henry is winning the renewals it needs
Jack Henry, which sells core platforms and card processing to US banks and credit unions, took revenue up 8.8% with operating income up 12.5% and raised fiscal 2027 guidance to 6.6-7.4% non-GAAP revenue growth. It booked 9 competitive core wins against 4 a year earlier, 63% of them bundling core, digital and card. "A lot of our wins recently have been longtime clients of that particular provider. A couple of them were 28-year clients," chief executive Greg Adelson said on November 4. The buyer's budget is cooperating: the Bank Director 2026 technology survey it cited found 81% of banks raising technology spending, up from 71%, at a median 10% increase. Jack Henry, Fiserv and FIS together serve roughly 70-72% of US banks and are each launching or consolidating platforms rather than cutting price. At 23.5x forward earnings against 7-8% guided earnings growth, it is the dearest name in the group and has no re-rating left in the number.
The one company that discloses what a transaction earns is cutting it deliberately. Wise, the cross-border transfer business, ran a 49 basis point take rate, down 3 basis points year on year, and grew revenue 21% in constant currency on volume of $72bn. "We follow the cost-plus margin logic, and we are in a driving seat," chief financial officer Emmanuel Thomassin said on October 15. Wise raised guidance and its shares still fell 5.6% over the month.
What the move actually bought
So the group average is carried by two names and one week. Excluding Fiserv and NCR Voyix — whose own gain follows a hardware exit that took revenue down 21.2% while lifting gross margin — the other four averaged 4.5%, and Broadridge's contribution rests on a November 2 mandate to supply the governance layer and digital transfer agency for the New York Stock Exchange's planned tokenized equity marketplace, which has nothing to do with payment transactions.
Results account for the whole of Jack Henry's move and the whole of FIS's fall. They do not account for Fiserv's. A 38.8% gain on flat organic revenue, compressing gross margin and conversion below target is buying a fourth quarter in which Merchant organic growth is guided at 6-8%, from minus 2%. Each 1x of 2027 earnings is 12.6% of today's price, so the multiple, not the attach rate, is still what the position depends on.
Fiserv told investors it takes nine to twelve months for better bank retention to show up in revenue. The repricing of its shares took one earnings week.