

Applied Digital's Interest Bill Now Exceeds the Rent Its AI Data Centers Collect
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
A signed hyperscaler lease was supposed to be an annuity. Applied Digital's latest quarter shows the money going out on the debt that built the halls arriving ahead of the money coming in from the tenants: $77.4m of interest against $65.8m of collected base rent, with only 250 of 1,410 contracted megawatts in service.
Cipher Mining put a figure on the other half of the squeeze on its November 2 call — cost per leasable information-technology megawatt at Barber Lake has reached $13m against the $10.4m it underwrote, while the rent on that capacity is fixed for 20 years. HIVE Digital runs a third model, borrowing at 9.0% to own the graphics chips itself.
Applied Digital's reported business is not what fell: revenue rose 322% and adjusted earnings before interest, taxes, depreciation and amortization reached $64.4m from $0.5m. Cipher's and HIVE's numbers did deteriorate.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
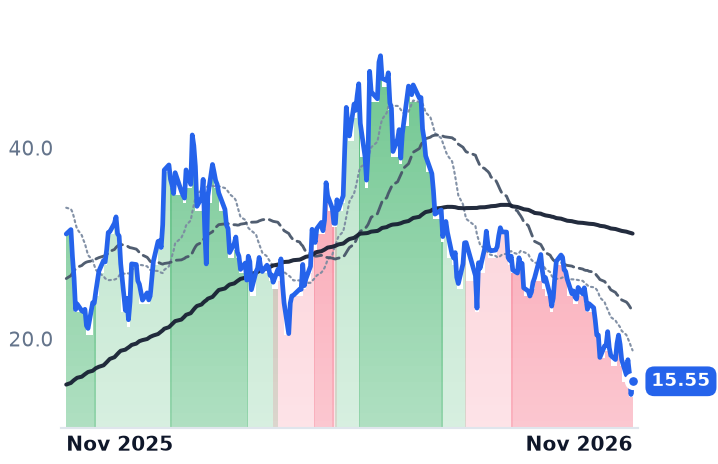
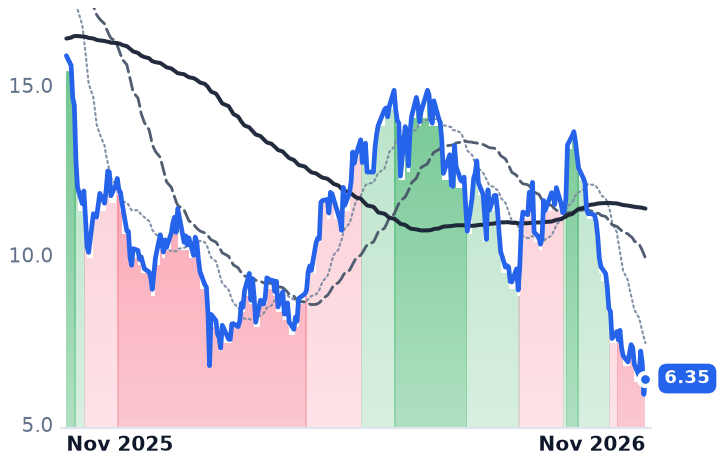
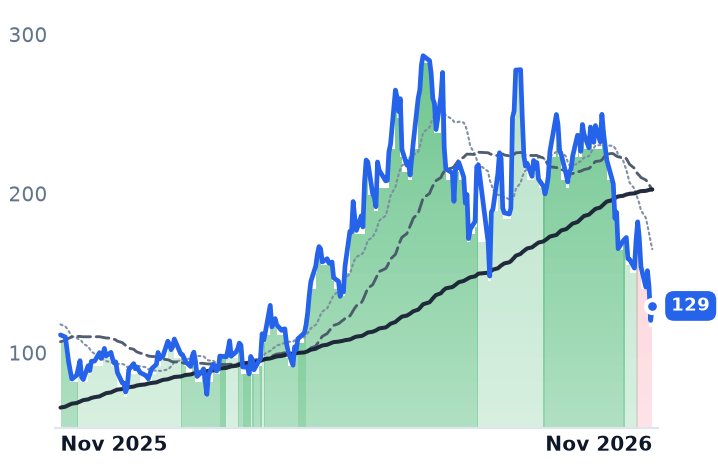
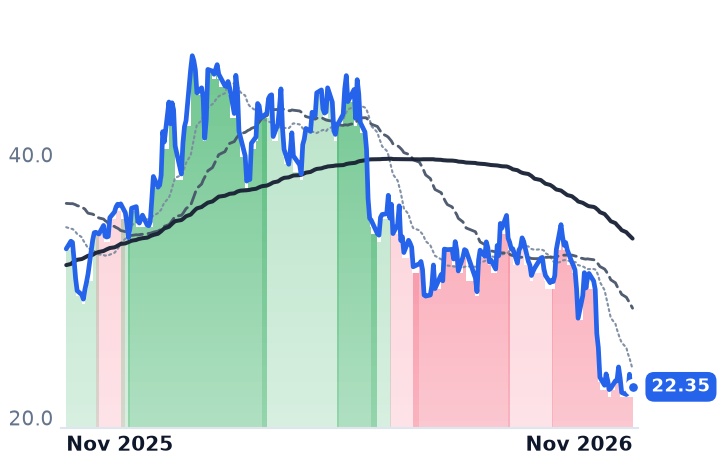
APLD | Applied Digital | Cloud & Computing Infrastructure | 🔴 Cont. Bear | −32.6% | −49.8% |
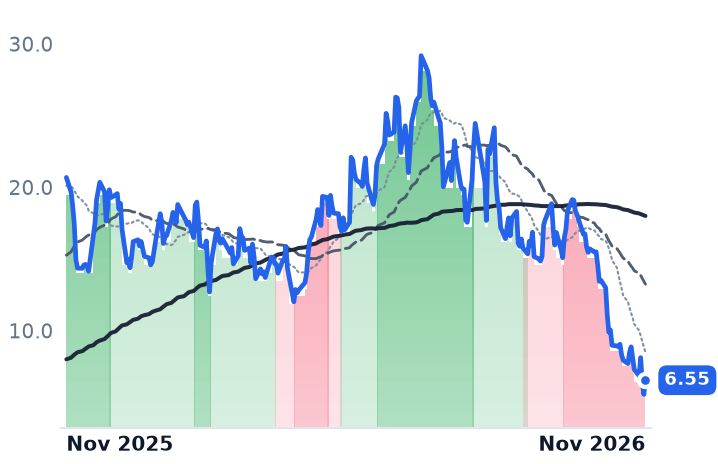
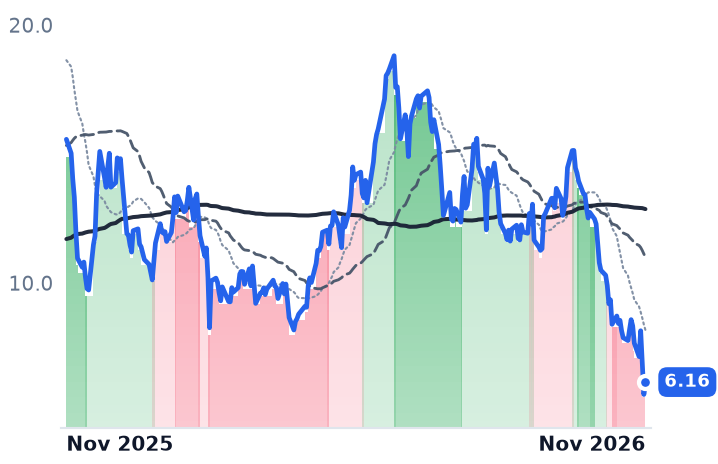
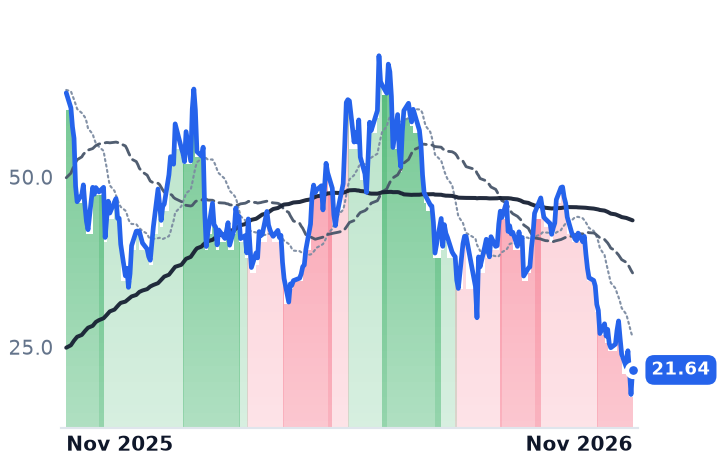
CIFR | Cipher Mining | Cloud & Computing Infrastructure | ⚠️ Emerging Bear | −51.3% | −68.4% |
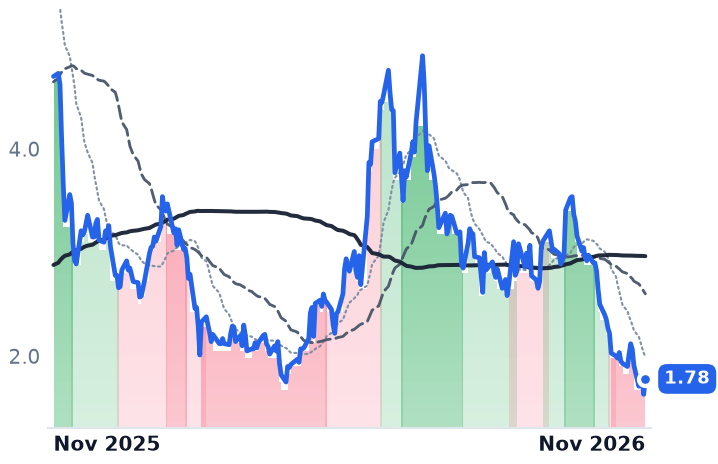
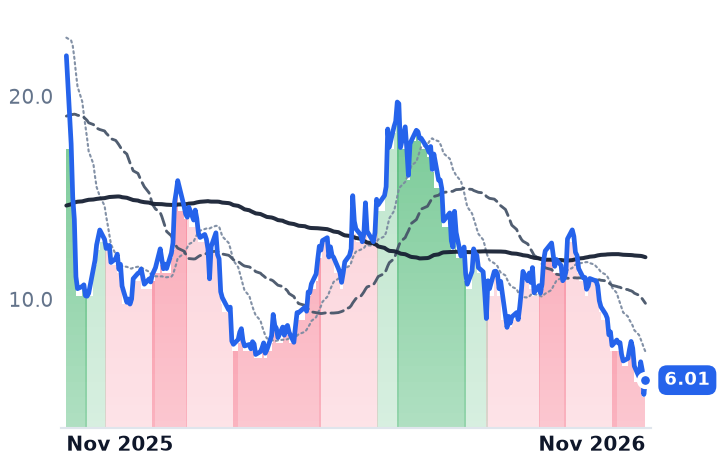
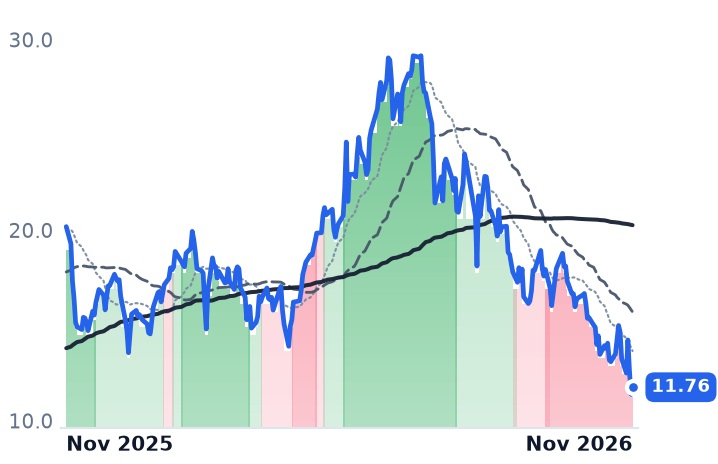
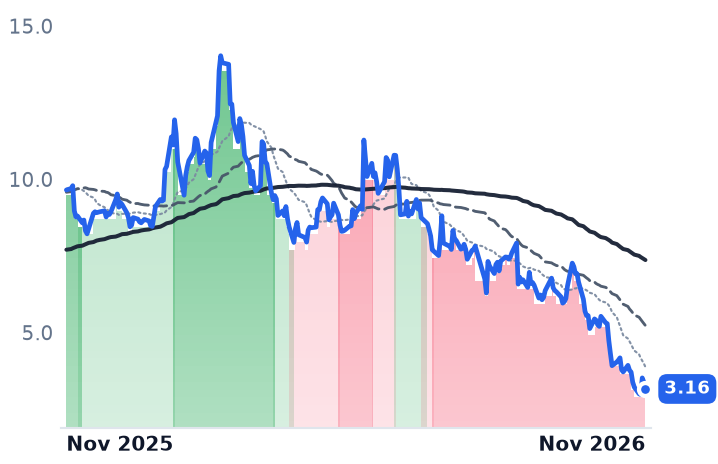
HIVE | HIVE Digital Technologies | Cloud & Computing Infrastructure | 🔴 Cont. Bear | −32.6% | −62.1% |
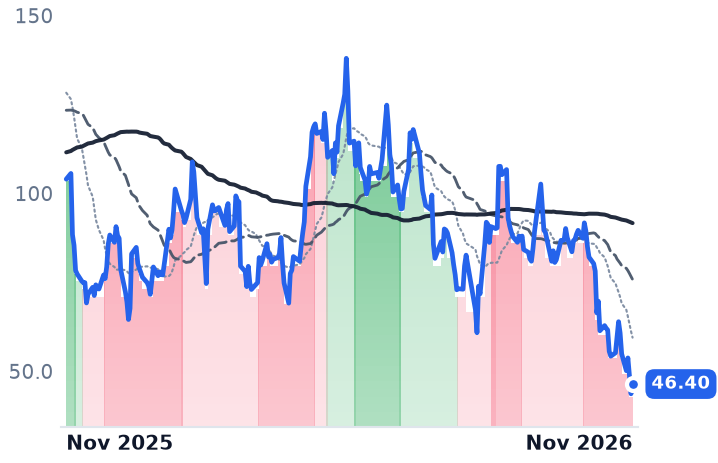
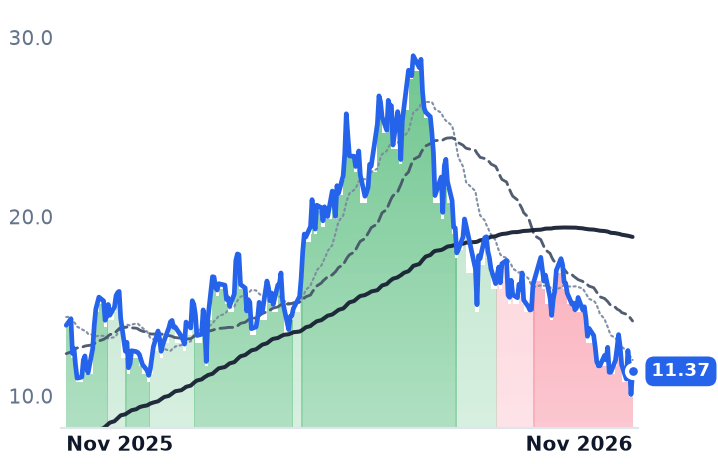
GDS | GDS | Cloud & Computing Infrastructure | 🔴 Cont. Bear | −27.0% | −31.9% |
VNET | VNET | Cloud & Computing Infrastructure | 🔴 Cont. Bear | −39.2% | −67.3% |
| Compared against · context, not the story | |||||
RIOT | Riot Platforms | Bitcoin Mining | 🟢 Cont. Bull | −1.5% | −1.8% |
MARA | Marathon Digital | Bitcoin Mining | 🔴 Cont. Bear | −35.9% | −60.0% |
CLSK | CleanSpark | Bitcoin Mining | 🔴 Cont. Bear | −42.9% | −60.4% |
BTDR | Bitdeer Technologies | Security, Compliance & Emerging Tech | 🔴 Cont. Bear | −39.4% | −72.6% |
CRWV | CoreWeave | Cloud Compute & Infrastructure | 🔴 Cont. Bear | −45.4% | −55.4% |
NBIS | Nebius | Software Development & Design | 🟢 Cont. Bull | −43.6% | +16.4% |
IREN | IREN | Software - Services | 🔴 Cont. Bear | −40.9% | −65.3% |
CORZ | Core Scientific | Vertical Industry Software | ⚠️ Emerging Bear | −23.5% | −41.8% |
WULF | TeraWulf | Bitcoin Mining | ⚠️ Emerging Bear | −14.7% | −18.4% |
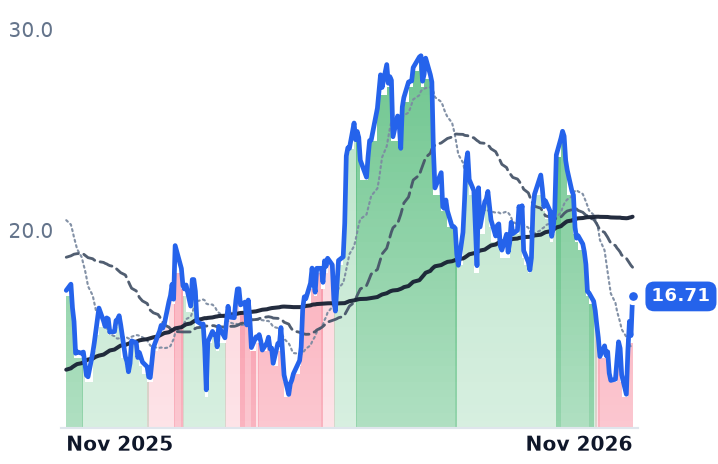
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
APLD | $4.7B | n/m | — | 5.5x | 4.9x | 27.2x | 24.3x | n/m | -94.8% |
CIFR | $3.0B | n/m | — | 20.4x | 16.8x | — | — | n/m | -103.3% |
HIVE | $488.2M | n/m | — | 1.5x | 1.4x | — | — | 73.2x | -25.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
RIOT | $7.7B | n/m | — | 11.3x | 11.7x | — | — | n/m | -11.5% |
MARA | $3.7B | n/m | — | 4.6x | 4.3x | — | — | n/m | -42.4% |
CLSK | $2.4B | n/m | — | 3.5x | 3.8x | — | — | n/m | -48.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BTDR | $1.9B | n/m | — | 2.3x | 2.0x | 485.6x | 417.0x | n/m | -112.6% |
CRWV | $35.3B | n/m | — | 4.6x | 2.8x | 6.9x | 4.1x | 20.4x | -38.7% |
NBIS | $41.3B | 661.5x | — | 30.5x | 12.3x | 41.0x | 16.6x | 43.1x | -14.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
IREN | $11.7B | n/m | — | 16.5x | 4.3x | 23.9x | 6.2x | 392.4x | -17.1% |
CORZ | $4.2B | n/m | — | 9.6x | 6.2x | 34.1x | 22.0x | n/m | -22.8% |
WULF | $6.7B | n/m | — | 40.5x | 25.7x | 58.5x | 37.1x | n/m | -37.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GDS | $4.4B | 7.7x | — | 2.3x | — | 9.4x | — | 11.0x | -2.8% |
VNET | $883.4M | n/m | — | 0.6x | — | 2.7x | — | 7.9x | -95.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
APLD | Revenue | +98.7% | +124.3% | +102.9% |
| EPS | −24.3% | +125.1% | −41.3% | |
CIFR | Revenue | −28.9% | +352.0% | +29.8% |
| EPS | +231.7% | −66.2% | −74.0% | |
HIVE | Revenue | +163.7% | +17.3% | +45.9% |
| EPS | +258.3% | +74.5% | −64.9% | |
RIOT | Revenue | +0.1% | +20.6% | +15.0% |
| EPS | +453.3% | −59.3% | −36.7% | |
MARA | Revenue | −11.4% | +20.3% | −23.2% |
| EPS | +227.3% | −65.4% | −244.5% | |
CLSK | Revenue | −22.8% | +5.3% | +15.2% |
| EPS | −364.6% | −55.0% | −38.7% | |
BTDR | Revenue | +57.6% | +74.6% | −10.7% |
| EPS | +260.8% | −72.8% | +195.7% | |
CRWV | Revenue | +150.7% | +106.7% | +61.6% |
| EPS | +208.9% | −49.2% | −141.7% | |
NBIS | Revenue | +508.0% | +260.2% | +88.0% |
| EPS | +65.5% | +69.1% | −94.1% | |
IREN | Revenue | +37.5% | +286.9% | +168.1% |
| EPS | −1022.8% | +177.0% | −97.4% | |
CORZ | Revenue | +90.2% | +66.6% | +45.1% |
| EPS | +154.1% | −104.9% | +175.5% | |
WULF | Revenue | +46.7% | +228.6% | +96.7% |
| EPS | +121.0% | −91.1% | −207.7% | |
GDS | Revenue | +12.5% | +8.7% | +23.1% |
| EPS | −58.7% | −103.9% | −736.0% | |
VNET | Revenue | +18.9% | +21.1% | +22.6% |
| EPS | −4.0% | −170.9% | +28.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Applied Digital, which builds data-center shells and leases them to artificial-intelligence computing tenants, spent more servicing its debt last quarter than it collected in rent. Interest expense reached $77.4m in the three months to August 31, up from $8.0m a year earlier, against $65.8m of base rent. Group revenue more than quadrupled to $341.9m, but $183.5m of that was low-margin tenant fit-out construction, which is why reported gross margin fell to 15.3% from 42.5% two quarters earlier.
That inversion is what the signed-lease story leaves out. Fifteen-year leases with creditworthy tenants have been read as annuities — megawatts contracted, rent fixed at signing, financing a detail of the plumbing. The sequence actually runs the other way: interest accrues from the day capital is drawn, rent starts only when a hall is energized, and just 250 of Applied Digital's 1,410 contracted megawatts were in service at the quarter's close.
The window between the draw and the rent is about to widen
"Over the next 12 months, we expect to place over 600 megawatts into service versus 250 megawatts over the past 12 months," chairman and chief executive Wes Cummins told investors on October 7. At the company's guided capex of $11m to $13m per megawatt, that step-up has to be funded before a dollar of it bills. It is being funded off the common equity line: $562.5m drawn from Macquarie Asset Management under a preferred-equity facility of up to $5.0bn, with a further $337.5m after quarter end, alongside $1.59bn of project notes placed at 7%. "Our first Polaris Forge 1 related notes placed last year carry a 9.25% coupon. This tranche priced at 7%," chief financial officer Mohammad Saidal L. Mohmand said on the same call, crediting anchor tenant CoreWeave's credit quality.
CoreWeave's own 2032 bond has since yielded above 16%, and convertibles, the channel these developers lean on, had their worst October since 2008 at -6.4%. The repricing of data-center risk after the midterms, already visible in power equipment, lands here as a cost of future capital.
Cipher had to buy its yield back
Cipher Mining, a bitcoin miner converting its powered Texas sites into leased AI capacity, disclosed on November 2 that cost per leasable information-technology megawatt at Barber Lake has risen to $13m from the $10.4m it originally underwrote, after $409m of tenant change orders — and that it put in additional capital to restore yield on cost to roughly 15% from the 13% the project would otherwise have earned. The rent is not movable: the lease was extended to a 20-year base term and about $9.1bn of contracted revenue. Of $6.7bn of debt, $4.5bn is non-recourse at the project level, and management says every contracted project is funded through completion. "We are not a neocloud," chief executive Tyler Page said. "Lenders and investors are placing a premium on predictable, contracted cash flows." Reported revenue fell 62.8% to $26.7m because mining was switched off at Black Pearl to hand the building over.
HIVE owns the chips the landlords refuse to buy
HIVE Digital Technologies, a miner that also sells graphics-processor cloud capacity, has $600m of contracted off-take but borrowed about $129m at a 9.0% fixed rate at 80% loan-to-cost to buy a $165m cluster itself. Revenue grew 69.1% to $77.1m at a gross margin of -37.3%, growth having decelerated from 285% four quarters earlier, and diluted shares rose 38.1%.
How much of the fall the numbers justify
For two of the three, they do. Cipher trades at 20.4x trailing sales on revenue that is falling by design; the bull anchor is an enterprise value near $6bn against roughly $864m of projected average annualized net operating income, derived from its own disclosures. HIVE's 1.12x book is a book of depreciating hardware earning a negative margin.
Applied Digital is the odd one. Revenue rose 322%, adjusted earnings before interest, taxes, depreciation and amortization went from $0.5m to $64.4m, and its project coupon tightened 225 basis points, while the shares fell 32.6% over the 21 sessions to November 6. At 27.2x trailing gross profit against 60.74x in late August, the decline has finally done the valuation work a 43% fall three months ago did not. The single line that genuinely deteriorated is the financing line, and it is the one that decides whether the next 600 megawatts earn their rent.
The nearest dated test belongs to the smallest of them: HIVE reports on November 9, with the call the following morning. It is the one company here whose hardware, not its landlord's balance sheet, has to hold its value.