

Reactor Developers Collect Nothing on an Order; GE Vernova Collects a Fifth Up Front
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Five companies are priced off reactor orders and only one of them sends invoices. GE Vernova's Nuclear Power business billed $719m of a $12.642bn September quarter, under 6% of revenue, and the company discloses no separate nuclear backlog. What the market marked down after the midterm vote was the gas and grid order book, where customer deposits of $5.3bn made up almost all of the quarter's free cash flow, arriving years before equipment ships.
The four developers have no such line. NuScale billed $281,000 in its September quarter and now trades at 1.02 times book; Oklo, X-energy and NANO Nuclear sit at or near the cash they raised, while their construction and licensing schedules held. The gigawatts in a developer's pipeline pay nothing until construction starts, and the premium that priced them has gone.
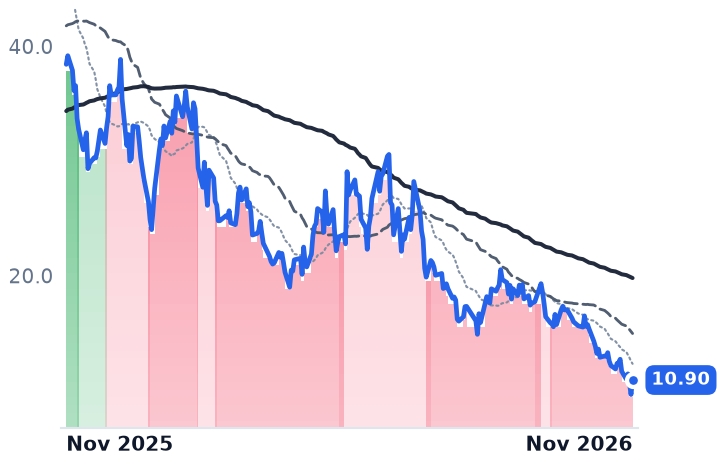
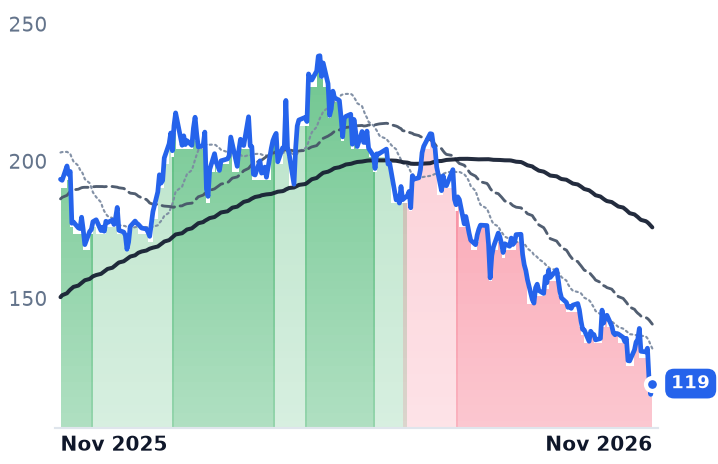
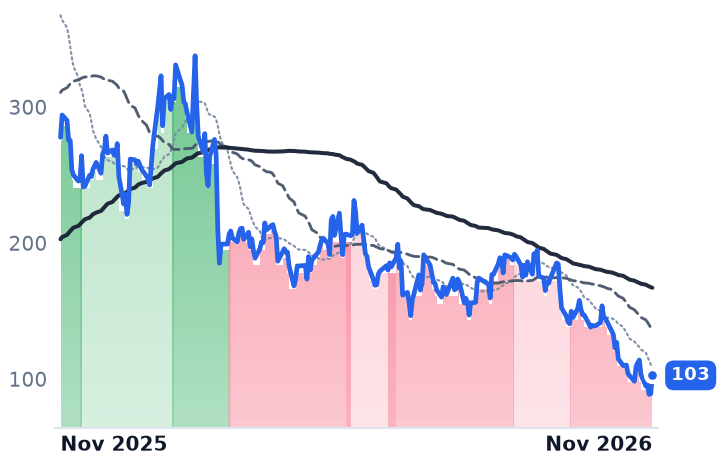
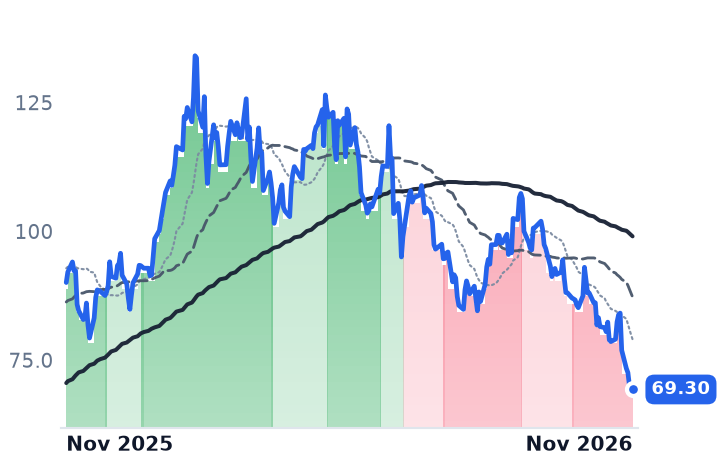
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
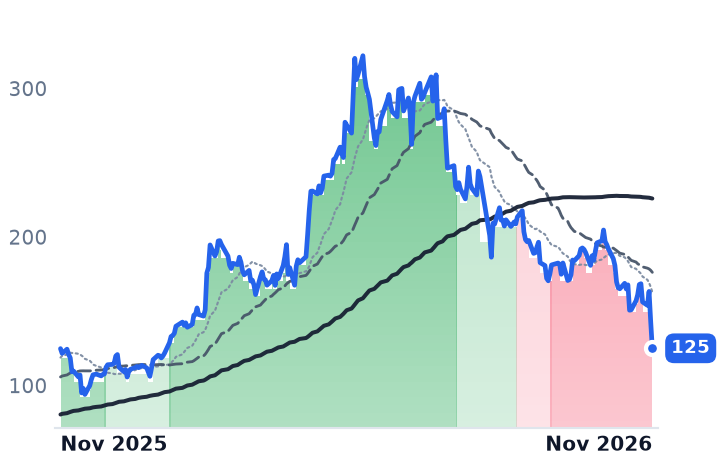
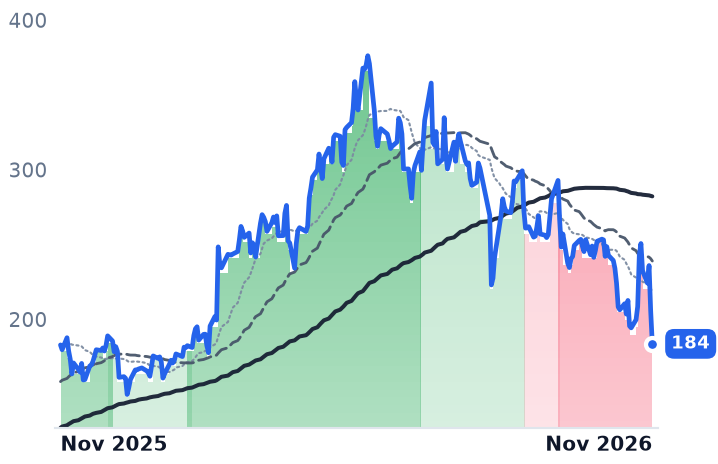
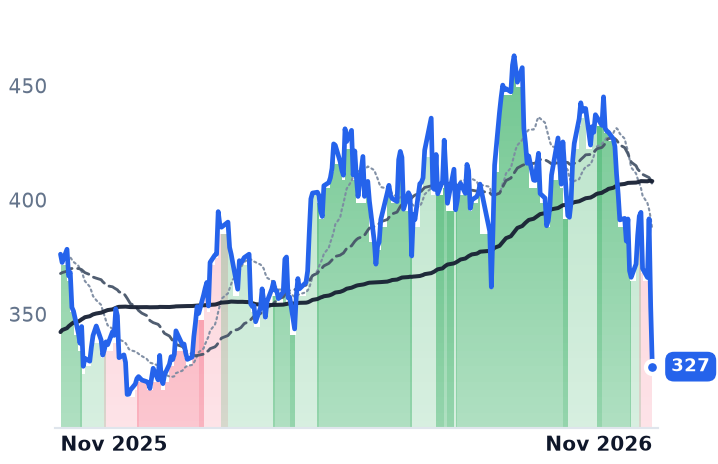
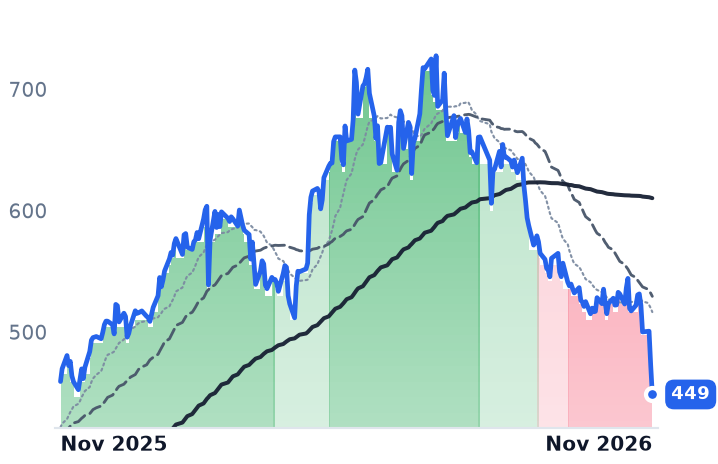
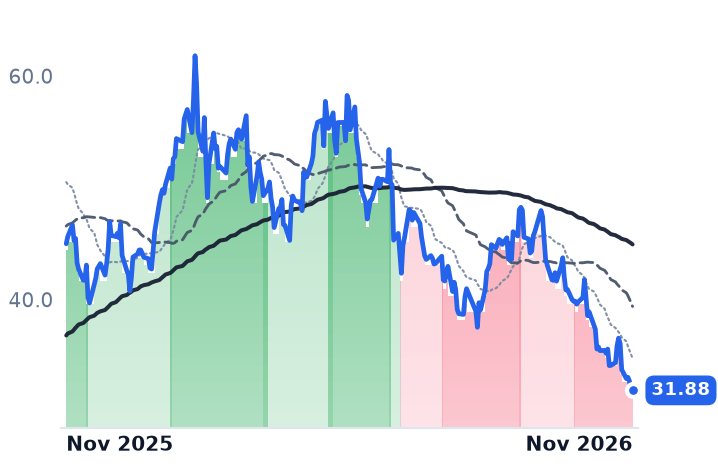
GEV | GE Vernova | Power Generation & Propulsion | ⚠️ Emerging Bear | −21.4% | +42.3% |
XE | X-Energy | Power & Propulsion Systems | 🔴 Cont. Bear | −31.3% | −66.4% |
OKLO | Oklo | Advanced Nuclear | 🔴 Cont. Bear | −37.8% | −78.7% |
SMR | NuScale Power | Advanced Power Systems | 🔴 Cont. Bear | −34.6% | −84.9% |
NNE | Nano Nuclear Energy | Advanced Power Systems | 🔴 Cont. Bear | −30.0% | −71.6% |
BWXT | BWX Technologies | Aerospace Components & Propulsion | 🔴 Cont. Bear | −15.6% | −38.5% |
LEU | Centrus Energy | Uranium | 🔴 Cont. Bear | −29.3% | −63.0% |
CCJ | Cameco | Uranium | 🔴 Cont. Bear | −23.5% | −23.1% |
POWL | Powell Industries | Power Distribution Systems | ⚠️ Emerging Bear | −36.5% | +0.2% |
VRT | Vertiv | Advanced Power Systems | ⚠️ Emerging Bear | −24.2% | +0.4% |
ETN | Eaton | Power Distribution Systems | 🟢 Cont. Bull | −24.2% | −13.1% |
CMI | Cummins | Power Generation & Propulsion | ⚠️ Emerging Bear | −14.5% | −2.3% |
NRG | NRG Energy | Retail-Focused Operators | 🔴 Cont. Bear | −20.6% | −52.5% |
CEG | Constellation Energy | Wholesale Generators | 🔴 Cont. Bear | −20.0% | −31.6% |
PWR | Quanta Services | Power Grid & Distribution | ⚠️ Emerging Bear | −27.9% | +15.0% |
BE | Bloom Energy | Fuel Cell & Hydrogen | 🟢 Cont. Bull | −42.2% | +22.4% |
URA | Global X - Uranium ETF | Asset Management | 🔴 Cont. Bear | −20.5% | −29.1% |
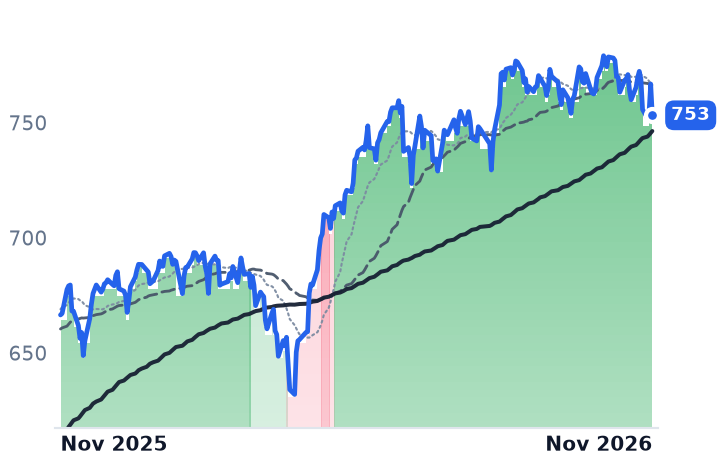
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −4.9% | +10.8% |
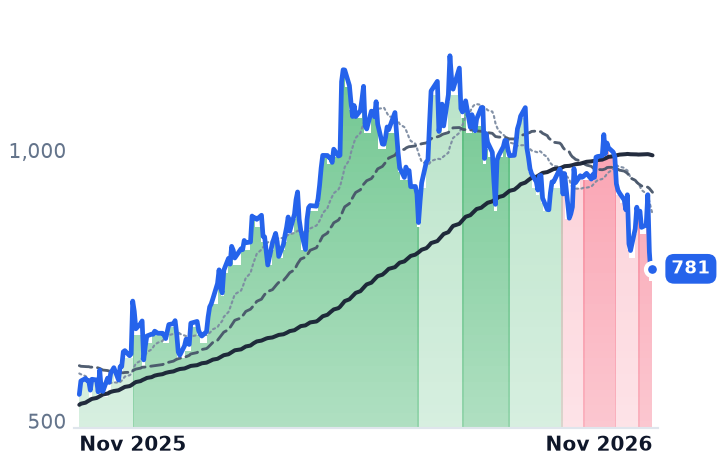
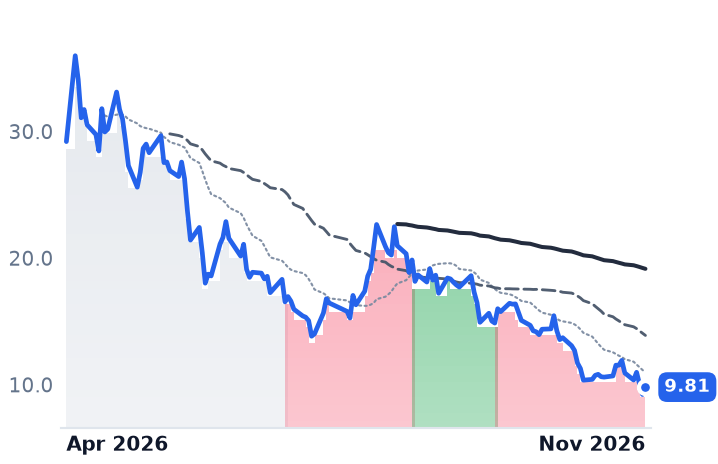
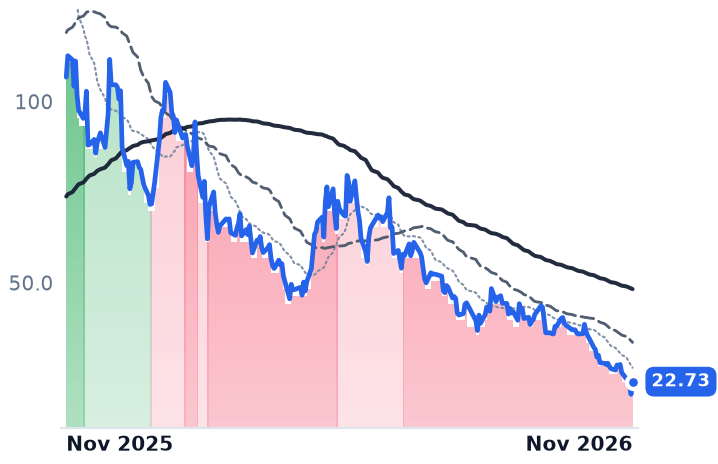
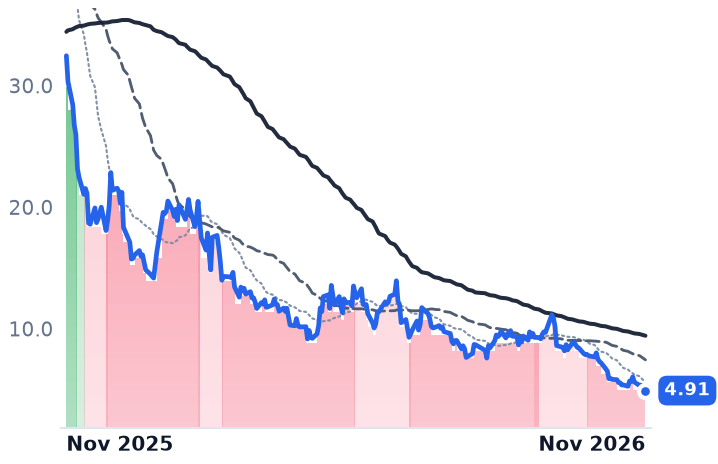
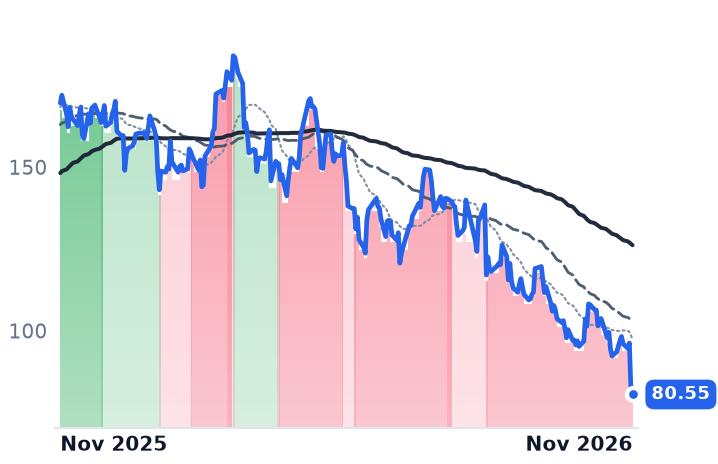
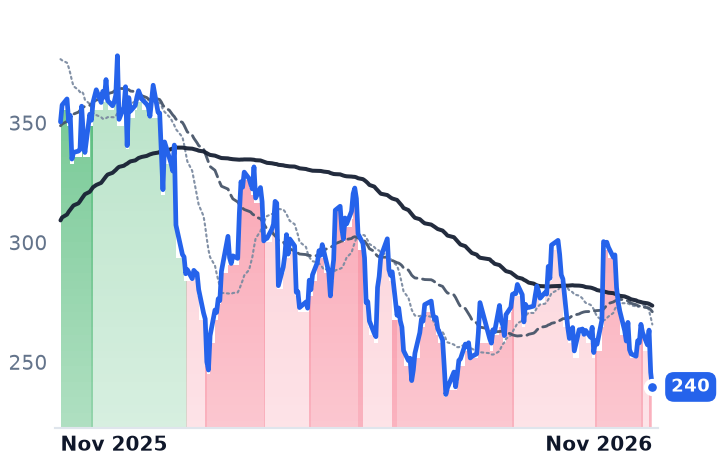
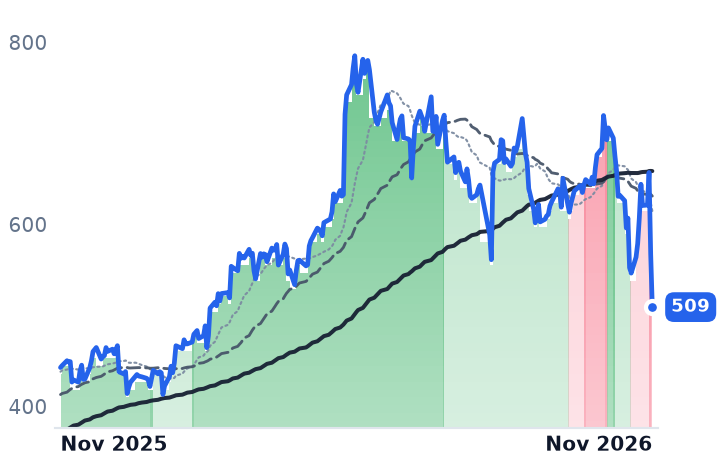
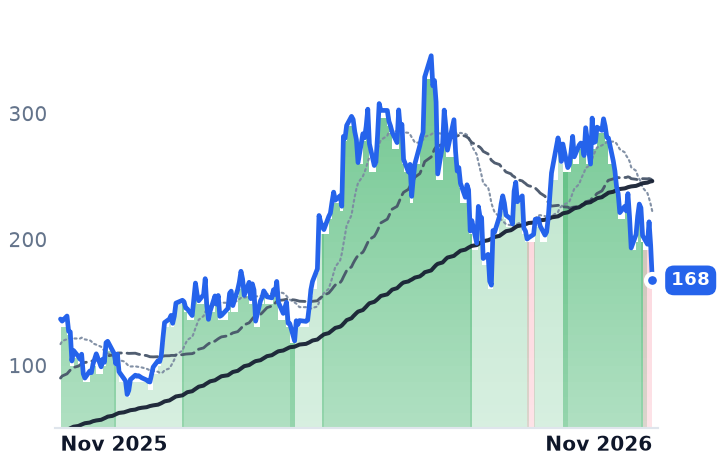
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GEV | $206.8B | 20.3x | 24.7x | 4.7x | 4.4x | 21.6x | 20.3x | 18.6x | 8.3% |
XE | $219.8M | n/m | — | 1.5x | 1.0x | — | — | 3.2x | -186.5% |
OKLO | $4.4B | n/m | — | — | — | — | — | n/m | -10.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SMR | $1.5B | n/m | — | 549.6x | 88.6x | — | — | n/m | -40.4% |
NNE | $585.0M | n/m | — | — | 78.6x | — | 270.4x | n/m | -6.7% |
BWXT | $12.0B | 33.7x | 27.6x | 3.4x | 3.1x | 15.4x | 14.3x | 24.2x | 2.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LEU | $2.0B | 26.9x | 42.9x | 4.5x | 4.2x | 19.6x | 18.6x | 8.9x | -14.5% |
CCJ | $30.1B | 106.4x | 52.1x | 12.2x | 8.6x | 51.3x | 36.1x | 48.8x | 0.7% |
POWL | $5.9B | 30.7x | 23.4x | 5.1x | 3.9x | 16.9x | 13.0x | 21.1x | 4.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VRT | $97.1B | 55.8x | 37.5x | 8.5x | 6.9x | 22.2x | 18.2x | 38.2x | 3.0% |
ETN | $149.2B | 39.0x | 28.2x | 5.0x | 4.5x | 13.8x | 12.6x | 26.3x | 3.0% |
CMI | $72.2B | 26.6x | 17.7x | 2.1x | 1.9x | 8.2x | 7.6x | 15.5x | 4.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NRG | $21.2B | — | 11.3x | — | 0.6x | — | — | 10.5x | 1.6% |
CEG | $107.0B | 29.0x | 24.7x | 3.5x | 3.2x | 20.0x | 18.4x | 15.8x | 0.3% |
PWR | $82.2B | 61.8x | 32.6x | 2.5x | 2.1x | 17.4x | 14.4x | 28.5x | 2.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BE | $60.0B | 113.9x | 64.1x | 15.7x | 13.5x | 48.5x | 41.8x | 97.9x | 0.7% |
URA | $3.2B | — | — | — | — | — | — | — | — |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
GEV | Revenue | +25.7% | +14.1% | +15.7% |
| EPS | +334.6% | −18.6% | +38.8% | |
XE | Revenue | +81.4% | +289.0% | +42.5% |
| EPS | −96.6% | −38.4% | −29.6% | |
OKLO | Revenue | — | +231.0% | +435.4% |
| EPS | +62.4% | +8.3% | +11.3% | |
SMR | Revenue | −59.6% | +507.1% | +271.3% |
| EPS | −77.1% | +14.4% | −16.3% | |
NNE | Revenue | +2627.0% | +309.5% | +1056.5% |
| EPS | −31.4% | +54.0% | +18.7% | |
BWXT | Revenue | +20.7% | +8.9% | +9.7% |
| EPS | +24.1% | +10.5% | +13.9% | |
LEU | Revenue | +6.9% | +4.5% | −5.5% |
| EPS | −46.4% | +46.7% | −12.2% | |
CCJ | Revenue | +2.4% | +12.8% | +8.8% |
| EPS | −7.5% | +88.3% | +27.3% | |
POWL | Revenue | +8.8% | +25.8% | +14.4% |
| EPS | +12.1% | +27.8% | +19.8% | |
VRT | Revenue | +37.1% | +30.2% | +21.3% |
| EPS | +62.9% | +36.7% | +26.4% | |
ETN | Revenue | +20.2% | +11.4% | +9.9% |
| EPS | +12.8% | +19.7% | +17.0% | |
CMI | Revenue | +13.1% | +9.4% | +8.5% |
| EPS | +29.6% | +17.1% | +16.5% | |
NRG | Revenue | +17.7% | +0.8% | +3.7% |
| EPS | +14.0% | +24.5% | +15.8% | |
CEG | Revenue | +37.2% | +2.5% | +5.3% |
| EPS | +28.9% | +10.4% | +26.4% | |
PWR | Revenue | +41.1% | +16.3% | +14.1% |
| EPS | +57.7% | +17.9% | +18.3% | |
BE | Revenue | +133.1% | +61.9% | +46.1% |
| EPS | +474.5% | +68.3% | +61.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
GE Vernova collected $5.3bn of customer deposits in the September quarter, money wired years before a gas turbine ships, and that single line is why it is the only one of the five companies sold as nuclear reactor builders whose markdown can be argued against an income statement. The deposits and slot reservations were $5.3bn of the quarter's $5.4bn of free cash flow. Its Nuclear Power business, meanwhile, billed $719m of a $12.642bn quarter, under 6% of revenue, and the company discloses no separate nuclear backlog.
So the thing repriced in GE Vernova after the 3 November midterm vote was the gas and grid book, where the revenue and the cash sit, on a political read that state ballot measures and gubernatorial shifts could delay permitting and interconnection for data centers. The belief worth testing across the other four is that a contracted gigawatt of reactor capacity pays its developer something before construction begins. It pays nothing. A firm gigawatt of GE Vernova gas equipment carries roughly $850m of booked revenue; a gigawatt in Oklo's, NuScale's or X-energy's pipeline carries a filing and a schedule.
Twenty percent down before the steel is cut
Gas equipment backlog plus slot reservations reached 122 GW from 116 GW in the quarter, as 13 GW of reservations converted to firm orders and 5 GW shipped: firm backlog rose from 53 GW to 64 GW, reservations fell to 58 GW. Set that against $54.4bn of Power equipment backlog and a firm gigawatt works out at about $850m of equipment revenue, a figure derived from the two disclosures. Services follow it. HA is the company's advanced-class turbine line, and "we expect every gigawatt of HAs to generate $0.5 billion of high-margin services revenue over the first 20 years of its lifetime," chief executive Scott Strazik told investors on 28 October. A reservation earns the label slot reservation agreement only once the customer has put down roughly a fifth of the price in cash, which is both the cash-timing mechanism and the screen against speculative bookings.
That is why the cash guide moved hardest: free-cash-flow guidance went to $16–17bn from $11.5–12.5bn, a raise that tracks the down-payment inflow. Orders rose 96% to $29.3bn and backlog reached about $197bn, split $104bn equipment and $93bn services. Revenue growth has accelerated for three consecutive quarters, to 26.8%, with gross margin 554 basis points wider year on year.
The shares fell through all of it. At $781.24 GE Vernova is 33.5% below its 52-week high, and price-to-sales is 4.69 against 7.47 in May; on the FY2027 consensus estimate of $25.75 a share the multiple is about 30x, against roughly 37x forward in May. The trailing 20.3x is flattered by the gain on Prolec GE and overstates the earnings base. Among the power-equipment makers the markdown was mild: down 21.9% over three months while Powell fell 39.7% and Vertiv 33.3%, and in the week to 3 November GE Vernova lost 11% as Vertiv lost 14%.
What $300m a gigawatt buys without a permit
X-energy, which licenses the Xe-100 reactor and makes TRISO fuel, booked $54.6m of revenue in the June quarter at a gross margin of minus 59.9%, because the revenue is Department of Energy cost-share development work. It holds $1,145.4m of cash and describes $1.9bn of liquidity with no debt, and spent $63.3m of capital in the quarter, mostly on the TX-1 fuel plant at Oak Ridge, about 80% complete and on schedule. Its pipeline is 144 reactors, roughly 11.5 GWe, assuming every customer exercises its contingent rights in full, with Amazon and affiliated projects more than 70% of contracted backlog. On 406.4m shares outstanding the market value is near $4.0bn and on the lower count implied by its May record about $2.7bn, so $233m to $347m per pipeline gigawatt, derived. "We are focused on that $2.3 trillion TAM that we can access with the Xe-100 and our TRISO fuel business," chief executive J. Clay Sell said on the second-quarter call.
Oklo, which builds the 15–75 MWe Aurora powerhouse, billed $1.861m of radioisotopes against an operating loss of $82.4m, and ended September with $3.13bn of liquidity after issuing 32.6m shares for $2.25bn; diluted shares are up 25% in a year. Its 14 GW pipeline is a 12 GW master power agreement with Switch to 2044, up to 1.2 GW at a Meta campus still in interconnection and a 500 MW Equinix letter of intent carrying a $25m prepayment — about $302m a gigawatt against $4.23bn of market value, and 1.21 times book.
NuScale billed $281,000 as RoPower engineering work wound down, down 96.6% year on year, and now carries $1.9bn of liquidity against roughly $1.47bn of Class A market value, 1.02 times book, with quarterly operating expenses near $65m. Its 6 GW framework with the Tennessee Valley Authority and commercialisation partner ENTRA1 is a memorandum: about $244m a framework gigawatt, derived, and the power purchase agreement behind it is unsigned. "We are no longer simply designing and planning, we are manufacturing," chief executive John Hopkins said on 5 November, citing the Doosan Enerbility first-article module agreement.
NANO Nuclear has no gigawatts to divide into. It reported $214,042 of revenue in the June quarter, the first in its history, against a $15.83m operating loss, holds about $580m of cash and short-term investments against $585m of market value, and trades at 0.93 times book, the only one of the five below its own balance sheet. It has one construction permit application accepted for review, with first power around 2030.
Two markdowns, two causes
Nothing in GE Vernova's results explains its markdown: every line improved and the cash guide rose. What is at risk is conversion, 58 GW of reservations whose customers can still walk, and that risk is political rather than operational. For the four developers the results cannot explain anything, because there is almost nothing to bill; what was erased is the premium over cash, while the schedules held and the Nuclear Regulatory Commission issued the first US construction permit for the BWRX-300 at Clinch River on 28 September. Three designs now clear between $244m and $347m a gigawatt of uncommitted capacity, and on 6 November Oklo rose 19% on a narrower loss, NuScale 15% and NANO Nuclear 9% as the policy fear passed, which is roughly what a balance sheet does for a share price when the story stops working.
X-energy reports its September quarter on 12 November. It will be the first look at what a quarter of fuel-plant construction costs now that the equity is worth little more than the money paying for it, and the first developer disclosure since the autumn took the option premium away.