

FormFactor, MKS and Cohu All Raised Forecasts in the Month Their Shares Fell a Third
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Three suppliers to the back end of chipmaking reported between 28 October and 5 November 2026, and each one beat its own guidance and raised the next number. Each is also worth about a third less than on 7 October, and roughly half its 2026 high.
FormFactor's September-quarter revenue grew 38.4% with gross margin at 54.7% against 39.7% a year earlier; MKS grew 43% with its semiconductor segment up 54%; Cohu's bookings rose 126% and customer test-cell utilization reached 82%. Nothing in those disclosures accounts for the markdown, which tracked the whole semi-cap complex.
The three do not sit on the same footing. MKS is the cheapest at 14.2x forward earnings against 21.0x trailing. Cohu, at 34.7x forward, is dearer than before the fall, because its earnings base is barely off zero.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
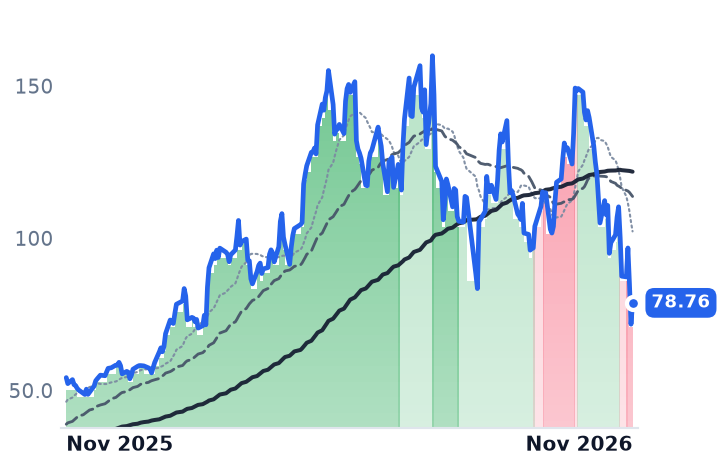
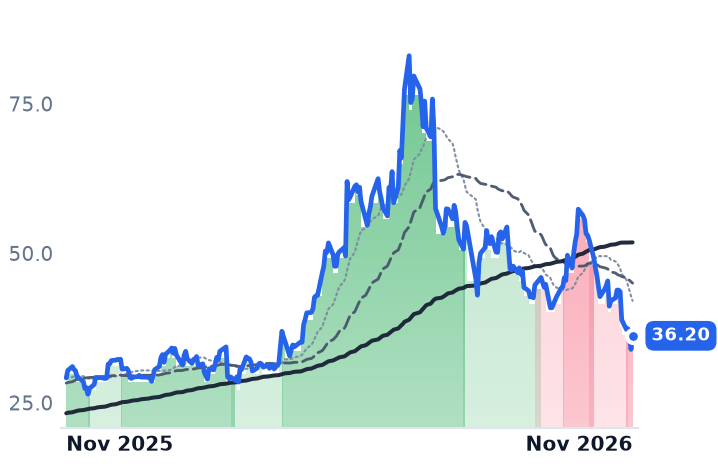
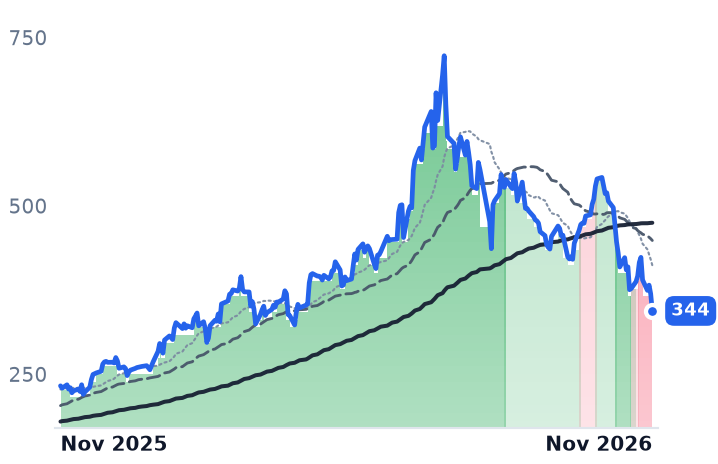
FORM | FormFactor | Test & Assembly Services | ⚠️ Emerging Bear | −43.3% | +45.3% |
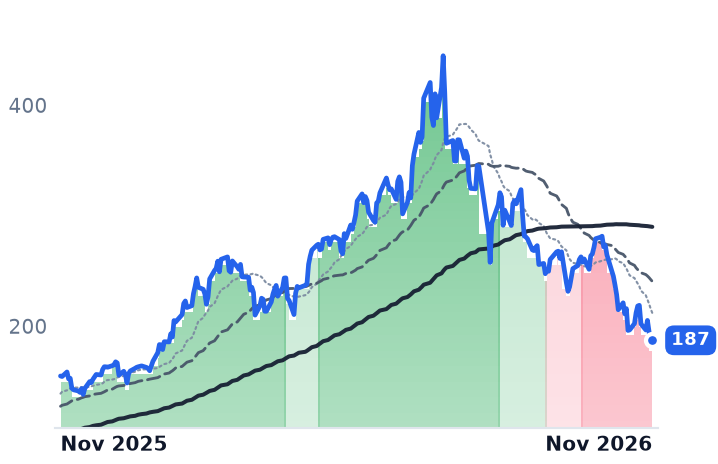
MKSI | MKS | Test & Measurement | ⚠️ Emerging Bear | −31.1% | +20.9% |
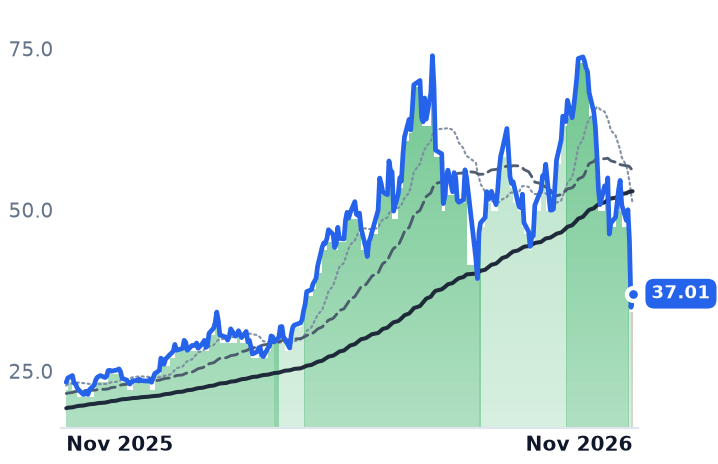
COHU | Cohu | Test & Assembly Services | 🟢 Cont. Bull | −48.6% | +59.1% |
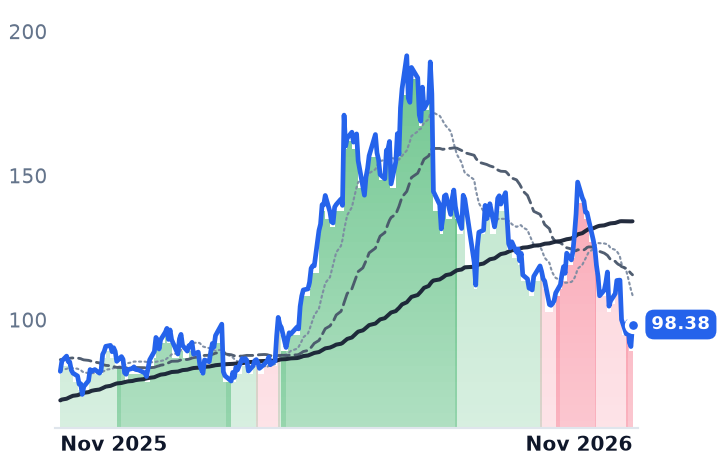
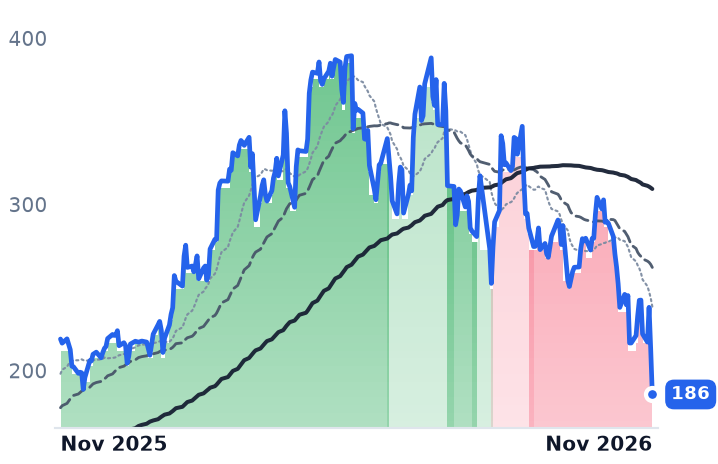
ACLS | Axcelis Technologies | Fabrication Equipment & Materials | ⚠️ Emerging Bear | −28.4% | +19.8% |
VECO | Veeco Instruments | Fabrication Equipment & Materials | ⚠️ Emerging Bear | −32.1% | +24.2% |
| Compared against · context, not the story | |||||
AEIS | Advanced Energy Industries | Power Conversion & Control | 🔴 Cont. Bear | −35.8% | −15.2% |
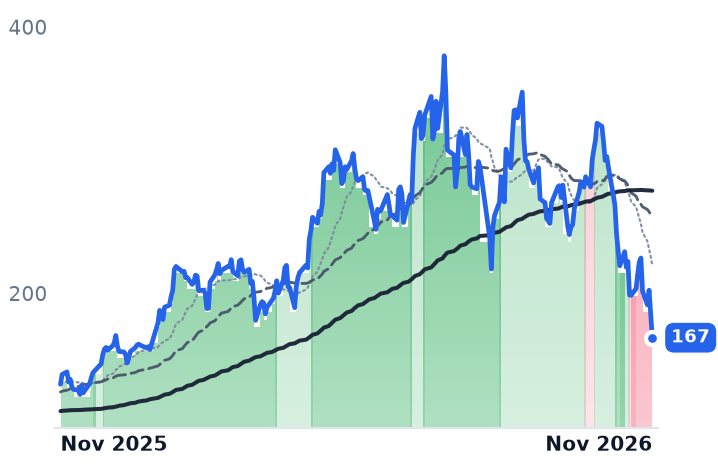
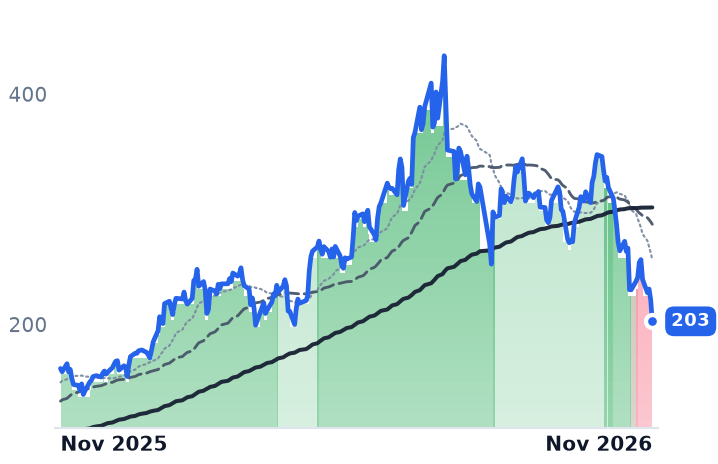
ONTO | Onto Innovation | Fabrication Equipment & Materials | ⚠️ Emerging Bear | −44.4% | +26.5% |
TER | Teradyne | Test & Assembly Services | 🟢 Cont. Bull | −48.5% | +15.1% |
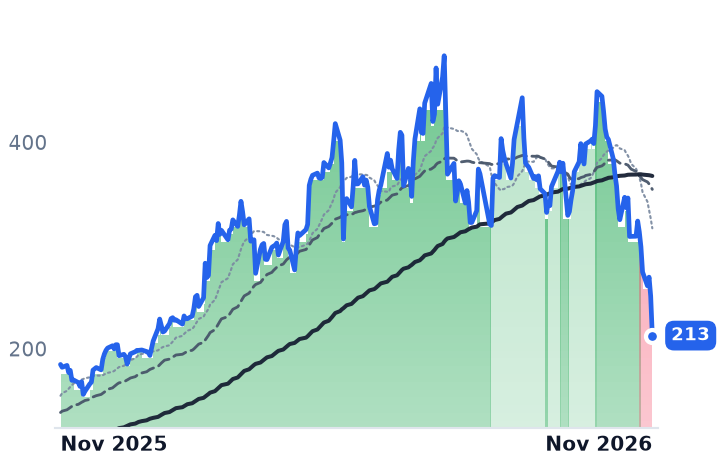
AMAT | Applied Materials | Fabrication Equipment & Materials | ⚠️ Emerging Bear | −33.6% | +47.8% |
LRCX | Lam Research | Fabrication Equipment & Materials | ⚠️ Emerging Bear | −37.5% | +25.3% |
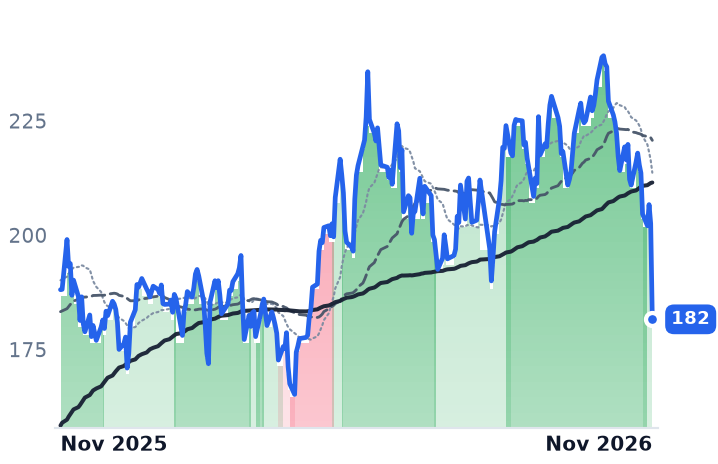
NVDA | NVIDIA | Processors & Accelerators | 🟢 Cont. Bull | −23.5% | −3.4% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FORM | $6.1B | 35.3x | 23.2x | 6.2x | 5.8x | 12.6x | 11.8x | 26.4x | 3.0% |
MKSI | $12.7B | 21.0x | 14.2x | 2.7x | 2.5x | 5.9x | 5.6x | 13.2x | 4.4% |
COHU | $1.7B | n/m | 34.7x | 3.1x | 2.8x | 7.3x | 6.7x | 43.2x | 3.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ACLS | $3.0B | 29.1x | 24.0x | 3.4x | 3.4x | 8.0x | 8.0x | 21.3x | 2.2% |
VECO | $2.2B | 85.7x | 24.2x | 3.0x | 2.8x | 8.1x | 7.4x | 43.3x | 5.7% |
AEIS | $11.4B | 49.5x | 25.4x | 5.6x | 4.7x | 14.1x | 11.9x | 37.7x | 0.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ONTO | $10.1B | 76.5x | 25.3x | 9.0x | 7.0x | 17.8x | 13.9x | 41.4x | 2.5% |
TER | $39.2B | 28.6x | 26.4x | 7.8x | 7.5x | 13.2x | 12.6x | 21.7x | 2.6% |
AMAT | $317.3B | — | 21.3x | — | 6.8x | — | — | 27.6x | 1.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LRCX | $303.0B | 35.9x | 25.0x | 11.6x | 8.6x | 22.7x | 16.8x | 29.4x | 2.2% |
NVDA | $5.5T | 34.3x | 25.0x | 21.5x | 13.9x | 29.0x | 18.7x | 28.3x | 2.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
FORM | Revenue | +34.6% | +24.3% | +26.7% |
| EPS | +199.2% | +29.0% | +38.5% | |
MKSI | Revenue | +29.7% | +20.5% | +10.3% |
| EPS | +67.2% | +33.9% | +14.9% | |
COHU | Revenue | +38.1% | +34.2% | +17.4% |
| EPS | +147643.1% | +122.8% | +35.8% | |
ACLS | Revenue | +8.3% | +11.9% | +26.0% |
| EPS | −8.7% | +28.3% | +56.2% | |
VECO | Revenue | +20.5% | +38.3% | — |
| EPS | +13.0% | +111.2% | — | |
AEIS | Revenue | +36.0% | +24.1% | +17.2% |
| EPS | +79.8% | +35.1% | +22.0% | |
ONTO | Revenue | +2.2% | +43.1% | +30.8% |
| EPS | −5.1% | +63.3% | +44.9% | |
TER | Revenue | +69.7% | +24.6% | +22.3% |
| EPS | +167.0% | +30.0% | +30.9% | |
AMAT | Revenue | +21.5% | +36.5% | +21.8% |
| EPS | +36.8% | +46.4% | +31.0% | |
LRCX | Revenue | +27.0% | +52.6% | +20.4% |
| EPS | +41.9% | +70.2% | +26.2% | |
NVDA | Revenue | +65.1% | +84.2% | +43.2% |
| EPS | +59.0% | +91.7% | +42.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
FormFactor told investors on 28 October that it will close 2026 above $1bn of revenue for the first time in the company's history. The probe cards it sells, the consumable contact arrays that test integrated circuits while they are still on the wafer, carried a 54.7% gross margin in the September quarter against 39.7% a year earlier. The shares ended 6 November at $78.77, roughly half their 2026 high.
Two other suppliers to the same step reported the same shape of quarter inside nine days. The layer's markdown has been read as the artificial-intelligence buildout cracking exactly where the industry had agreed it was tightest, in advanced packaging and the test that follows it. What the three actually disclosed locates the strain in the out-year capital budgets their customers' customers publish, not in their own order books.
What FormFactor's record memory quarter was made of
Revenue reached $280.5m, up 38.4%, the third straight quarter above 30% growth against full-year 2025 growth of 2.8%. The non-GAAP gross margin of 56.5% flattered that: about $10.5m came from one-time tariff refunds, and management put the durable baseline near 53%, with roughly $2m of refunds left after the fourth quarter.
The honest soft spot is the mix. FormFactor's third-quarter 10-Q attributes the quarter's memory increase to non-high-bandwidth-memory designs, specifically DDR5, with high-bandwidth-memory probe-card revenue declining sequentially on customer product-mix changes. The bottleneck framing is a 2027 claim. "We shipped probe cards to the world's leading foundry for 1 single GPU design in multimillion-dollar volumes," chief executive Mike Slessor said on 28 October, with chief financial officer Aric McKinnis sizing the new Farmers Branch plant at about $400m of annual probe-card capability exiting 2027.
The stock trades at 23.2x forward earnings against 35.3x trailing, and at 11.8x forward gross profit against 19.0x in late August and 25.2x in mid-May. On 12 October Teradyne agreed to buy 2,234,887 shares for $300m, an implied $134.24.
MKS ran out of its own capacity, not customers
MKS, which supplies vacuum, gas-delivery, power and laser subsystems plus the plating chemistry used in advanced packaging, grew revenue 43% to $1.413bn, its semiconductor segment 54% to $638m. "Current capacity is sold out through 2027, and to meet accelerated chemistry equipment demand, we are expanding capacity in Guangzhou, China," chief executive John T.C. Lee said on 5 November, targeting completion in the third quarter of 2027.
The leverage worry inherited from the Atotech deal has gone the other way: interest expense fell to $38m from $53m a year earlier against record quarterly adjusted earnings before interest, taxes, depreciation and amortization of $434m, with net leverage down to 2.4x and a new $500m repurchase authorization. At 14.2x forward earnings against 21.0x trailing, and 13.2x trailing enterprise value to EBITDA, it is the cheapest of the three on every one of those anchors, and cheaper than the roughly 29.6x forward it fetched in early May.
Cohu's handlers are booked; its earnings base is not
Cohu's test handlers and contactors produced $173m, up 37%, with gross margin at 45.5% from 35.7% and GAAP operating income back to $12.8m from a $9.3m loss. Bookings rose 126%, customer test-cell utilization hit 82%, and the fourth quarter is guided to $178m plus or minus $7m. "For 2027, we expect revenue growth of approximately 30% to 40%," chief executive Luis Müller said on 28 October, crediting rising power and test intensity rather than processor unit volume.
Cohu is also the weakest-anchored. Its forward earnings multiple of 34.7x is higher than the roughly 25x it carried in May, because 2026 earnings start from near zero; the case rests on 7.33x trailing gross profit against 12.5x in August.
The selling came from outside the order books
None of the decline is in the results. Between 7 October and 5 November, Teradyne fell 48.5% and Lam Research 37.5% against Nvidia's 23.5%; Onto Innovation lost 44% without having reported at all. Two dated events bracket it: Microsoft and Alphabet declined on 29 October to raise capital-expenditure forecasts, and a semiconductor gauge fell 12% on 5 November, its worst session since March 2020, on the data-center regulation fear the front page has been tracking since the midterms. Revenue booked for 2027 and 2028 reprices on an out-year budget twice as hard as revenue being shipped today, which is the whole mechanism.
What remains genuinely open is timing rather than direction. Cohu's billion-dollar computing funnel is mostly in qualification, on cycles management puts at nine to twelve months; FormFactor's high-bandwidth-memory line went down last quarter, not up; MKS's doubled chemistry capacity does not exist until late 2027. Against that, Citi has raised its 2027 capex estimates for Alphabet, Meta and Amazon to roughly $801bn combined.
Teradyne, which competes with Cohu in handlers and knows what a test order book looks like, paid an implied $134.24 for its FormFactor stake in October. The market has since offered the same shares at $78.77. One of those two prices was reading the 2027 book.