

A New Compression Package Takes Archrock Seven Years of Rent to Pay Back Its Cost
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Natural gas compressors have never rented for more money than they do now, and the companies that own them were marked down by roughly a sixth in two sessions. Archrock reported revenue of $24.38 a month per horsepower on 3 November, up 4% on the year, with 94.3% of the fleet working and an eighth straight quarter of contract-operations margin at or above 70%. USA Compression posted a record $23.14, up 8% on the year.
Nothing in the rate, the utilization or the forward contract book turned. What did change was the price of data-center-adjacent energy risk after the Texas governor's race: Kodiak Gas Services fell 16.4% without having reported at all, and now trades at 6.44x trailing enterprise value to EBITDA against roughly 9.8x in late August. The cost side is real but small, and it was disclosed in August.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
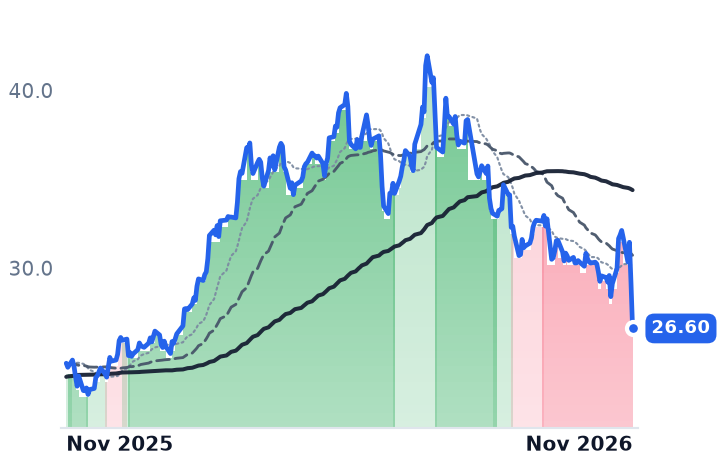
AROC | Archrock | Gas Compression & Processing | ⚠️ Emerging Bear | −12.9% | +7.9% |
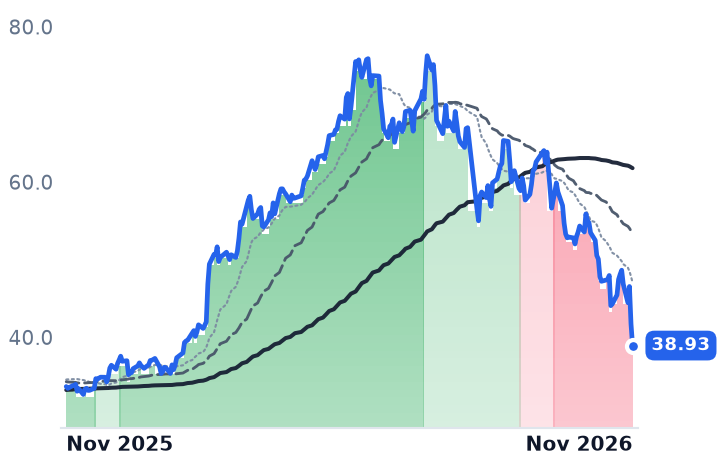
KGS | Kodiak Gas Services | Gas Compression & Processing | ⚠️ Emerging Bear | −29.3% | +15.7% |
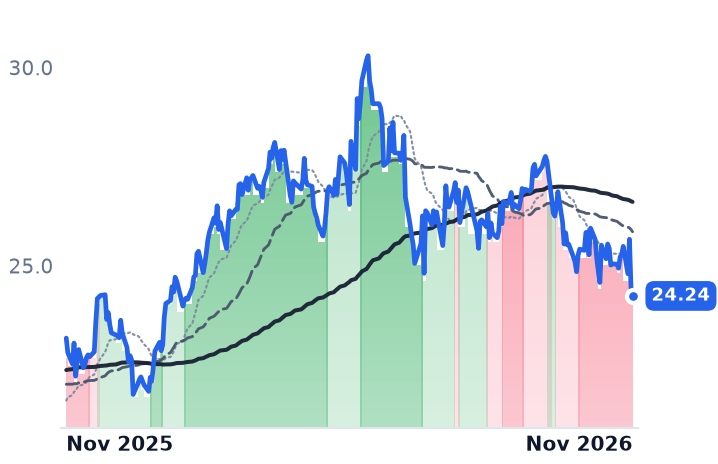
USAC | USA Compression Partners | Compression & Gas Processing | 🔴 Cont. Bear | −6.2% | +4.6% |
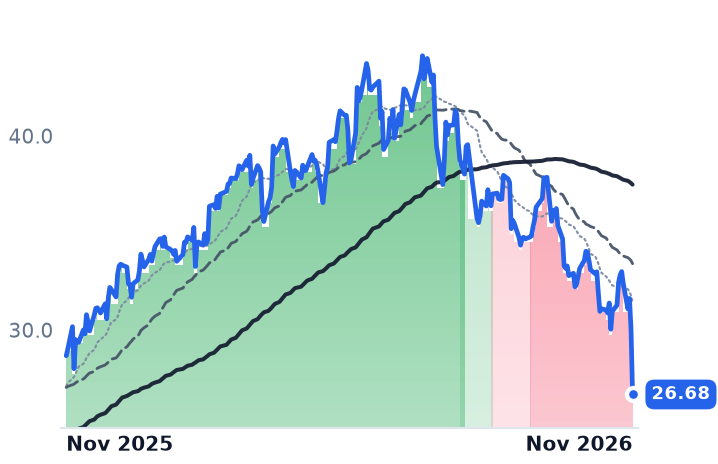
NGS | Natural Gas Services | Compression & Gas Processing | 🔴 Cont. Bear | −21.5% | −6.9% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AROC | $4.7B | 13.7x | 15.5x | 3.1x | 3.1x | 5.4x | 5.3x | 8.6x | 6.5% |
KGS | $3.9B | 44.2x | 19.7x | 2.8x | 2.6x | 7.0x | 6.5x | 6.4x | 0.1% |
USAC | $3.7B | 22.5x | 19.7x | 2.9x | 2.7x | 10.5x | 9.7x | 6.1x | 11.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NGS | $344.1M | 16.4x | 15.3x | 1.8x | 1.6x | 4.1x | 3.6x | 8.0x | -9.1% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
AROC | Revenue | +1.4% | +8.1% | +7.8% |
| EPS | +9.4% | +19.8% | +16.5% | |
KGS | Revenue | +16.2% | +14.3% | +18.3% |
| EPS | +77.3% | +37.5% | +44.8% | |
USAC | Revenue | +37.8% | +6.9% | +4.6% |
| EPS | +38.5% | +26.7% | +20.0% | |
NGS | Revenue | +25.8% | +18.8% | +8.3% |
| EPS | +7.2% | +45.8% | +14.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Archrock, the largest US contract compression provider, which owns and leases natural gas compressors to gatherers, processors and pipelines, told investors on 3 November that one horsepower of its fleet now rents for $24.38 a month, up 4% on the year, with 94.3% of the fleet working. Adjusted earnings of $0.49 a share beat the $0.45 analysts expected, the dividend rose about 10% to an annualised $0.92, and leverage came down to 2.5x from 3.1x.
Compression has lately been traded as a derivative of the data-center buildout. The quarter describes something duller and far more durable: a rental business whose own payback arithmetic makes oversupply close to impossible, and whose rate therefore keeps climbing.
Seven years of rent for a $1,500 package
Start with the single unit. At a 72% contract-operations margin, Archrock's $24.38 monthly rate keeps roughly $17.55 of gross margin, or about $211 a horsepower a year. Against that, management reaffirmed $1.4bn-$1.6bn of cumulative growth capital from 2027 through 2030 to buy approximately 1 million horsepower, which is $1,400-$1,600 to put one new horsepower in the field. Those figures are the company's; the division is ours, and it says a new package returns its cost in gross margin only after about seven years, before overhead, maintenance capital and tax.
That is why nobody floods this market. The second gate is physical: Caterpillar engine lead times remain beyond 180 weeks, and Archrock's booking-to-revenue cycle has stretched to about 1.25 years from one year. "When you're talking about 4 years to get a compressor 185 to 200 weeks, somewhere in there to get an engine, there's definitely an urgency to make sure they have equipment for what's coming down the pipe," Micah Green, president and chief executive of USA Compression, told investors on 3 November.
Archrock added roughly 21,000 operating horsepower in the quarter and expects more idle units back in service by year-end. Year-to-date bookings were up 13%, the best quarter since the second quarter of 2023.
The cost side is lube oil, and it was disclosed in August
USA Compression, the Energy Transfer-sponsored compression partnership, is where the squeeze shows. Its record $23.14 monthly rate rose only 1% sequentially, with management citing smaller operators pressing on price, and its 62.2% adjusted gross margin, which carries a roughly $30m retail parts and service book, leaves about $14.39 a horsepower a month. Lube oil ran some 25% above the first half and diesel hit all-time highs, and the partnership trimmed the top of its 2026 EBITDA guide to $770m-$780m from $770m-$800m. It also improved distribution coverage to 1.67x and has more than 60% of 2027 new horsepower already contracted.
Kodiak Gas Services, the large-horsepower Permian operator that also controls roughly 395 MW of distributed gas-fired power with about two-thirds contracted to data centers, last reported $23.80 a horsepower on 98.2% utilization and raised full-year EBITDA guidance to $830m-$860m. Its third quarter lands on 9 November.
Two sessions, no disclosure
Archrock's shares rose 4.5% on the day of the print, then fell 15.4% over 4-5 November. Kodiak fell 16.4% in the same two sessions with no new company information of any kind. USA Compression, the yield vehicle, lost 5.6%. The context is the one the market already assigned: the 3 November Texas result, read as a threat to data-center development, with the governor's appointment power over utility and environmental regulators the channel that reaches engine permitting.
So the results account for none of the markdown, and the valuations have moved further than the earnings. Kodiak now trades at 6.44x trailing enterprise value to EBITDA against roughly 9.8x in late August, while its EBITDA was setting records; 19.7x forward earnings sits against consensus of about $1.97 a share versus $0.89 last year. Archrock's 8.58x enterprise multiple comes with one honest blemish: forward earnings of 15.5x sit above trailing 13.7x, because 2026 consensus of $1.72 a share is still below 2025's $1.84. The genuine deterioration in its quarter is Aftermarket Services, down 29% to $40m of $370.8m total revenue as customers defer maintenance to run-to-failure.
"If I were to take the over-under, I still believe the market is more likely to be short of compression equipment than long on compression equipment," Brad Childers, Archrock's chief executive, said on 3 November. On the same call he sized the gas needed to power data centers at less than a third of the LNG equivalent, two days before his stock was repriced as a data-center asset.
An engine ordered now arrives closer to 2030 than to next summer. Whoever signs that order is underwriting a decade of rate, and the people selling the shares this week were trading a week.