

Vertex's Invoice Volume Is Set by French Law, and It Lowered Its Cloud Growth Forecast
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
A shelf of financial-services software re-rated hard through October without a single one of its members reporting results, and the three vendors whose revenue runs on one regulated transaction turn out to be mirror images rather than one story.
Vertex has statutory volume: France's e-invoicing and transaction-reporting obligation for its largest companies began on 1 September 2026, Germany's issuing rule starts in 2027. It still lowered full-year cloud revenue growth guidance to 18% on slower customer migration, with annual recurring revenue up 10.5% and net revenue retention of 105%, down from 108%.
BlackLine has no regulator setting anything: recurring revenue grew 6% against a 13-16% ambition, retention 102.4%, held back by its own move off per-seat pricing. FICO's price lever, the only thing that drove its year, is frozen. All three report within four days.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
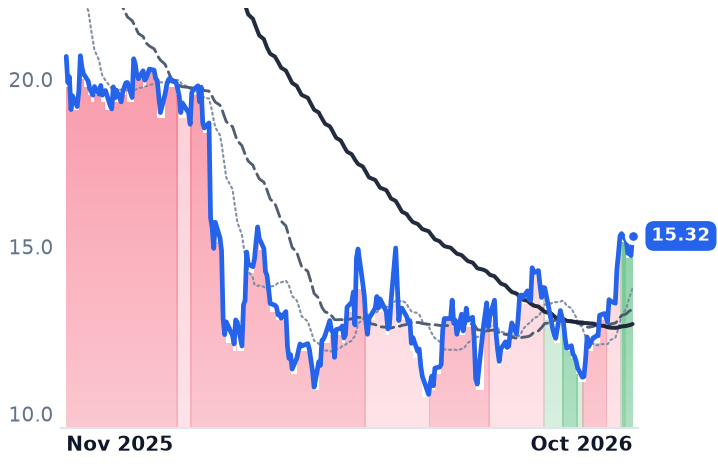
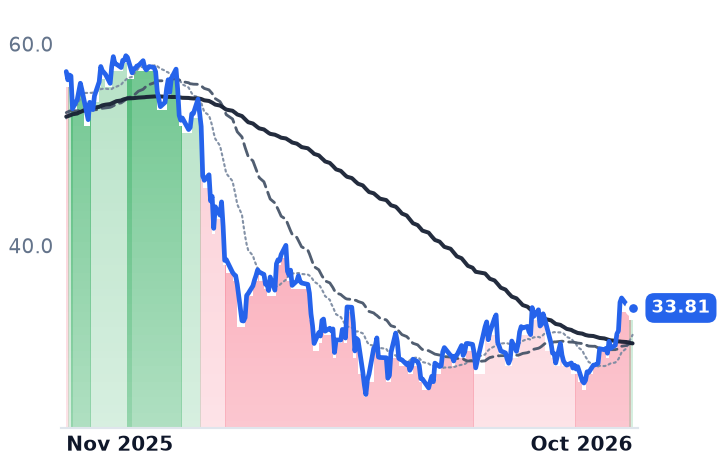
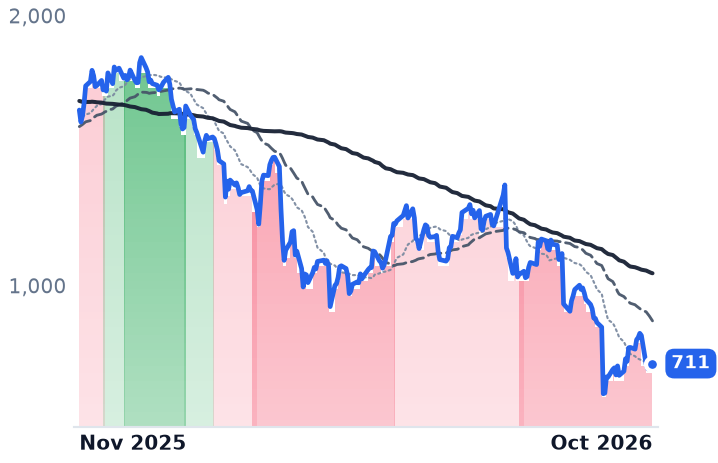
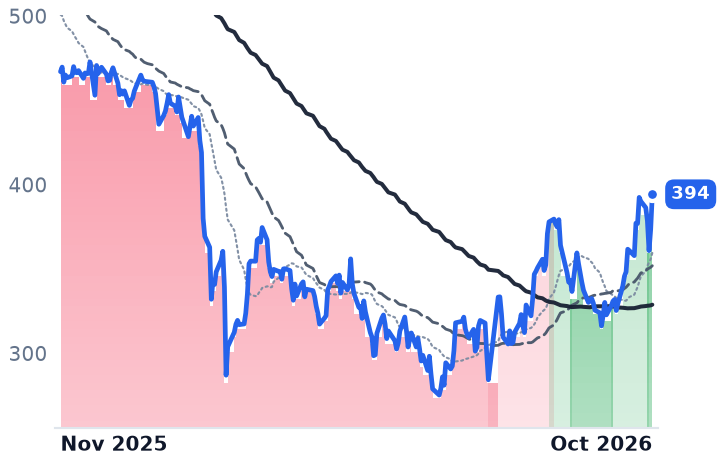
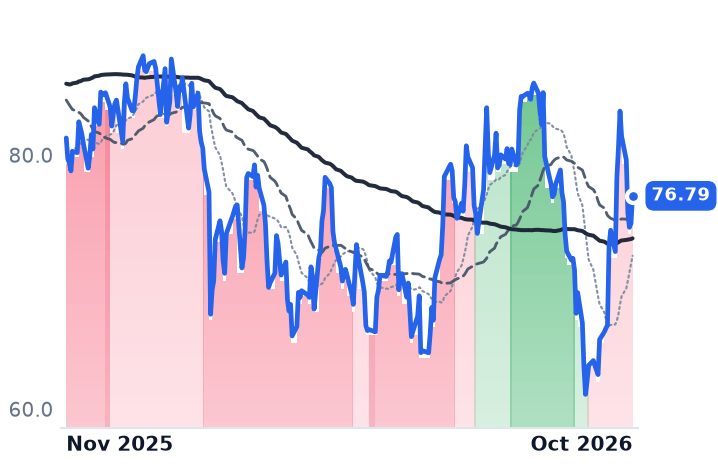
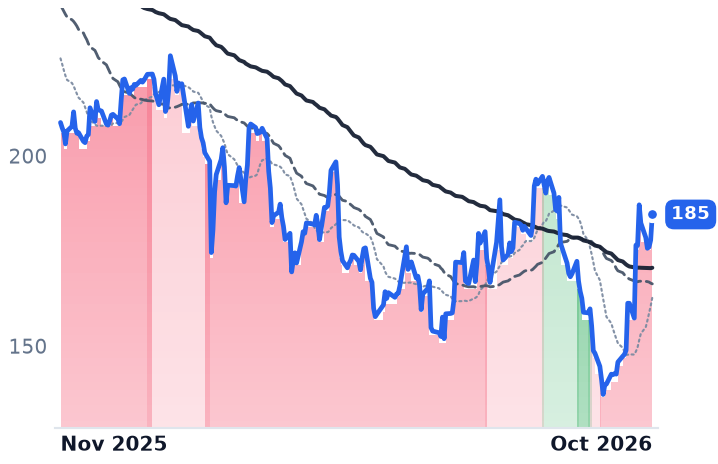
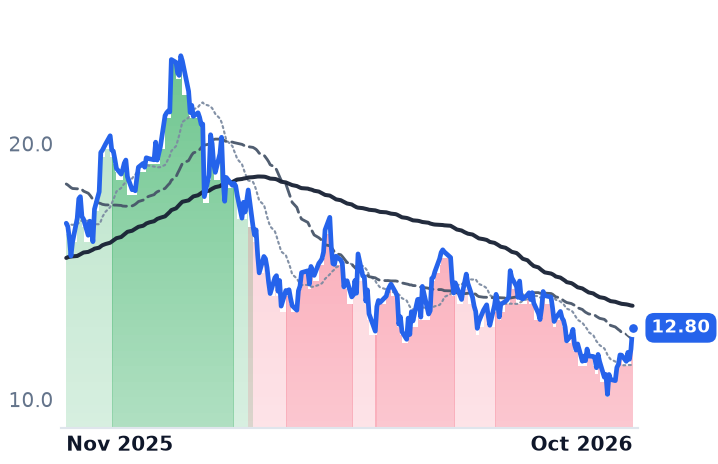
VERX | Vertex | Commerce & Digital Payments | 🌱 Emerging Bull | +24.8% | −26.0% |
BL | BlackLine | Other | 🔴 Cont. Bear | +20.2% | −41.0% |
FICO | Fair Isaac | Data, Analytics & Intelligence | 🔴 Cont. Bear | +3.1% | −56.9% |
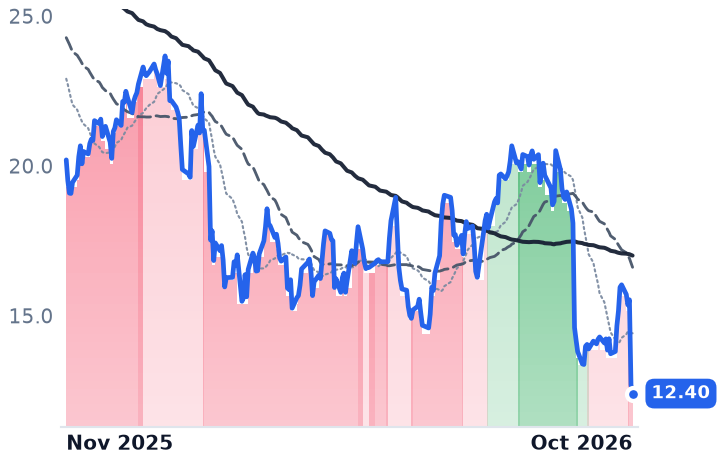
ALKT | Alkami Technology | Commerce & Digital Payments | 🔴 Cont. Bear | −12.4% | −38.6% |
NCNO | nCino | Commerce & Digital Payments | 🌱 Emerging Bull | +17.6% | −15.2% |
QTWO | Q2 | Commerce & Digital Payments | 🟢 Cont. Bull | +15.2% | +7.1% |
SSNC | SS&C Technologies | Enterprise Resource Planning | 🌱 Emerging Bull | +1.7% | −4.5% |
GWRE | Guidewire Software | Industry-Specific Platforms | 🌱 Emerging Bull | −0.4% | −28.7% |
TYL | Tyler Technologies | Industry-Specific Platforms | 🌱 Emerging Bull | +20.1% | −15.6% |
| Compared against · context, not the story | |||||
TRU | TransUnion | Consumer Credit Reporting | 🔴 Cont. Bear | +20.3% | −5.6% |
EFX | Equifax | Workforce Data & Analytics | 🔴 Cont. Bear | +29.5% | −11.6% |
RKT | Rocket Companies | Residential Loan Originators | 🔴 Cont. Bear | +9.6% | −24.2% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −2.5% | +11.2% |
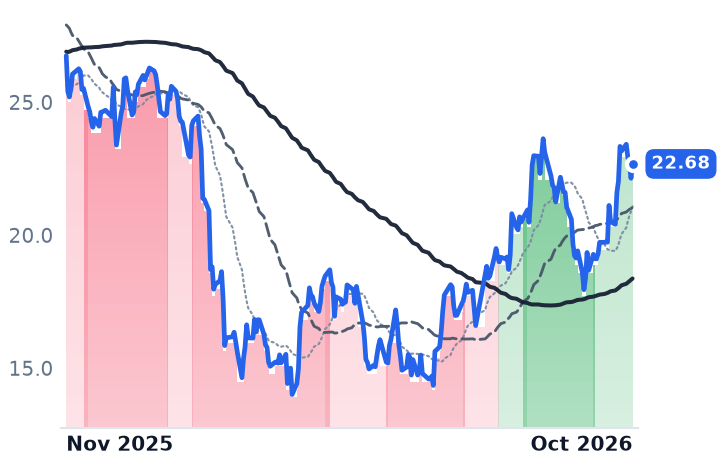
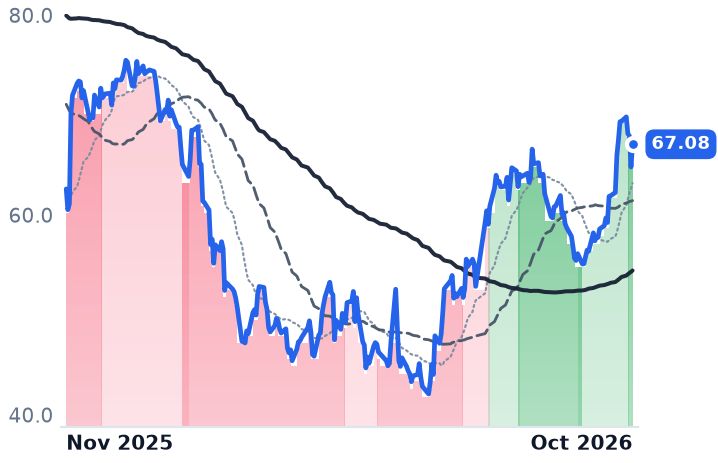
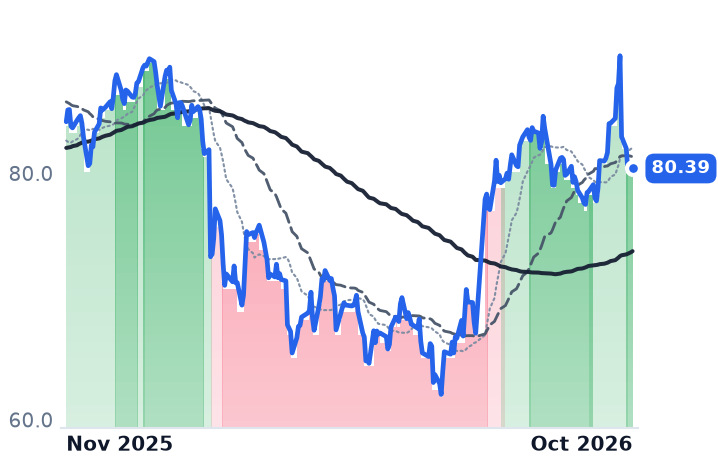
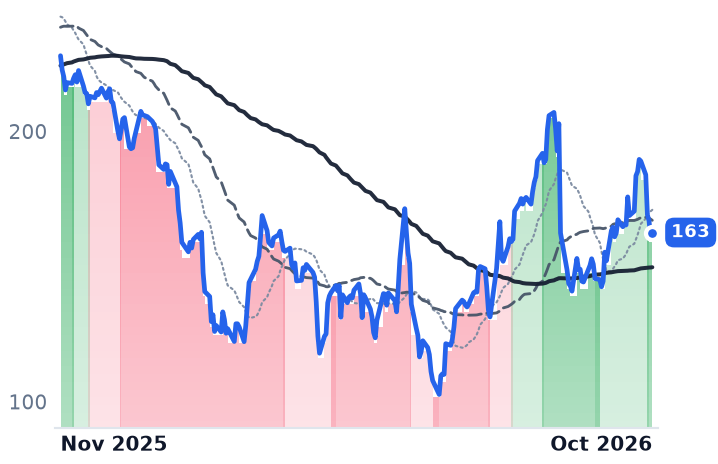
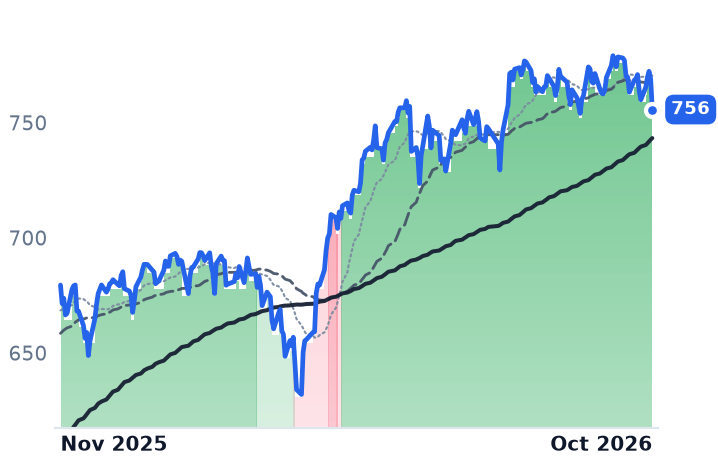
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VERX | $2.5B | 500.7x | 18.7x | 3.2x | 3.0x | 5.1x | 4.8x | 49.6x | 2.4% |
BL | $2.0B | 57.5x | 13.6x | 2.7x | 2.6x | 3.6x | 3.4x | 23.8x | 8.7% |
FICO | $15.4B | 20.4x | 15.2x | 6.4x | 5.7x | 7.5x | 6.7x | 16.3x | 6.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ALKT | $1.3B | n/m | 15.0x | 2.6x | 2.5x | 4.5x | 4.4x | 256.4x | 4.1% |
NCNO | $2.4B | 73.2x | 17.2x | 3.9x | 3.7x | 6.3x | 6.0x | 28.7x | 5.5% |
QTWO | $4.1B | 37.9x | 24.0x | 4.8x | 4.7x | 8.2x | 8.0x | 24.5x | 5.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SSNC | $18.9B | 22.5x | 11.3x | 2.8x | 2.8x | 5.9x | 5.8x | 11.6x | 9.3% |
GWRE | $13.4B | 98.5x | 39.1x | 9.1x | 7.8x | 14.2x | 12.2x | 64.4x | 2.2% |
TYL | $15.7B | 49.2x | 30.1x | 6.3x | 6.1x | 13.4x | 13.0x | 28.1x | 4.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TRU | $12.8B | 17.5x | 13.8x | 2.6x | 2.5x | 4.7x | 4.5x | 9.6x | 6.1% |
EFX | $17.7B | 26.2x | 17.6x | 2.7x | 2.6x | 4.9x | 4.7x | 12.1x | 6.3% |
RKT | $29.7B | 67.3x | 17.7x | 3.1x | 2.7x | 3.4x | 3.0x | 24.1x | -2.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
VERX | Revenue | +10.6% | +10.5% | +11.5% |
| EPS | +28.6% | +23.8% | +21.1% | |
BL | Revenue | +9.5% | +10.4% | +10.3% |
| EPS | +19.7% | +10.9% | +18.0% | |
FICO | Revenue | +27.3% | +6.3% | +7.2% |
| EPS | +44.8% | +9.6% | +12.3% | |
ALKT | Revenue | +19.9% | +14.4% | +14.4% |
| EPS | +58.9% | +30.1% | +26.1% | |
NCNO | Revenue | +9.8% | +8.9% | +8.6% |
| EPS | +25.2% | +45.3% | +20.0% | |
QTWO | Revenue | +12.5% | +10.2% | +10.0% |
| EPS | +17.9% | +23.8% | +17.2% | |
SSNC | Revenue | +8.4% | +5.1% | +4.9% |
| EPS | +17.7% | +8.6% | +8.4% | |
GWRE | Revenue | +23.8% | +17.2% | +15.6% |
| EPS | +41.5% | +20.0% | +27.5% | |
TYL | Revenue | +8.7% | +9.8% | +9.8% |
| EPS | +14.7% | +18.9% | +14.0% | |
TRU | Revenue | +13.8% | +8.2% | +8.1% |
| EPS | +13.5% | +15.0% | +15.8% | |
EFX | Revenue | +11.2% | +8.3% | +9.7% |
| EPS | +11.8% | +17.4% | +21.0% | |
RKT | Revenue | +72.1% | +5.7% | +7.9% |
| EPS | +146.1% | +34.6% | +21.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Vertex sells the indirect-tax engine that calculates sales tax and value-added tax inside corporate order and billing systems, and it has something few software vendors have: a legislature setting its volumes. France now requires its largest value-added-tax registrants to issue electronic invoices and to submit consumer and cross-border transaction data to the tax authority through approved platforms, an obligation that began on 1 September 2026, with Germany's issuing rule starting in 2027 for firms above €800,000 of prior-year turnover. In August the company lowered its full-year cloud revenue growth guidance to 18%.
That gap matters because of what happened to the shares without it. Across the 30 trading days to 30 October, eight of nine financial-services software names rose, an equal-weighted 16.4% against a 0.9% decline in the S&P 500 tracking fund, with Vertex up 32.1% and BlackLine up 26.9% and both moving from a year-long downtrend into an uptrend. Not one of the nine reported results inside that window. The Federal Reserve held its benchmark near 3.9% at its 27-28 October meeting. The month was read as proof that vertical software billed inside a regulated workflow keeps its pricing power while generic seats get eaten by artificial intelligence. The three vendors that actually sit in such a workflow do not agree with each other about that.
A legislature sets the volume; the customer sets the timing
Vertex's annual recurring revenue reached $703.4m at 30 June, up 10.5%, with net revenue retention at 105% against 108% a year earlier and average annual revenue per customer of $142,997, up 9.2%. Cloud revenue was $101.7m, up 17.9%, inside full-year guidance of $825-830m. The e-invoicing line grew well above the corporate average and the company won several six-figure enterprise deals, including a mid-six-figure expansion driven by mandates in two countries, France and Finland. But the cloud guide came down because convergence and migration ran slower than planned; management called it a conversion timing issue rather than a revenue issue, customers delaying on information-technology priorities and broader enterprise-resource-planning schedules. Chief executive Christopher Young told the 3 August call that cloud growth should accelerate on e-invoicing.
The price paid for that promise moved first. Against a constant $488.6m of gross profit from the last four reported quarters, Vertex's price went from roughly 3.85x that figure on 30 September to 5.09x on 30 October, within reach of the 6.9x implied at its 12-month high. Reported revenue growth has been flat to slower for a year: 10.5% in June, 11.1% in March, against 16.5% for 2024.
BlackLine is slowing itself down on purpose
BlackLine automates the accounting close for large enterprises, and nobody legislates its price. Recurring revenue was $719m at June, up 6%, against the 13-16% the company holds out as its ambition, with dollar-based net revenue retention of 102.4% that the company attributed partly to lower levels of user adds. The cause is partly its own doing: nearly 90% of net new business now lands on platform pricing instead of seats, and platform recurring revenue rose to more than 17% of eligible recurring revenue from 13% in a single quarter, a shift management concedes understates demand near term.
"We saw a 4X increase in the number of customers on Verity, and we have now proof points in terms of the monetization of our agentic revenue," chief executive Owen Ryan said on the 4 August call. Reported revenue grew 9.2% to $187.8m with operating income up 45.7%. The shares now cost 3.55x trailing gross profit against about 2.80x a month earlier and roughly 6.2x a year ago, and the largest single session of the advance, 8.4% on 22 October, came on volume 73% below average alongside unrelated software names.
FICO had the only price lever, and a regulator opened the socket
Fair Isaac is the one of the three whose per-unit price did all the work and the one that did not turn. Mortgage originations were 71% of business-to-business Scores revenue and 62% of total Scores revenue in the June quarter, where mortgage-origination revenue rose 97% on score volumes up only low single digits after the wholesale royalty went from $4.95 to $10.00. TransUnion has now fixed VantageScore 4.0 mortgage pricing at $0.99 through 2028 and supplies it free alongside a FICO pull, and on 23 October FICO held its own price at $10 for lenders in a new Preferred Program. The shares fell 13.2% the next session, and Wells Fargo cut its target to $735 from $800 while UBS went to $942 from $1,100. At 15.2x forward and 20.4x trailing earnings, against roughly 62x trailing in January, the stock is cheap because the lever that made the numbers is frozen.
The month paid for pricing power none of the three has shown
The results explain almost none of the advance, because there were no results. The likelier reading is the unwind of the de-rating that took software down on fears customers would build applications in-house with artificial intelligence; the S&P 500 software and services index reached its highest level since November 2025 in early October, and it landed hardest on the cheapest shelf. Breadth was not universal: Alkami, which sells digital banking platforms, fell 11.3% over the same 30 days and slid into a downtrend. And the one consensus revision discoverable inside the window went down.
Size the difference between the three and the split has a cause in each case. Vertex's volume is written into statute but its revenue recognition waits on customer migration schedules it does not control. BlackLine's growth is being suppressed by a pricing migration it chose, which is also the only answer it has to being paid for work its software removes. FICO showed what a genuine per-unit price increase does to a profit and loss statement, and then lost the right to repeat it.
FICO and Vertex report after the close on 4 November, BlackLine on 5 November. Within four days the shelf that re-rated on no information at all will have three quarters of it.