

Celestica Says the Year It Nearly Doubles to $40bn Will Be a Net Use of Cash
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
The contract manufacturers that bolt together AI server racks are growing faster than at any point in their history, and the one growing fastest just told investors it will not generate cash while doing it. Celestica guided 2027 revenue to about $40bn against roughly $21bn this year, cut 2026 free-cash-flow guidance to $460m from $600m, and set 2027 capital spending at $1.5–2.0bn.
Its September quarter grew revenue 82.5% while gross profit grew 54%, and the design-led Hardware Platform Solutions line grew 70% — slower than the assembly it is meant to out-earn. Flex went the other way: its Cloud, Power & Infrastructure segment grew 54% with operating margin up 240 basis points to 10.7%, and Jabil funds its rack work on net capital spending of 1.3% of revenue. All three beat and raised, and all three were marked down anyway.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
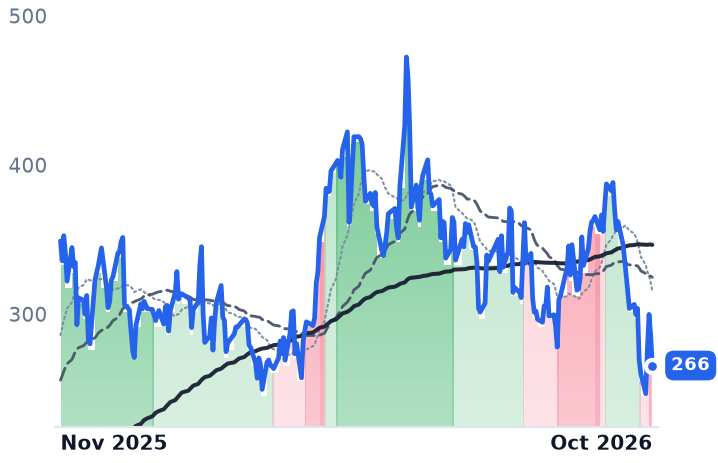
CLS | Celestica | Contract Manufacturing | ⚠️ Emerging Bear | −31.4% | −23.9% |
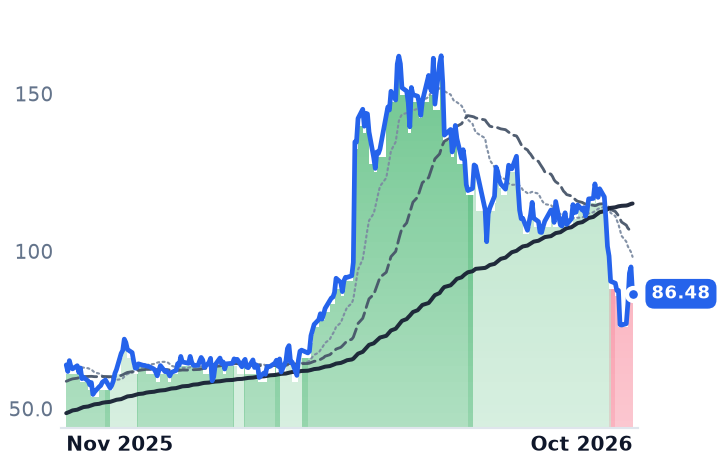
FLEX | Flex | Contract Manufacturing | ⚠️ Emerging Bear | −25.8% | +35.3% |
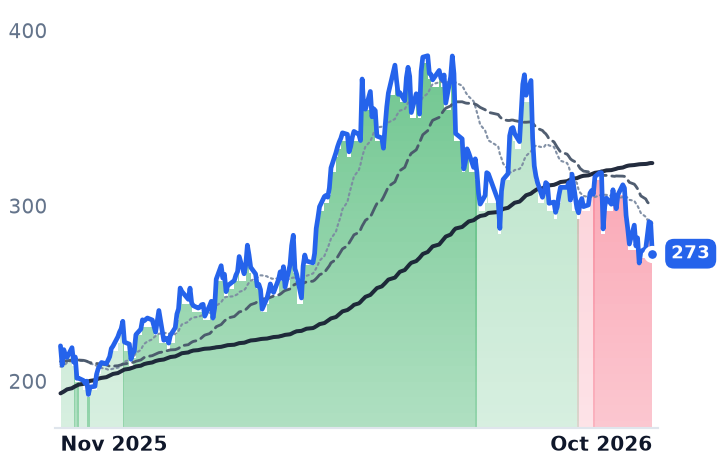
JBL | Jabil | Contract Manufacturing | ⚠️ Emerging Bear | −10.4% | +23.9% |
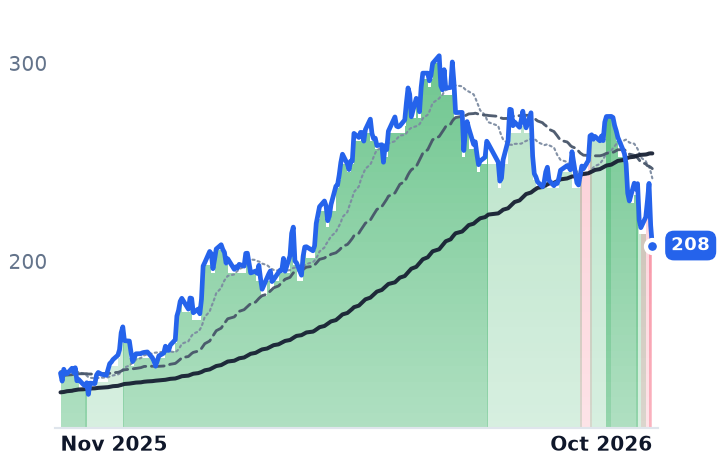
PLXS | Plexus | Other | 🟢 Cont. Bull | −23.9% | +44.9% |
SANM | Sanmina | Contract Manufacturing | 🟢 Cont. Bull | −27.7% | +18.0% |
BHE | Benchmark Electronics | Contract Manufacturing | 🟢 Cont. Bull | −21.8% | +56.5% |
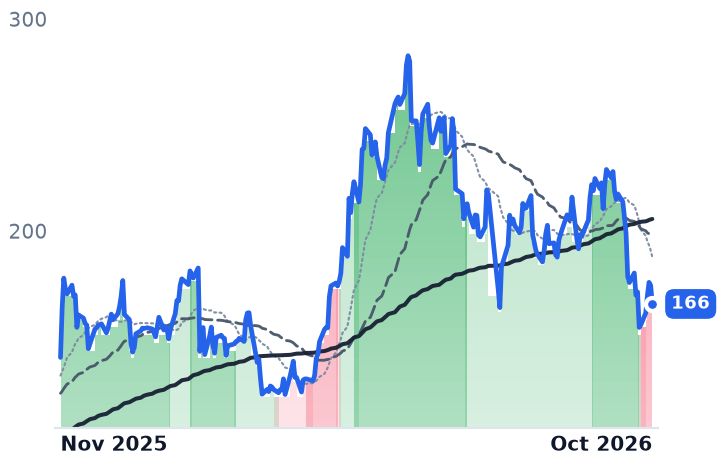
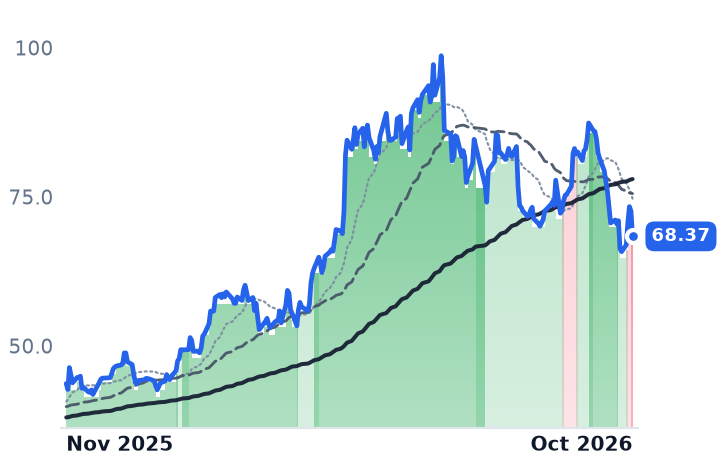
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CLS | $33.5B | 24.6x | 23.0x | 1.8x | 1.6x | 16.0x | 13.9x | 17.6x | 1.6% |
FLEX | $32.0B | 31.2x | 17.5x | 1.0x | 0.9x | 10.7x | 9.4x | 16.2x | 3.2% |
JBL | $28.1B | 27.6x | 15.4x | 0.8x | 0.6x | 8.5x | 6.8x | 13.5x | 6.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PLXS | $5.5B | 27.4x | 19.5x | 1.1x | 0.9x | 11.0x | 9.4x | 17.3x | -0.5% |
SANM | $8.9B | 29.0x | 11.8x | 0.7x | 0.5x | 7.7x | 5.9x | 13.2x | 6.7% |
BHE | $2.4B | 43.8x | 22.5x | 0.8x | 0.8x | 8.0x | 7.7x | 16.1x | 4.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CLS | Revenue | +70.5% | +88.7% | +44.5% |
| EPS | +93.1% | +90.3% | +45.6% | |
FLEX | Revenue | +6.8% | +29.2% | +30.7% |
| EPS | +24.2% | +52.6% | +53.2% | |
JBL | Revenue | +20.3% | +27.7% | +15.5% |
| EPS | +36.0% | +38.5% | +24.7% | |
PLXS | Revenue | +21.6% | +19.3% | +9.9% |
| EPS | +21.0% | +22.9% | +16.2% | |
SANM | Revenue | +74.9% | +17.5% | +16.8% |
| EPS | +103.5% | +16.2% | +15.4% | |
BHE | Revenue | +15.4% | +8.3% | +5.4% |
| EPS | +30.0% | +13.7% | +11.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Celestica told investors on 27 October that it expects about $40bn of revenue in 2027, nearly double the roughly $21bn it now guides for this year, and in the same breath that the year would be a net use of cash with positive free cash flow not returning until 2028. The shares rose 12.1% that day and a further 8.4% the next, then gave the entire move back on 29 and 30 October.
The re-rating that took Celestica from single-digit earnings multiples rested on a belief about mix: that designing hyperscale racks pays better than screwing them together. The September quarter is the first clean test of that belief at scale, and it reads three ways across the shelf — compressing at Celestica, expanding at Flex, and barely capital-intensive at all at Jabil.
The quarter that grew 83% and gave up gross margin
Celestica, the Toronto contract manufacturer that designs and assembles switches, data-center interconnects, servers and storage for hyperscale cloud buyers, reported revenue of $5,829.7m, up 82.5%. Gross profit grew 54%, so gross margin fell to 10.99% from 13.03% a year earlier on the reported series; management's own adjusted figure, on a different basis, was 11.2%, down 50 basis points on mix.
The composition explains the gap. Connectivity & Cloud Solutions reached $4.9bn, up 102%, with Compute and Storage up 242%. The design-led Hardware Platform Solutions line reached $2.3bn, up 70% — slower than the group — which on its own disclosed figures takes HPS from 42% of revenue in the March quarter to 39.5% in September. The pure-assembly work accelerated; the design work did not keep up.
None of which is a market-share problem. Celestica puts itself at 31% of revenue and 44% of port shipments in 800G-plus switching and 58% of custom Ethernet switches, with ten 1.6-terabit programs won and research spending now above $300m a year, three times its 2023 level. Its three largest customers were 35%, 17% and 14% of September-quarter revenue, and the top ten rose to 85% from 80%.
The bill arrives a year before the revenue
Free-cash-flow guidance for 2026 came down to $460m from $600m to fund working capital for next year's growth. The 2027 capital budget of $1.5–2.0bn is 3.75% to 5.0% of the guided revenue it supports, and Celestica raised $3.45bn of equity during the quarter. Its trailing free-cash-flow yield of 1.64% is the lowest of the six names on this shelf.
"Our $40 billion guide took into consideration the risks around the ramps, the component availability, and the operational execution, David," chief financial officer Todd Ankenmann told analysts on 27 October. "At 90% year-to-year growth, we feel high confidence that that number is supported." The confidence is in the revenue. The cash timing is the disclosure.
Component prices are part of what has to be financed: the contract price of a 64GB DDR5 server memory module reached roughly $1,500 from about $272 a year earlier, and suppliers do not forecast relief before 2028.
Flex sold the part of the rack that pays
Flex, which builds switchgear, busways and power distribution for data centers alongside its broader manufacturing book, reported its Cloud, Power & Infrastructure segment up 54% to $2.5bn with operating margin up 240 basis points to 10.7%. "Power segment operating margin increased to approximately 16%, up roughly 550-basis points year over year driven by strong volume growth and the benefits of scaling the investments we made last year," chief financial officer Kevin S. Krumm said on 28 October. Group gross margin rose to 9.56% from 9.02%, a fourth consecutive annual improvement from 7.06% in fiscal 2024. Inventory rose 39%, pushing net working capital to 60 days. The segment is being separated as Axiom Solutions International, targeted for the first quarter of 2027.
Jabil's version is the capital-light one. Intelligent Infrastructure grew 56% to $5.8bn, net capital spending ran at 1.3% of fiscal 2026 revenue — $470m on $36bn — free-cash-flow conversion exceeded 100%, and core return on invested capital is 59%. Its shares still fell about 10% on 30 September on a beat and a raise.
What the selling was actually about
The margin split does not explain the drawdowns, because the name with no AI-rack exposure fell too. Plexus — semiconductor capital equipment, aerospace, defense and medical — dropped 20.3% over the 30 days to 30 October after a record quarter of $1.43bn, up 35%, a 6.2% full-year operating margin and the best cash cycle in its history at 62 days. Sanmina now owns AMD's former rack-assembly plants and Benchmark's advanced computing line grew 50%, so neither is a control on anything.
What moved was the willingness to pay, not the order book. Hyperscale capital budgets for 2026 stand at $720–745bn, and the dated trigger was financing discipline rather than demand: Microsoft trimmed its figure to $170bn and Google declined to raise its forecast in late October, before a session that erased more than $1trn of technology market value.
So the multiples did the moving while the businesses accelerated. Celestica now trades at 24.6x trailing earnings and about 12.1x the $21.98 fiscal 2027 consensus, against the roughly 30x forward multiple of mid-May. Measured against trailing gross profit, the cheapest of the three is Jabil at 8.5x, down from 12.8x in May. The reported results account for none of the decline; the question the market is now pricing is who funds the next rack, and Celestica has answered it in writing.
Sanmina reports on 9 November and Flex details both post-spin companies at an innovation day the following day. Celestica's own next disclosure is further out, which leaves its 2027 budget standing alone for now: a year of spending it has already promised, against revenue it will book before the cash shows up.