

Strip Out the Factory Tax Credit and Enphase's Inverters Earn a Third Less Than Last Year
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Enphase's September quarter was read as a volume problem. Measured at the shipped unit, with the federal manufacturing credit taken out of cost of goods, it is a price-and-margin problem: ex-credit gross margin fell to 23.4% from 31.3% a year earlier, while microinverter shipments fell to 1.42m from 1.77m.
The same credit is the whole of SolarEdge's celebrated margin repair. Its own quarterly filing says that without the Section 45X incentive, gross profit would have become a gross loss, and its best quarter in three years leaned on $13.3m of tariff refunds and a 36% sequential jump in Europe, not the US.
The market has now stopped distinguishing between them: both trade near 6x trailing gross profit, against roughly 14.6x and 16.1x in May, even though one company's gross profit fell 35% and the other's tripled.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
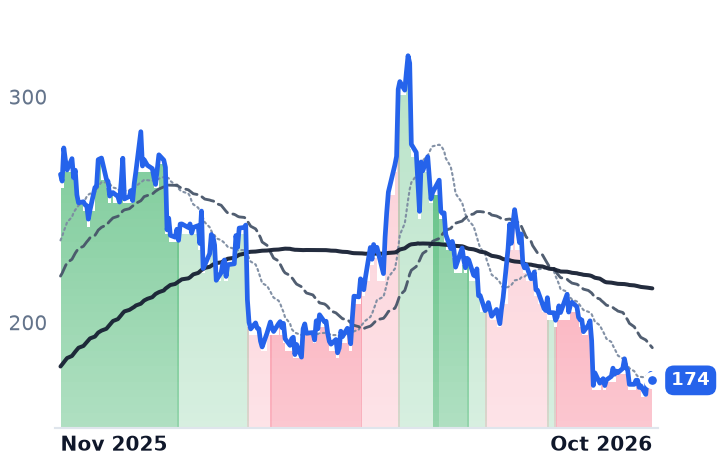
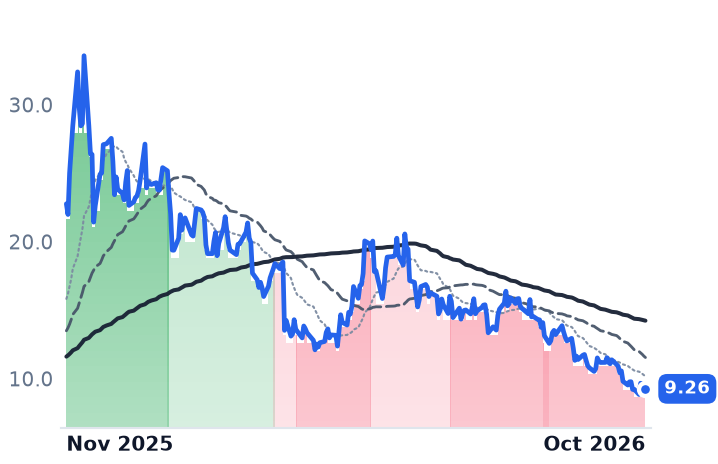
ENPH | Enphase Energy | Inverters & Optimization | 🔴 Cont. Bear | −23.4% | −13.1% |
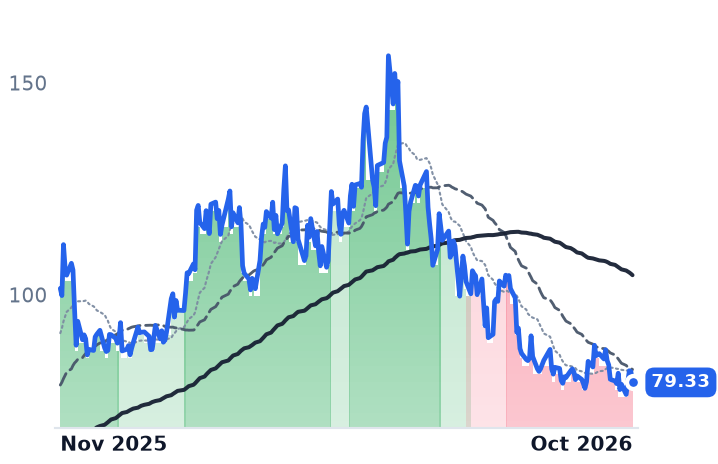
SEDG | SolarEdge Technologies | Inverters & Optimization | ⚠️ Emerging Bear | −9.2% | −8.6% |
| Compared against · context, not the story | |||||
RUN | Sunrun | Residential Services | 🔴 Cont. Bear | −3.0% | −62.5% |
CWEN | Clearway Energy | Diversified Generators | 🔴 Cont. Bear | +9.2% | +1.0% |
FSLR | First Solar | Modules | 🔴 Cont. Bear | −0.1% | −34.4% |
NXT | Nextpower | Tracking Systems | 🔴 Cont. Bear | −5.9% | −21.8% |
ARRY | Array Technologies | Tracking Systems | 🔴 Cont. Bear | −16.9% | −59.7% |
SHLS | Shoals Technologies | Balance Of System | ⚠️ Emerging Bear | −13.3% | −30.4% |
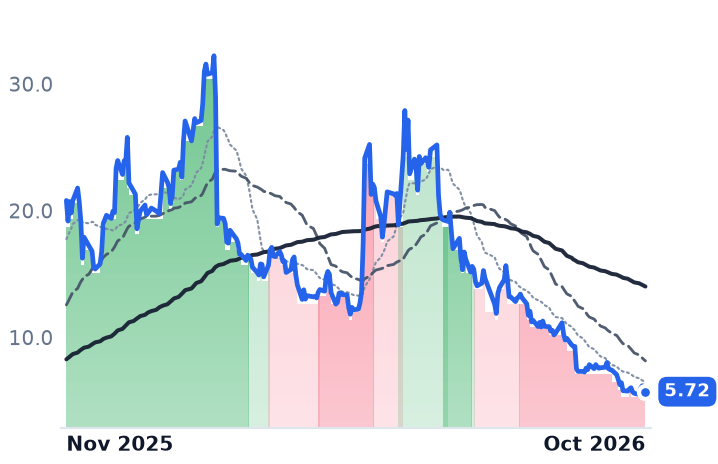
CSIQ | Canadian Solar | Modules | 🔴 Cont. Bear | −17.2% | −59.3% |
FLNC | Fluence Energy | Energy Storage | 🔴 Cont. Bear | −24.8% | −72.5% |
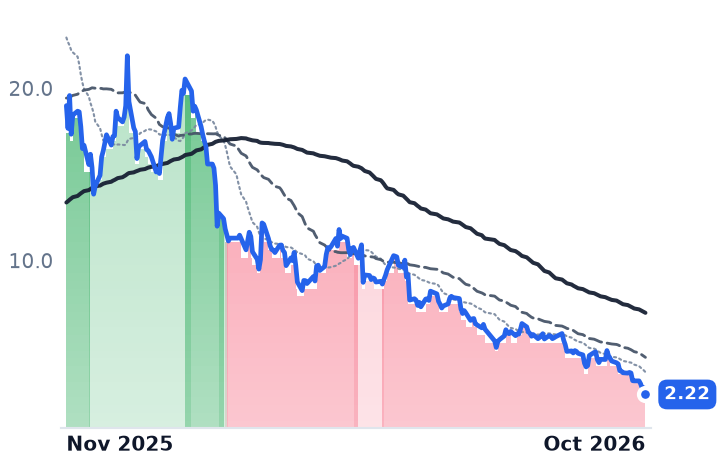
STEM | Stem | Renewable Utilities | 🔴 Cont. Bear | −47.9% | −88.3% |
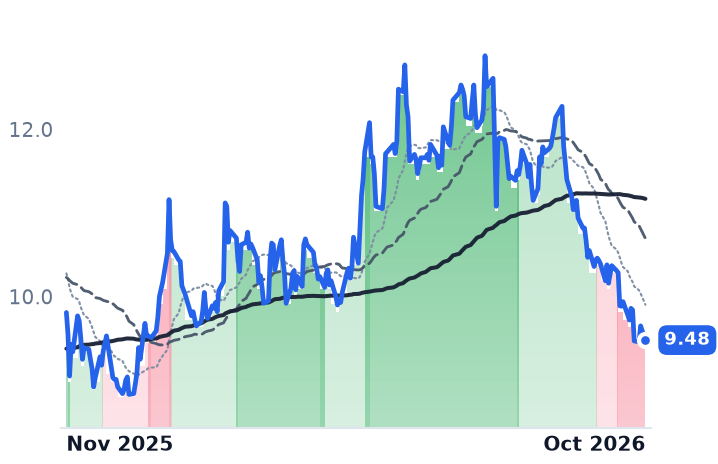
XIFR | XPLR Infrastructure | Infrastructure Investor | ⚠️ Emerging Bear | −8.8% | −3.4% |
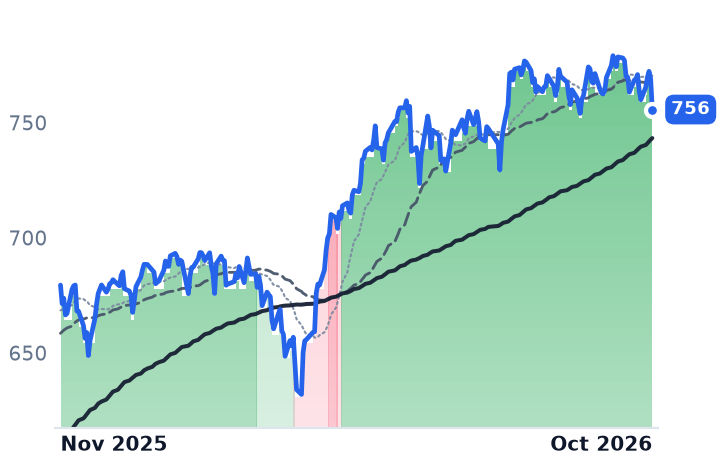
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | −1.8% | +11.2% |
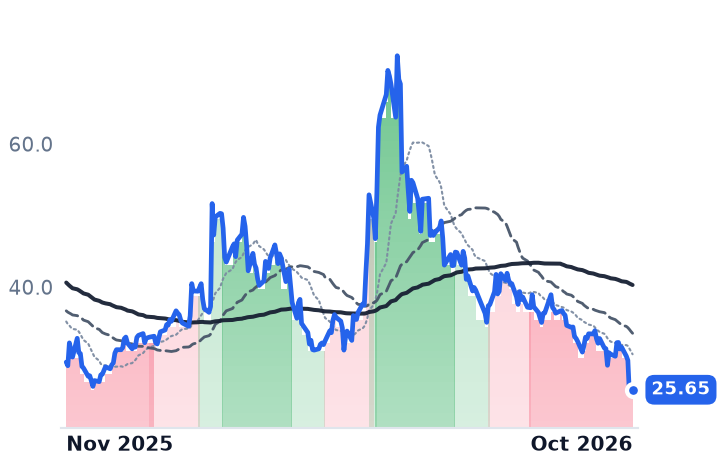
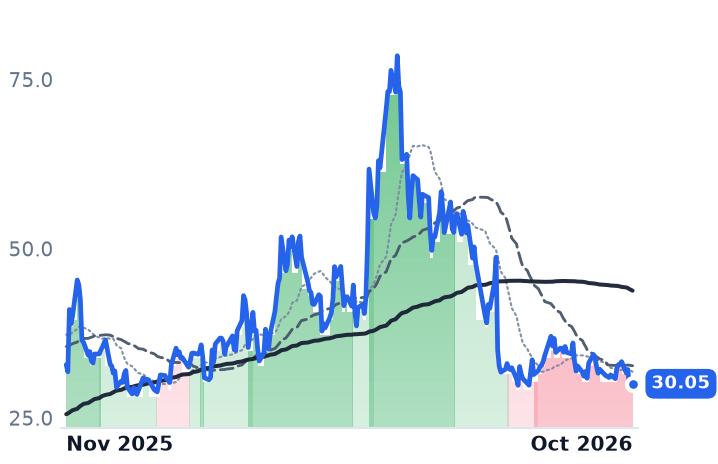
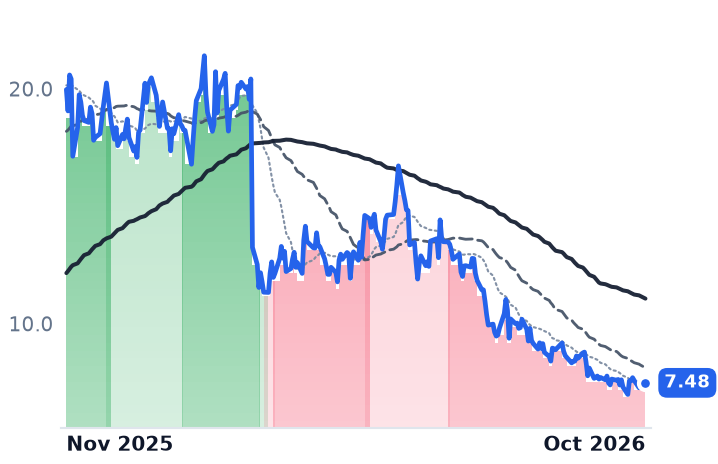
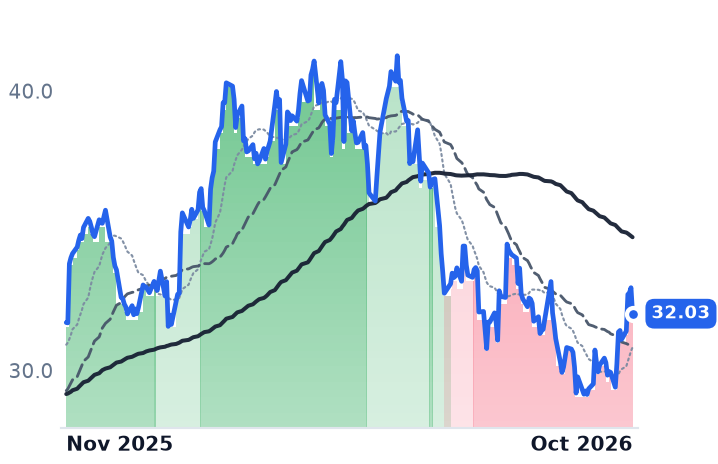
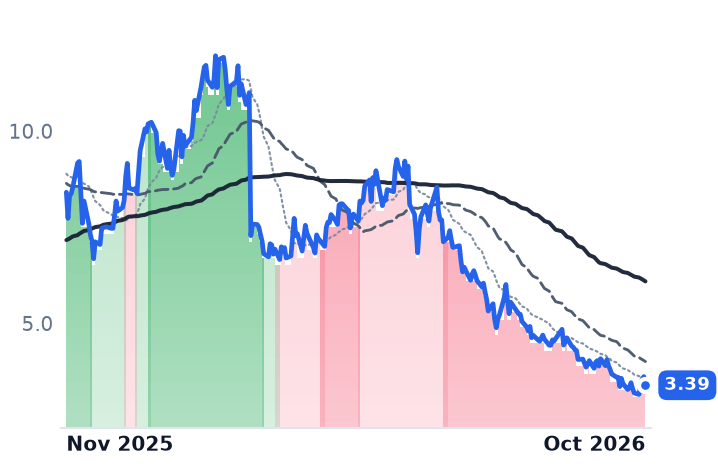
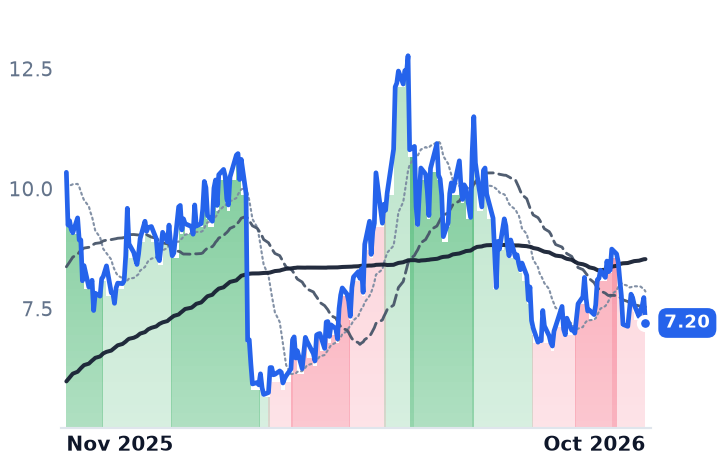
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ENPH | $3.4B | 37.2x | 15.1x | 2.8x | 3.0x | 6.1x | 6.6x | 25.7x | 4.0% |
SEDG | $1.8B | n/m | — | 1.4x | 1.4x | 6.3x | 6.4x | n/m | 4.9% |
RUN | $1.8B | 4.4x | 6.2x | 0.5x | 0.6x | 1.5x | 1.7x | 18.4x | -75.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CWEN | $6.5B | 41.4x | — | 4.1x | 3.9x | 7.7x | 7.4x | 13.8x | 10.4% |
FSLR | $19.1B | 10.9x | 10.1x | 3.6x | 3.8x | 8.1x | 8.6x | 7.2x | 7.9% |
NXT | $14.9B | 24.7x | 21.2x | 4.1x | 3.5x | 12.3x | 10.4x | 18.3x | 3.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ARRY | $589.2M | n/m | 5.1x | 0.5x | 0.4x | 2.0x | 1.7x | 248.5x | 22.9% |
SHLS | $1.4B | 45.8x | 21.0x | 2.5x | 2.3x | 7.7x | 7.2x | 23.5x | -3.6% |
CSIQ | $866.4M | n/m | — | 0.2x | 0.1x | 1.1x | 0.9x | 79.4x | -182.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FLNC | $1.4B | n/m | — | 0.5x | 0.4x | 5.8x | 4.7x | n/m | -9.4% |
STEM | $42.7M | n/m | — | 0.3x | 0.3x | 0.8x | 0.7x | n/m | 13.6% |
XIFR | $972.0M | 15.4x | 8.6x | 0.8x | 0.7x | 4.7x | 4.2x | 8.5x | -65.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ENPH | Revenue | −23.6% | −8.6% | +16.3% |
| EPS | −39.5% | −18.1% | +34.3% | |
SEDG | Revenue | +10.4% | +9.7% | +13.5% |
| EPS | −85.3% | −313.9% | +112.5% | |
RUN | Revenue | +27.9% | +2.6% | +12.9% |
| EPS | −11.4% | −54.4% | +7.2% | |
CWEN | Revenue | +13.9% | +12.1% | +13.2% |
| EPS | −104.5% | −951.7% | +33.6% | |
FSLR | Revenue | −1.7% | +17.1% | +11.7% |
| EPS | +20.3% | +33.1% | +26.2% | |
NXT | Revenue | +22.3% | +22.3% | +18.0% |
| EPS | +13.8% | +6.1% | +21.9% | |
ARRY | Revenue | +13.2% | +11.9% | +5.3% |
| EPS | +12.5% | +17.9% | +9.7% | |
SHLS | Revenue | +32.7% | +9.1% | +11.0% |
| EPS | +5.1% | +27.4% | +16.3% | |
CSIQ | Revenue | +2.6% | +21.0% | +0.2% |
| EPS | +49.6% | −142.0% | +234.3% | |
FLNC | Revenue | −2.5% | +29.2% | +23.8% |
| EPS | +277.1% | −76.7% | −169.5% | |
STEM | Revenue | +0.1% | +17.5% | +22.8% |
| EPS | +31.7% | −14.2% | −45.1% | |
XIFR | Revenue | +0.8% | +4.7% | +1.3% |
| EPS | −889.4% | −39.7% | −94.7% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Enphase Energy, which makes module-level microinverters, alternating-current batteries and the Enlighten monitoring service and sells through solar distributors and installers, shipped 1.42m microinverters in the September quarter and reported $127.1m of gross profit on them. Its quarterly filing for the period ended 30 September shows $58.6m of that figure was the Section 45X advanced manufacturing production credit, which pays $0.11 for every watt of alternating-current capacity built in an American microinverter plant and arrives as a reduction of cost of revenues. Take it out and a shipped watt earned the company $0.105 of gross profit, against $0.164 in the same quarter of 2025.
The first three quarters of 2026 had been read as evidence that module-level electronics could hold price through the expiry of the homeowner solar credit: reported gross margin was 43.3%, and at SolarEdge it had risen for six consecutive quarters. At the shipped unit, with the manufacturing credit removed, product economics went the other way at both. Enphase's ex-credit gross margin fell to 23.4% from 31.3%. SolarEdge's filing says that without the same credit its gross profit would have been a loss.
Nine cents inside a nineteen-cent watt
Enphase's unit disclosure for the quarter, filed with its results of 27 October, shows 655.2 MW DC shipped against 784.6 MW a year earlier, and 129.9 MWh of batteries against a then-record 195.0 MWh. Revenue fell 28.5% to $293.3m and operating income 90.2% to $6.5m. Gross profit per microinverter works out at $48.24 once the credit is stripped, against $72.66 a year earlier. The entire $23.4m of reported net income came from a roughly $27.0m income tax benefit sitting on a pretax loss of about $3.6m.
All three variables are guided lower together. Fourth-quarter revenue is set at $225–255m including roughly $51m of safe-harbor revenue, batteries at 100–120 MWh, and non-GAAP gross margin at 40–43% from 45%. Global sell-through, flat near $230m a quarter all year, is expected to fall about 10% to around $210m, and Enphase intends to ship some $20m below even that to drain distributor stock. US battery prices were cut 8–9%.
"We are not seeing any meaningful recovery in the U.S. demand," chief executive Badrinarayanan Kothandaraman told investors on 27 October.
The person claiming the subsidy changed
Section 25D, the residential credit, expired for expenditures after 31 December 2025, taking 30% of system cost away from anyone paying cash or borrowing. What survives is the Section 48 commercial credit, claimable only by a third-party owner, and third-party ownership's share of US residential volume rose from 40% to 52% during 2024 with 60–65% projected on exit from this quarter. Borrowing got no easier: the Federal Open Market Committee held at 3.75–4.00% on 28 October with the average 30-year fixed mortgage at 7.33%, up from 7.12% a month earlier. Enphase's US residential sell-through fell about 35% year on year. Its Propel lease programme now runs in 13 states with more than 350 installers and a 71% battery attach rate, but the equipment revenue from those originations is expected in the first half of 2027.
One sentence in SolarEdge's filing
SolarEdge, the Herzliya-based maker of DC-optimized inverters and power optimizers, grew June-quarter revenue 19.6% to $346.2m and lifted GAAP gross margin to 27.5% from 11.1%, its first non-GAAP operating profit since mid-2023. The composition undercuts the direction. Its 10-Q states that excluding the same manufacturing incentives would have caused gross profit "to transition from a gross profit to a gross loss," and the 28.6% non-GAAP figure included $13.3m of tariff refunds. Europe, up 36% sequentially to $154.4m, drove the quarter; the US slipped 2%. Third-quarter guidance is $310–340m on 22–26% margin, and the results land on 4 November.
A premium that closed in one session
Enphase fell 16.0% on 28 October and 22.3% over the 30 days to 30 October; SolarEdge fell 8.3% that day on a rival's numbers. First Solar, Nextracker and Array Technologies all rose the same session, which argues against a sector-wide repricing.
The de-rating is doing most of the work the results ask of it. Enphase trades at 6.12x trailing gross profit, rising to 6.62x forward because the denominator is shrinking faster than the price, against 14.55x in May. SolarEdge sits at 6.26x against 16.09x then.
So the two now carry effectively the same price against gross profit, though Enphase's fell 35.2% year on year and SolarEdge's tripled. That is a judgment that neither company's margin is its own: both are priced off the durability of one federal credit rather than off the trajectory of the product. It fits the numbers better than it fits the narratives. Enphase still earns 23.4% at the gross line without help, on consensus revenue the Street sees falling a further 8.6% in 2027 to $1.02bn, which puts the stock near 18.5x the $1.39 of earnings expected that year. SolarEdge, on its own disclosure, does not clear zero without the credit at all. Oppenheimer's Colin Rusch, cutting Enphase to Perform, wrote that a recovery in the core business "is not materializing".
The credit that is holding both income statements up has a schedule. Section 45X pays in full through 2029, then steps down each year and pays nothing for product sold after 2032. Residential inverter makers have until then to make a watt worth shipping on its own.