

This Year's Bankruptcies Are Too Small to Pay FTI Consulting's Restructuring Bills
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Litigation and restructuring advisers are paid by the hour, and the hours are not following the filings. Commercial Chapter 11 cases ran 11% ahead of last year through September, yet FTI Consulting's Corporate Finance & Restructuring utilization fell to 58% from 63% and the Restructuring line inside that segment shrank 1% year on year.
FTI still crossed $1bn of quarterly revenue for the first time on 29 October, with adjusted EBITDA at 15.2% of revenue against 13.7%. The lift came from a record $40.7m of success fees, a lower tax rate, the end of the Compass Lexecon dislocation and a diluted share count down to 27.0m from 31.8m; chief executive Steve Gunby normalized the $3.84 of adjusted earnings per share to roughly $2.90 himself.
CRA International, the purer litigation-economics exposure, has published nothing since 6 August and reports on 5 November.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
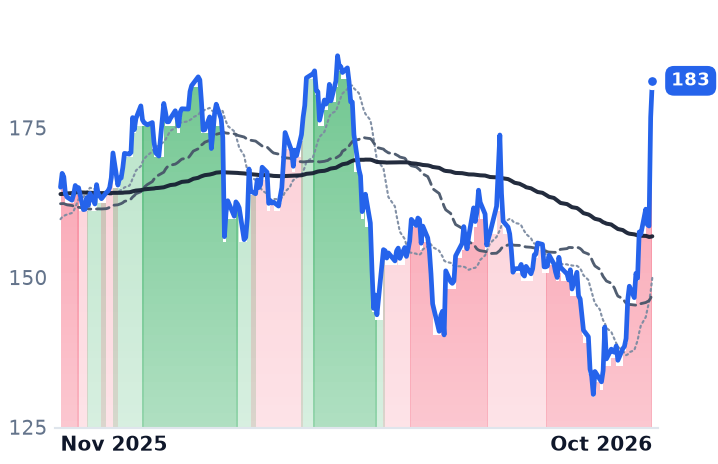
FCN | FTI Consulting | Litigation & Forensic Advisory | 🔴 Cont. Bear | +34.0% | +10.8% |
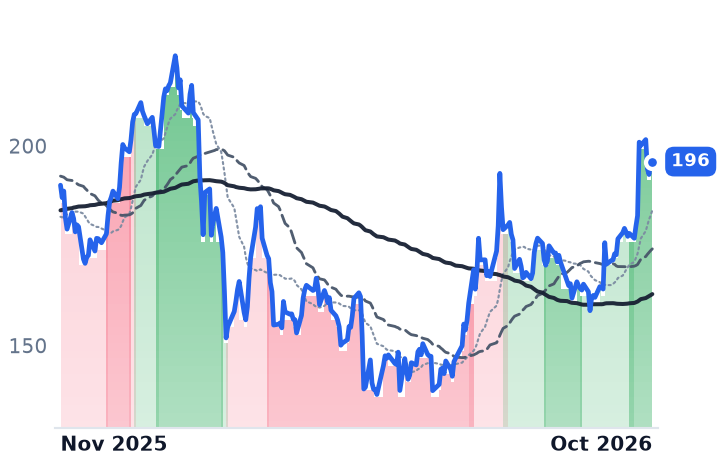
CRAI | CRA International | Litigation & Forensic Advisory | 🟢 Cont. Bull | +15.1% | +3.1% |
| Compared against · context, not the story | |||||
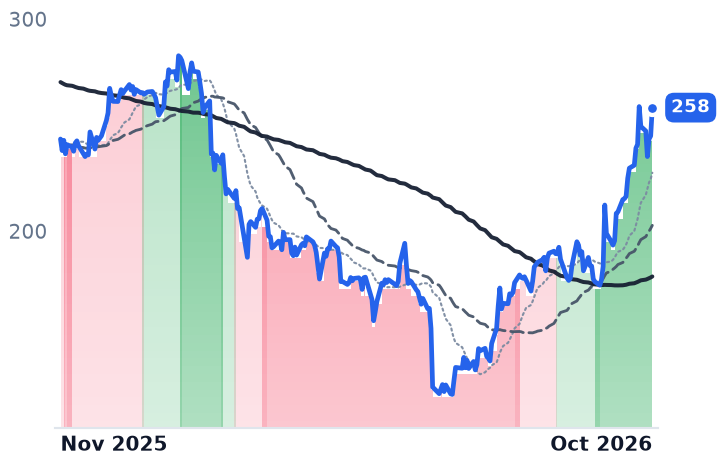
ACN | Accenture | Consulting & Professional Services | 🌱 Emerging Bull | +29.8% | +6.1% |
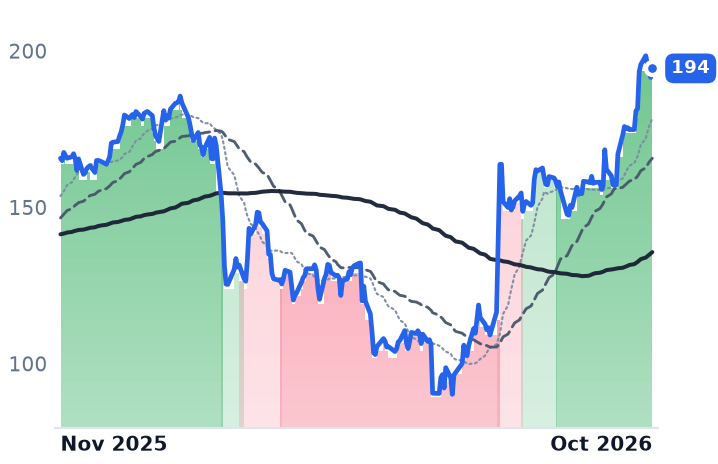
HURN | Huron Consulting | Financial & Operations Consulting | 🌱 Emerging Bull | +19.9% | +17.3% |
EXPO | Exponent | Professional Services | 🌱 Emerging Bull | +19.3% | +12.3% |
ICFI | ICF International | Government & Policy Advisory | 🟢 Cont. Bull | +16.6% | +21.4% |
MMS | Maximus | Professional Information & Advisory | 🔴 Cont. Bear | +21.0% | −22.6% |
NSP | Insperity | Payroll & HCM Platforms | 🟢 Cont. Bull | +4.7% | +12.9% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FCN | $5.0B | 23.1x | 18.9x | 1.3x | 1.2x | 3.9x | 3.9x | 14.7x | 8.0% |
CRAI | $1.2B | 25.8x | 23.2x | 1.5x | 1.5x | 5.8x | 5.6x | 13.2x | -2.3% |
ACN | $149.0B | 17.8x | 16.6x | 2.0x | 1.9x | 6.3x | 6.0x | 11.3x | 7.8% |
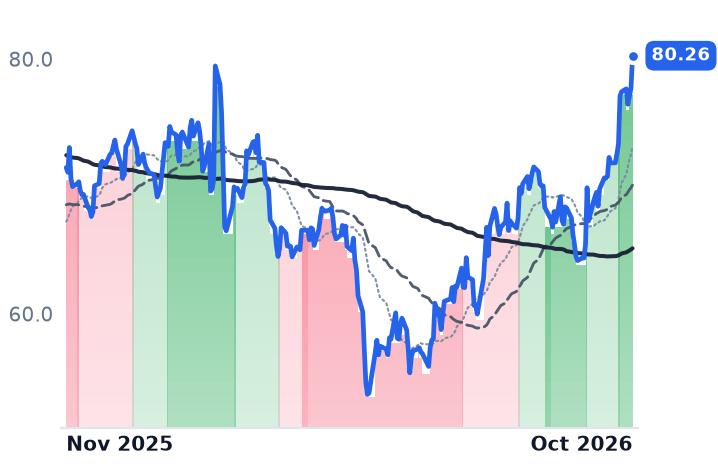
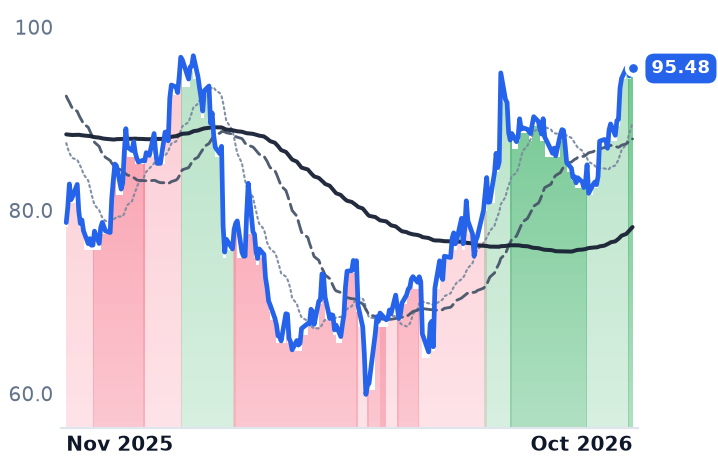
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
HURN | $2.8B | 25.7x | 19.1x | 1.5x | 1.5x | 5.1x | 4.9x | 15.5x | 5.8% |
EXPO | $3.3B | 30.2x | 29.2x | 5.2x | 5.5x | 21.0x | 22.5x | 21.4x | 3.3% |
ICFI | $1.6B | 17.8x | 12.2x | 0.9x | 0.8x | 2.4x | 2.3x | 11.2x | 12.8% |
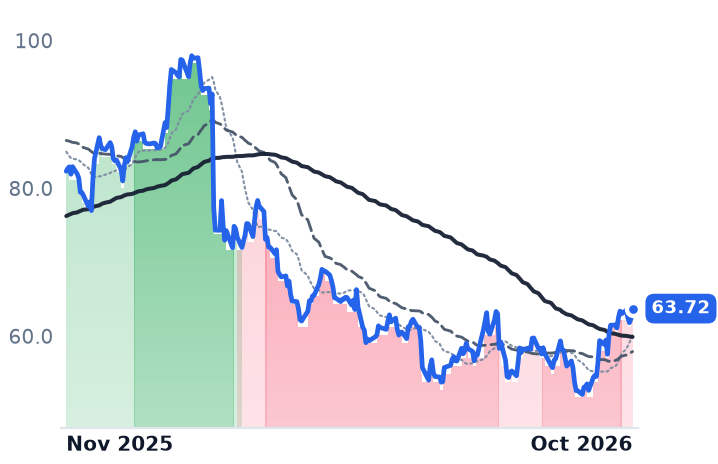
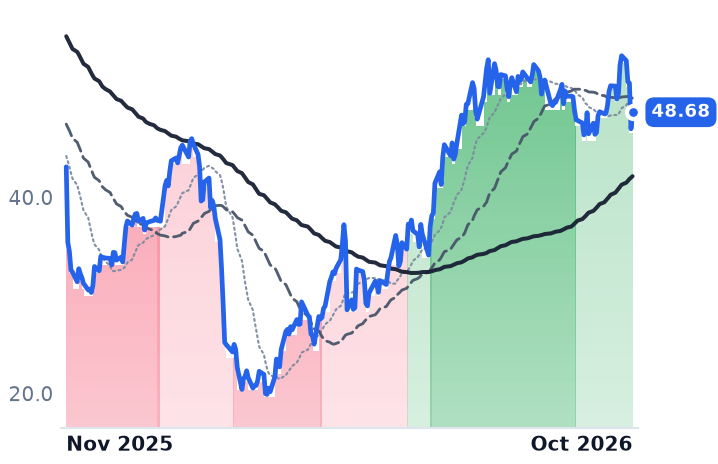
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MMS | $2.9B | 8.2x | 7.0x | 0.6x | 0.6x | 2.3x | 2.3x | 6.3x | 14.7% |
NSP | $1.9B | n/m | 23.5x | 0.3x | 0.3x | 2.2x | 2.1x | 32.5x | 14.5% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
FCN | Revenue | +7.6% | +5.8% | +5.7% |
| EPS | +13.6% | +17.0% | +9.4% | |
CRAI | Revenue | +9.9% | +9.3% | +4.0% |
| EPS | +14.9% | +2.8% | +12.9% | |
ACN | Revenue | +6.0% | +5.3% | +5.1% |
| EPS | +7.6% | +5.9% | +8.6% | |
HURN | Revenue | +12.5% | +9.0% | −5.9% |
| EPS | +20.7% | +15.1% | −3.5% | |
EXPO | Revenue | +4.1% | +10.0% | +7.5% |
| EPS | −0.3% | +12.3% | +14.0% | |
ICFI | Revenue | +1.8% | +5.9% | +8.3% |
| EPS | +5.1% | +8.5% | +6.4% | |
MMS | Revenue | −4.2% | +2.9% | +8.5% |
| EPS | +7.5% | +4.4% | +12.3% | |
NSP | Revenue | +1.2% | +4.3% | +5.2% |
| EPS | +84.8% | +27.6% | +16.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Commercial bankruptcy filings in the United States ran 11% ahead of last year through September, and FTI Consulting, the advisory firm built to staff the largest of those cases, got less work out of each consultant than it did a year earlier. Utilization in its Corporate Finance & Restructuring segment fell to 58% from 63%, and the Restructuring practice inside that segment saw revenue decline 1%.
The 29 October print was read as the distress cycle finally reaching the invoices. FTI did cross $1bn of quarterly revenue for the first time, at $1.013bn, with adjusted EBITDA margin of 15.2% against 13.7%. But the hours behind that revenue tell a different story about where advisory money is coming from, and it is not the bankruptcy docket.
Why a filing count stopped predicting a fee
The year's insolvency growth is small-company insolvency. Subchapter V small-business elections were up 46% year on year as of October, and a small-business reorganization generates a fraction of the expert hours a large case does. Meanwhile the headline series has turned: Epiq counted 6,560 commercial Chapter 11 filings through September, but September alone produced 648 against 769 a year earlier, a 16% decrease. The wave crested in the first half, when filings ran 28% ahead.
The antitrust channel has the same shape. Merger notifications reached 2,555 in fiscal 2026, the largest total since 2022, but second requests — the investigations that pay for testifying economists — numbered 41 in fiscal 2025, about 2.1% of adjusted reported deals, and in July the Justice Department's Antitrust Division published a model timing agreement meant to compress those reviews. More deals, narrower investigations, fewer hours each.
What actually paid at FTI
Corporate Finance & Restructuring revenue rose 4.8% to $424.4m on a 3.2% higher average bill rate of $550, with Transactions up 13% on success fees and Transformation up 7%. Success fees hit a record $40.7m, including a Federal Reserve Bank of Boston loan-portfolio sale. That is event income, not a recurring run rate of billed hours.
The genuine repair is at Compass Lexecon, the Economic Consulting arm, whose dislocation management says had been costing roughly $22m of EBITDA a quarter for five quarters. Revenue there rose 9.3% to $189.3m and adjusted segment EBITDA swung to $14.0m from minus $4.6m, at a $639 average rate, the firm's richest hour. "That dislocation is behind us, and the power of everything else we have been doing is once again beginning to shine through," Gunby told investors on 29 October.
Forensic & Litigation, by contrast, was flat at $195.1m on 54% utilization, record rates offsetting lost volume as US enforcement pulled back. FTI took a $46m charge for cuts touching about 4% of staff, with roughly $80m of annualized savings expected. "We believe these actions further strengthen our business and position us for sustained growth," chief financial officer Angela Nam said the same day.
CRA re-rated before it reported
CRA International, the $1.23bn Boston economics and expert-testimony firm that competes with Compass Lexecon for antitrust mandates, rose 19.5% over October with nothing published since 6 August; it reports on 5 November. Its largest day, 22 October, came as Accenture rose 7.4%, Huron 6.5% and Exponent 5.2% on a session when the Nasdaq fell 2.6% — the likelier reading is rotation into de-rated labor businesses. Its last numbers were good: revenue up 12.8% to $210.8m at 77% utilization, with guidance raised to $805m–$820m on an unchanged 12.0%–13.0% margin target, and chief executive Paul Maleh describing "peak levels of new project opportunities" on 6 August.
Still, consensus has CRA earning $8.47 for the year ending January 2027, up 2.8%, against a forward multiple that went from 19.4x to 23.2x on no news. Its trailing free cash flow yield is minus 2.3% against FTI's 8.0%, and it is the dearer of the two on price to gross profit, 5.78x versus 3.89x.
FTI's results account for about an eighth of its 36% month: the forward multiple moved from 13.9x to 18.9x while the adjusted earnings guide rose 4.3% at the midpoint, to $9.50–$10.00. And the earnings that justified it are mostly not hours. Gunby normalized the quarter's $3.84 of adjusted earnings per share to roughly $2.90 after success fees and a tax rate near 22%, while buybacks took the diluted share count to 27.0m from 31.8m the prior quarter. The one durable gain is Compass Lexecon's return, which management frames as a five-year recovery to historical profitability.
What both firms are really defending is the named expert. FTI promoted 100 senior managing directors and hired more than 140 laterals over two years, which is why its rates can set records while its utilization falls. Paying up for experts works when the cases are big enough to keep them busy, and this year's cases are getting smaller.