

Prologis Raised Its Rent Outlook Into the Selloff; Rexford Alone Guides Rents Down
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Industrial landlords have been sold since the summer as though distribution demand were rolling over. All three of the big warehouse owners that reported in October raised full-year guidance instead, and the only decline in rents disclosed anywhere in the group belongs to Rexford's Southern California cash roll — whose shares are the only ones in the set up over the past month.
Prolologis signed 60m square feet of leases in the quarter. EastGroup lifted funds from operations guidance to $9.65 a share on record second-generation leasing at 21% cash spreads. Rexford's chief financial officer guided cash re-leasing spreads to negative low-to-mid teens for the next two years.
The drawdown prices off the discount rate rather than the rent roll: the ten-year Treasury yield reached 5.27%, and Prologis's extra fall traces to how it funded a £14bn acquisition in Europe.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
PLD | Prologis | Industrial Logistics | ⚠️ Emerging Bear | −4.9% | +2.2% |
REXR | Rexford Industrial Realty | Industrial Logistics | 🌱 Emerging Bull | +3.0% | −7.7% |
EGP | EastGroup Properties | Industrial Logistics | ⚠️ Emerging Bear | −1.8% | +13.4% |
FR | First Industrial Realty Trust | Industrial Logistics | ⚠️ Emerging Bear | −9.4% | −0.1% |
TRNO | Terreno Realty | Industrial Logistics | ⚠️ Emerging Bear | −1.7% | +9.7% |
| Compared against · context, not the story | |||||
STAG | STAG Industrial | Single-Tenant Industrial | ⚠️ Emerging Bear | −1.6% | −3.1% |
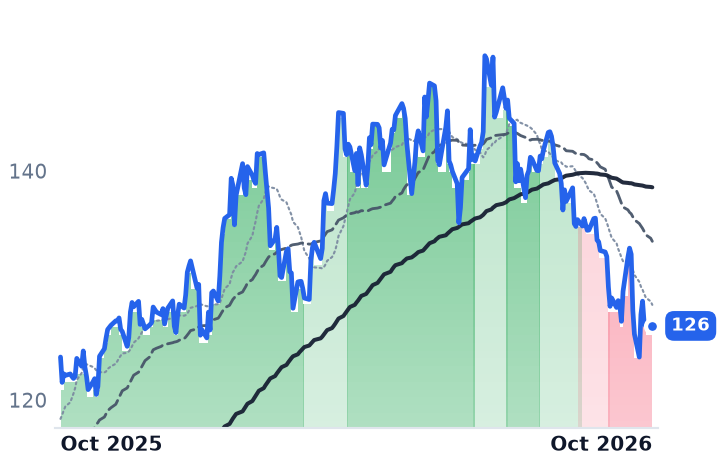
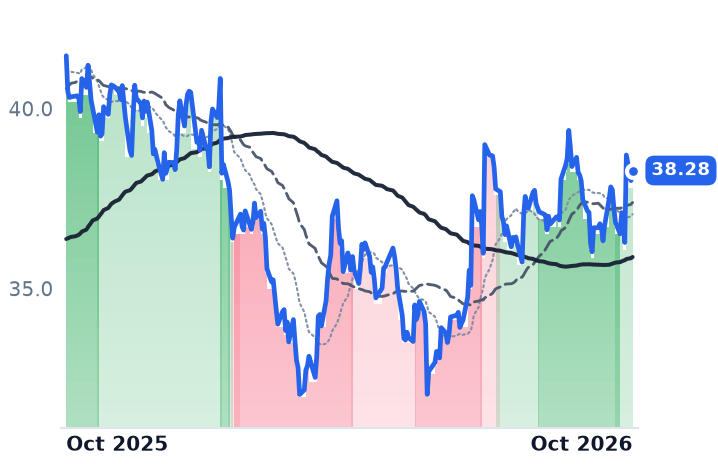
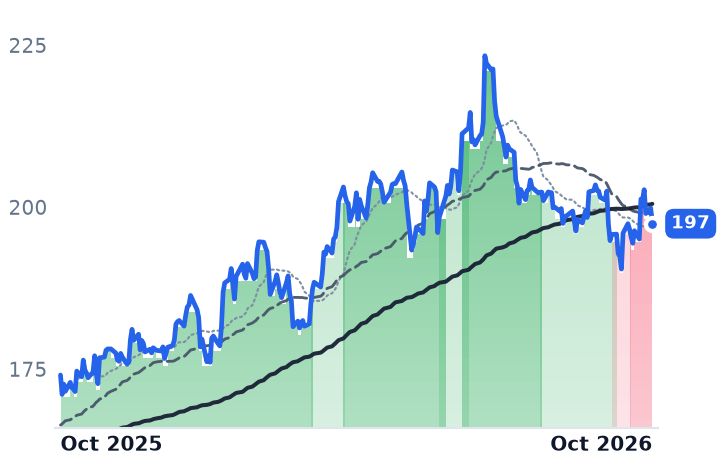
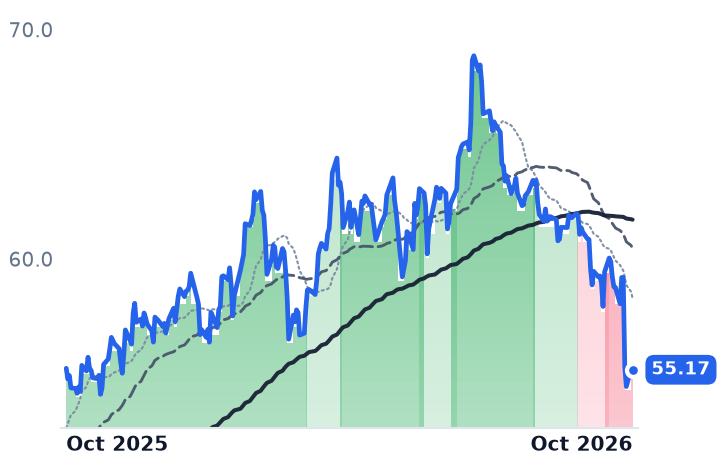
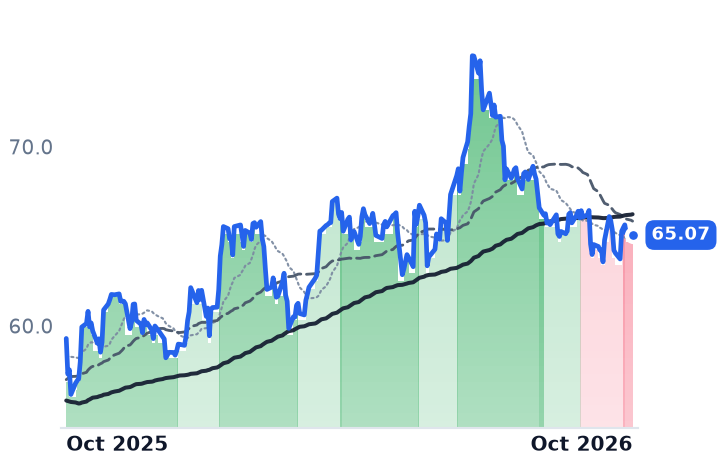
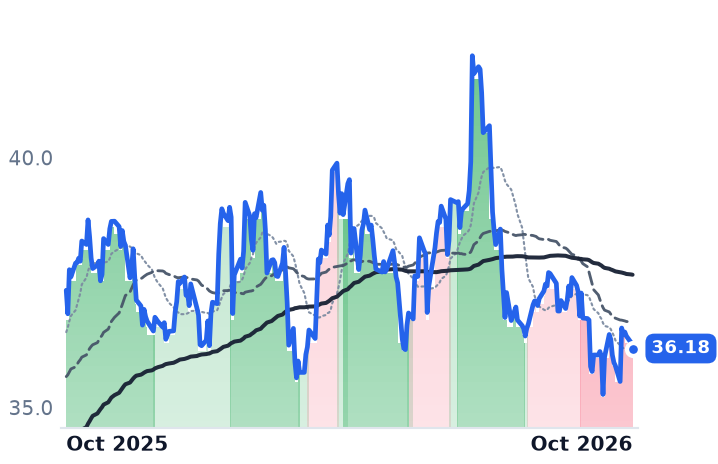
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PLD | $120.2B | 27.9x | 33.7x | 12.8x | 13.9x | 59.2x | 64.3x | 18.1x | 3.2% |
REXR | $8.8B | n/m | — | 9.0x | 9.3x | 14.9x | 15.3x | n/m | 3.0% |
EGP | $10.6B | 33.4x | 32.8x | 13.8x | 13.5x | 26.5x | 26.0x | 21.6x | 2.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FR | $7.3B | 20.4x | 21.7x | 9.4x | 9.3x | 19.5x | 19.3x | 14.2x | 4.4% |
TRNO | $7.1B | 17.5x | 30.8x | 14.1x | 13.9x | 21.9x | 21.6x | 15.3x | 2.6% |
STAG | $6.9B | 27.6x | 32.7x | 7.9x | 7.6x | 12.7x | 12.3x | 14.5x | 6.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
PLD | Revenue | +5.8% | +12.0% | +7.9% |
| EPS | +36.3% | −11.3% | +9.6% | |
REXR | Revenue | −4.5% | −5.7% | +1.2% |
| EPS | −199.2% | −197.5% | +4.6% | |
EGP | Revenue | +9.4% | +9.5% | +8.3% |
| EPS | +22.7% | −4.8% | +9.9% | |
FR | Revenue | +8.6% | +6.3% | +6.5% |
| EPS | +51.7% | −25.0% | +4.5% | |
TRNO | Revenue | +7.8% | +11.7% | +16.6% |
| EPS | −41.2% | −14.6% | +10.5% | |
STAG | Revenue | +8.2% | +6.3% | +7.4% |
| EPS | −11.2% | +0.5% | −0.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Every warehouse landlord that reported in October raised its full-year forecast. Prologis, the world's largest owner and developer of distribution space, took core funds from operations guidance to $6.25–6.29 a share on 15 October and lifted same-store cash growth to 7–7.5%. EastGroup Properties, which builds and leases shallow-bay Sunbelt space of roughly 15,000 to 70,000 square feet, went to $9.65 a share on 22 October. Rexford Industrial, which owns 419 properties and about 51.2m square feet exclusively in infill Southern California, raised its core midpoint by two cents on 23 October.
All three had already been marked down. Over the three months to 27 October, Prologis fell 14.1%, First Industrial 17.0%, Terreno 10.9% and EastGroup 6.4% — a drawdown read as the goods-movement economy turning down and dragging distribution rents with it. What the quarter disclosed is close to the reverse: rent on rollover, occupancy and development yields all moved the landlords' way, and the single rent decline anyone put in guidance belongs to the one name whose shares rose.
Prologis signed more space and raised its starts
Prolologis earned $1.60 of core funds from operations per diluted share against $1.49 a year earlier, signed 60m square feet of leases adding $85m of incremental net operating income at a 38% net-effective roll-up, and held occupancy at 95.6%. It disclosed a 16% lease mark-to-market worth $780m of embedded income, and raised development starts to $6–6.75bn. The reason is supply. "Today, the rents needed to justify new construction have expanded to 27% above current market levels," chief executive Dan Letter told investors on 15 October. "That leaves meaningful room for rents to grow before new supply makes economic sense."
Prolologis's deeper fall is traceable to how it is paying for Europe. It raised $2.4bn of common equity in the quarter toward the £14bn SEGRO combination, which shareholders approved on 28 September; the deal was negotiated with ten-year yields near 4.50% before they surged. On 27 October the UK Competition and Markets Authority asked for views on whether the purchase would harm competition. The shares trade at 18.1x trailing enterprise value to EBITDA and 2.14x book.
The one rent decline in the group is Rexford's
"Over the next couple years, we do expect cash re-leasing spreads to average in the negative low to mid teens area," chief financial officer Michael Fitzmaurice said on 23 October. "That is about a 200 basis point improvement, though, better than if we had not sold our noncore assets." That is the 2022–23 Southern California mark-to-market being handed back, and it is real.
It is also offset inside the same portfolio. Rexford leased 3.7m square feet, renewed or backfilled 87% of expiring space, and pushed same-property occupancy up 200 basis points to roughly 97%. Some 600,000 square feet of repositioning leasing adds $14m of annualized income on commencement, with about $40m more in lease-up. The company sold $1.3bn of property in the quarter, including a 22-property portfolio whose in-place rents sat 30% above market on a 2.7-year average lease term. Having bought back close to $1bn of stock, about a tenth of the shares outstanding, it trades at 1.18x book, the cheapest of the three against EastGroup's 2.97x.
Big-box asking rents fell; infill and shallow-bay turned up
Inland Empire average asking rent fell 9.9% year on year to $1.01 per square foot per month, yet vacancy there declined 50 basis points to 8.0% on 3.9m square feet of absorption, and Los Angeles direct vacancy was 6.0%. Infill Southern California rents posted their first quarterly increase since 2023.
EastGroup's portfolio splits the same way: mid-single-digit rent growth in the Carolinas, Georgia, Texas and Arizona against flat-to-negative California, which is 14% of its income. "We signed a company record of 2.9 million square feet of second generation leases during third quarter," chief financial officer Staci Tyler said on 22 October. Spreads held at 36% on a straight-line basis and 21% on cash, retention reached 79% year to date, and development starts went to a record $390m. At 32.8x forward earnings against 33.4x trailing, EastGroup is the dearest name here and the one that fell least.
So the rent roll explains none of the drawdown and the discount rate explains most of it. The ten-year Treasury yield reached 5.27% from 4.18% at the end of 2025, and listed property fell 5.7% in September against 0.6% for large-cap equities. The dispersion inside that has causes: Prologis issued equity into the move to fund an acquisition priced before it, Rexford had already taken its impairments and is retiring its own shares instead of buying buildings, and EastGroup is the one whose higher cost of capital hurts the merchant developers it bids against more than it hurts EastGroup.
Rexford built its negative-teens guide on an assumption that Southern California market rents stay flat, and quantified the sensitivity at roughly $1.5m of income for every 30 basis points the spread improves. Those rents have just risen for the first time since 2023. Whichever way the next two quarters of infill pricing go, the number that moves the stocks is being set in the Treasury market rather than in the leasing offices.