

Dutch Bros Pays for Today's Coffee Rally Two to Three Quarters From Now
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Both scaled US coffee retailers climbed about 7% over the past month, and the reading on offer is that the economics of selling a cup of coffee have turned. The cost side says otherwise. Arabica is back near $3.11 a pound with certified exchange stocks at a 27-year low, and Dutch Bros has told investors coffee prices reach its income statement two to three quarters after they move.
The duty everyone watched is settled: Washington carved coffee out of the 25% Brazil tariff. The live cap is the bean itself. Dutch Bros grew revenue 32.5% in its June quarter and raised guidance, then guided third-quarter system same-shop sales to 4%-5% as its price increases step down; its gross margin already slipped 145 basis points. Starbucks' comp is transaction-led and its North America margin widened to 13.6% from 13.3%, while it closes roughly 250 cafes.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
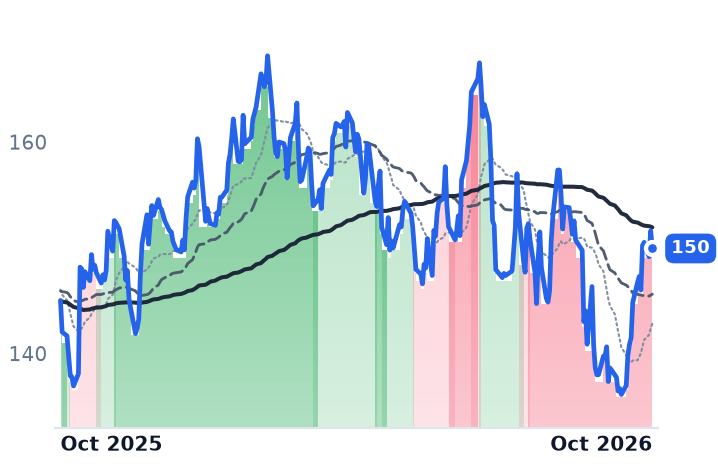
SBUX | Starbucks | Coffee & Tea Chains | 🟢 Cont. Bull | +8.3% | +20.9% |
BROS | Dutch Bros | Coffee & Tea Chains | 🔴 Cont. Bear | +8.6% | −26.9% |
| Compared against · context, not the story | |||||
MCD | McDonald's | Quick Service Restaurants | 🔴 Cont. Bear | +3.5% | −19.4% |
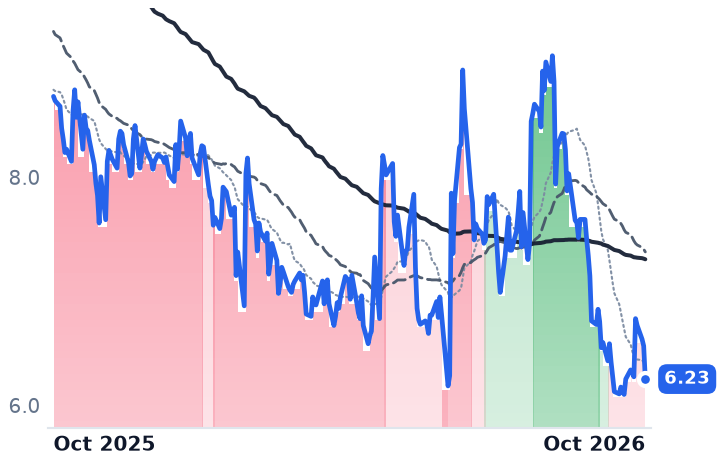
CMG | Chipotle Mexican Grill | Fast-Casual Restaurants | 🌱 Emerging Bull | −13.6% | −32.4% |
YUM | Yum! Brands | Multi-Brand QSR Operators | ⚠️ Emerging Bear | +6.6% | +3.4% |
QSR | Restaurant Brands International | Multi-Brand QSR Operators | 🟢 Cont. Bull | +4.1% | +12.6% |
WEN | The Wendy's | Quick Service Restaurants | 🌱 Emerging Bull | −7.5% | −28.5% |
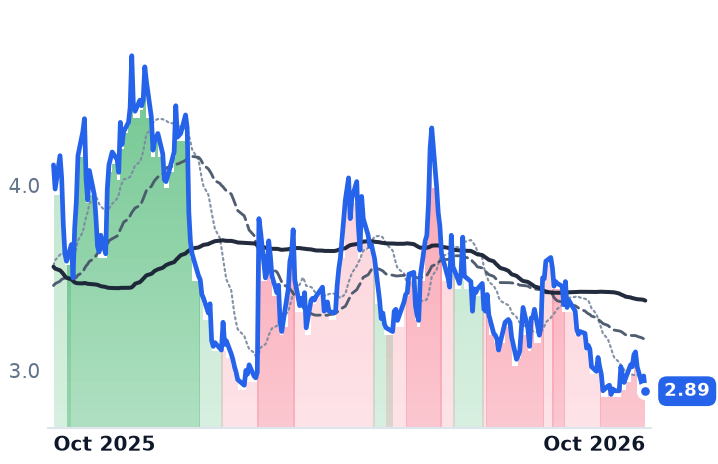
DNUT | Krispy Kreme | Specialty Treats | 🔴 Cont. Bear | −4.4% | −29.7% |
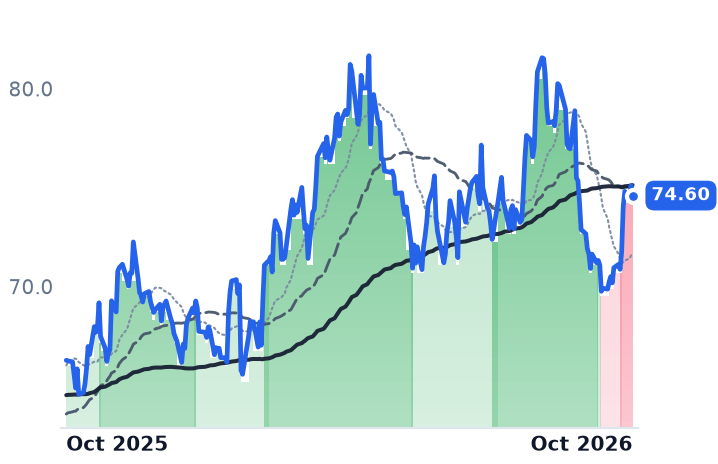
12-month price & trend
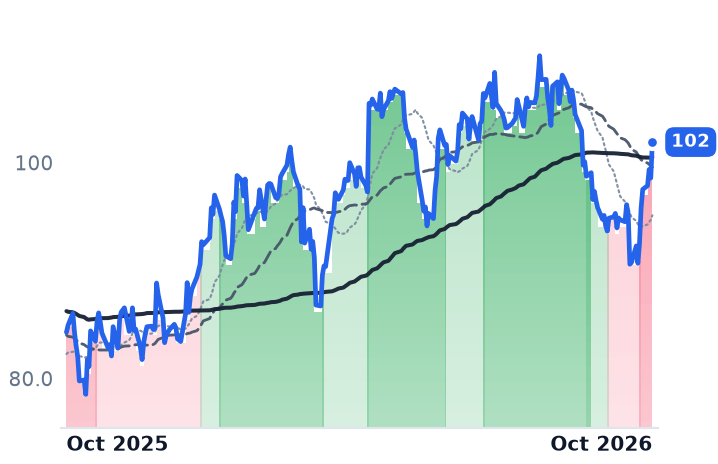
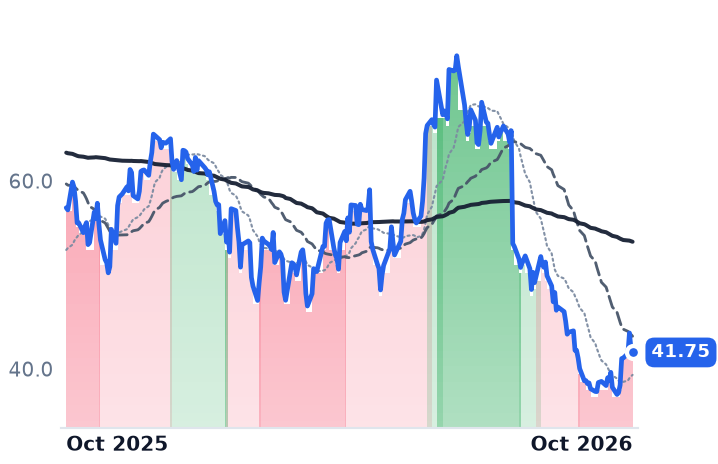
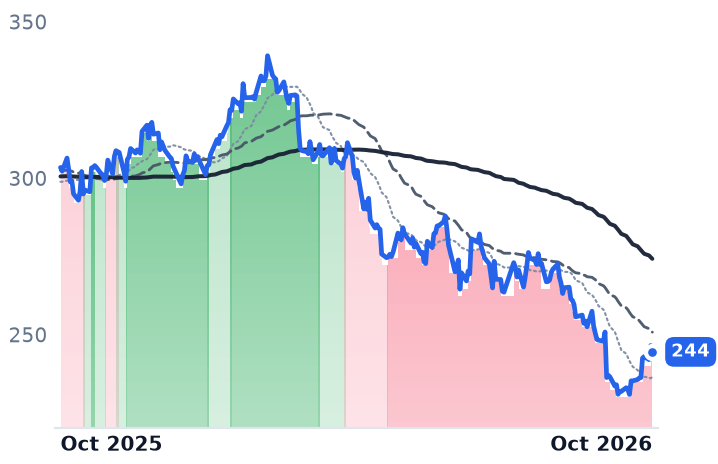
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SBUX | $116.2B | 58.6x | 32.3x | 3.0x | 3.0x | 9.5x | 9.5x | 22.8x | 3.1% |
BROS | $7.8B | 58.0x | 43.6x | 4.2x | 3.7x | 16.6x | 14.7x | 29.6x | 1.2% |
MCD | $168.0B | 19.2x | 18.3x | 6.1x | 6.0x | 10.6x | 10.4x | 14.8x | 4.6% |
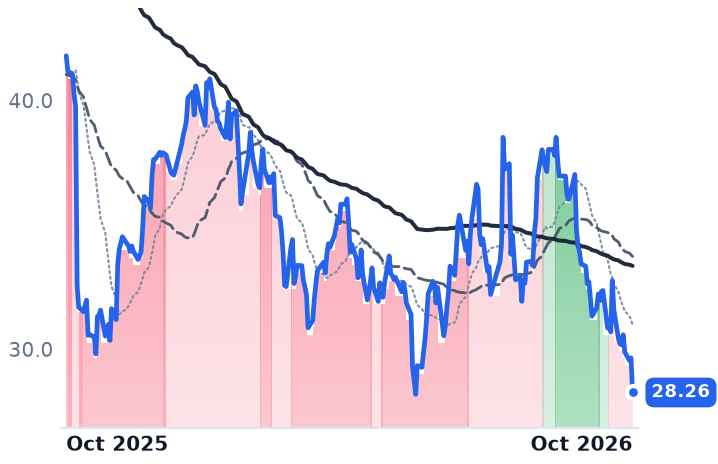
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CMG | $38.6B | 28.0x | 26.6x | 3.1x | 3.0x | 12.9x | 12.3x | 19.3x | 4.1% |
YUM | $38.0B | 17.2x | 21.0x | 4.4x | 4.3x | 9.5x | 9.3x | 17.2x | 4.4% |
QSR | $25.0B | 17.6x | 17.8x | 2.6x | 2.5x | 5.8x | 5.7x | 14.2x | 6.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
WEN | $1.2B | 9.9x | 12.9x | 0.6x | 0.6x | 2.1x | 2.1x | 10.2x | 21.2% |
DNUT | $547.0M | n/m | — | 0.4x | 0.4x | 0.8x | 0.9x | 9.6x | 6.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
SBUX | Revenue | +2.8% | +1.3% | +4.8% |
| EPS | +22.2% | +20.0% | +18.7% | |
BROS | Revenue | +31.7% | +24.4% | +21.1% |
| EPS | +39.1% | +32.3% | +26.4% | |
MCD | Revenue | +5.7% | +4.9% | +3.1% |
| EPS | +6.4% | +7.9% | +6.6% | |
CMG | Revenue | +9.5% | +10.8% | +10.2% |
| EPS | −0.4% | +19.4% | +16.1% | |
YUM | Revenue | +9.4% | +3.2% | +5.8% |
| EPS | +8.1% | +10.2% | +11.0% | |
QSR | Revenue | +5.2% | +0.5% | +0.4% |
| EPS | +10.3% | +9.1% | +9.4% | |
WEN | Revenue | +1.3% | −0.5% | +3.3% |
| EPS | −41.7% | +3.9% | +11.8% | |
DNUT | Revenue | −12.4% | +0.6% | −5.7% |
| EPS | −95.8% | −1261.5% | +14.6% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Green coffee turned back up through October, and the chain that has spelled out how long beans take to reach its income statement is the same one that has guided its comparable sales lower. Dutch Bros, the drive-thru coffee operator founded in Grants Pass, Oregon, has said that changes in coffee prices typically flow through its profit and loss account with a two-to-three-quarter delay, given inventory turns. Arabica closed near $3.11 a pound on the ICE exchange on 22 October, roughly 14% higher over thirty days.
Shares in both scaled US coffee retailers rose about 7% over that same window, and the bounce has been read as four-wall economics repairing. The disclosures support something narrower. The cost input is re-inflating while the price contribution inside Dutch Bros' comparable sales is scheduled to fade, and the duty question that was supposed to be the shared ceiling on both chains has already been resolved in their favor.
The tariff that never arrived
Green coffee was exempted from the US reciprocal tariff retroactive to 13 November 2025, and the Trade Representative's final notice spared coffee from the 25% Section 301 Brazil duty that took effect on 22 July 2026, because Brazil supplies close to a third of US green coffee imports and there is no quick substitute. The carve-out was estimated to protect $2bn to $2.5bn of Brazilian coffee exports.
What is left is physical scarcity. December arabica settled at $3.157 a pound on 19 October with stocks in ICE warehouses near a 27-year low.
A $2.2m shop against a $1.4m build
Dutch Bros' June quarter was strong on every line that matters to a unit-growth story: revenue up 32.5% to $550.9m, system same-shop sales up 5.8% on transactions up 1.7%, and guidance raised to a 5%-6% comparable range. Average unit volumes reached $2.2m with shop contribution margin near 31%, and the company opened 48 shops at roughly $1.4m of capital expenditure each, funded from $196.9m of first-half operating cash flow. No cash-on-cash return figure was disclosed; those inputs imply something in the high-40s percent on a mature shop, but that is arithmetic, not a company number.
Then the guidance for the September quarter: system same-shop sales of 4%-5%, below the quarter just delivered, on tougher transaction comparisons and a sequential step-down in effective pricing. Gross margin had already eased 145 basis points to 27.4%. Full-year guidance contemplates about 80 basis points of cost-of-goods pressure, front-loaded at roughly 200 basis points in the March quarter.
Chief financial officer Josh Guenser has called high coffee prices "the biggest headwind" the company faces, and the reason it has not reached its 30% shop-margin goal, while arguing costs should normalize. That was said on the February call, before October's rally.
Starbucks is improving four walls and removing 250 of them
Starbucks' June quarter answered the question the market asked of it. US comparable sales rose 7.9% on transactions up 4.2%, carried by traffic rather than price, and North America segment operating margin widened to 13.6% from 13.3%. Reported revenue fell 1.4% on the China deconsolidation. "The shine is back on Starbucks," chairman and chief executive Brian Niccol told CNBC on 10 September.
The estate is shrinking underneath that margin. Starbucks confirmed on 24 September it will close about 250 North America cafes against roughly $300m of restructuring charges, and cut its fiscal-2026 net new store target to about 440, all international.
Why one is expensive and the other halved
Thirty basis points of segment margin improvement, against a shrinking US unit count, is what twelve months of Starbucks' 19% share gain rests on, at 58.6x trailing earnings and 32.3x fiscal-2027 consensus of $3.16 — a figure still 12% below the $3.58 the company earned in fiscal 2023. The growth multiple is being paid for a return to a four-year-old earnings level.
Dutch Bros went the other way with better reported numbers. Revenue growth accelerated from 30.8% to 32.5% across two quarters while the shares fell 49% from their 1 July high, compressing the multiple on fiscal-2026 consensus from 76.5x to 43.6x, and 32.9x on 2027. Nothing in the results deteriorated; the pricing lever did, and the bean cost that lands two to three quarters late has started climbing again.
The October move explains itself without either store model. Starbucks fell 4.9% on 8 October on a report it had discussed a Chipotle takeover with advisers, and recovered after a spokesperson told CNBC on 12 October that "Starbucks is not buying Chipotle." Dutch Bros bounced off a 12 October low of $37.28 and was met by cuts: RBC Capital downgraded it to Sector Perform on 21 October with a $46 target, from $70, and Citigroup trimmed its target to $69 from $86 the same day.
Starbucks reports fourth-quarter and full-year results after the close on 29 October, Dutch Bros its third quarter on 4 November. Neither print will contain October's coffee price. By Dutch Bros' own description of how its inventory works, that bill arrives sometime next year.