

Intapp's Shrinking On-Premise Licenses Hide a Cloud Business Compounding at 29%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Intapp's reported revenue growth has slowed in each of the last four quarters, and the obvious reading — a vertical software vendor losing ground as artificial intelligence commoditizes what it sells — is not what its own disclosure says. The deceleration is mix. Subscription cloud revenue is compounding while the residual on-premise license and maintenance base shrinks in absolute terms, subtracting roughly 14 points of headline growth.
Cloud annual recurring revenue reached $495.7m at the end of June, and expansion inside the existing client base improved to 123% trailing-twelve-month net revenue retention from 119%. What has not improved is the bottom line: the fiscal 2026 operating loss widened to $40.1m from $27.4m.
The shares have re-rated to 6.3x sales from 4.9x in five weeks, on no new company data at all.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
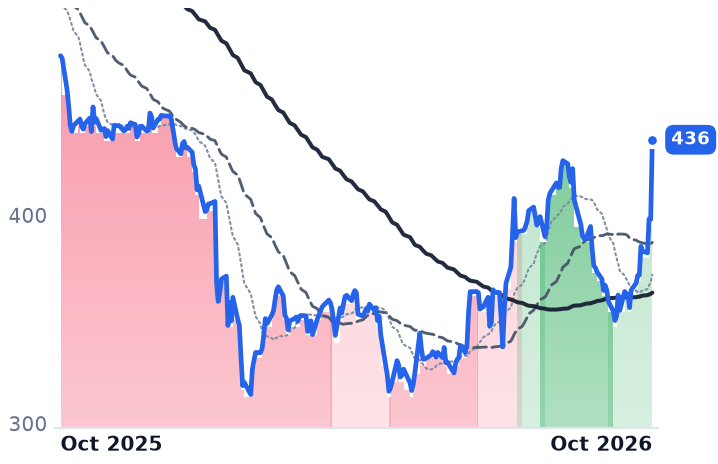
INTA | Intapp | Sales, Service & Customer Management | 🌱 Emerging Bull | +29.4% | +19.3% |
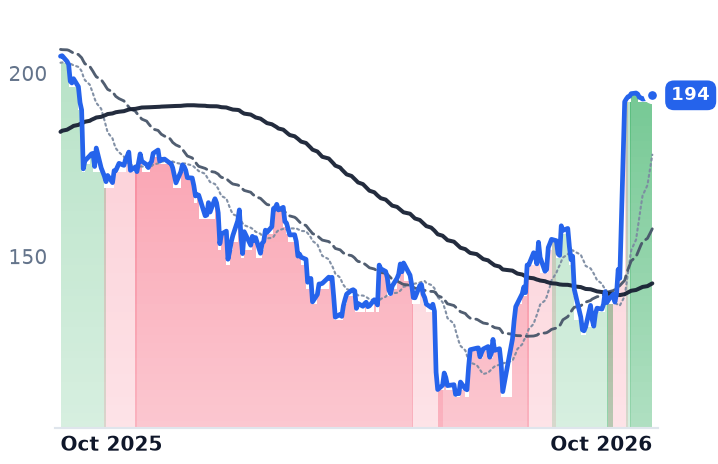
MANH | Manhattan Associates | Industry-Specific Platforms | 🟢 Cont. Bull | +15.1% | +24.4% |
APPF | AppFolio | Industry-Specific Platforms | 🌱 Emerging Bull | +3.5% | −9.3% |
NOW | ServiceNow | Sales, Service & Customer Management | 🌱 Emerging Bull | +11.5% | −16.4% |
ROP | Roper Technologies | Enterprise Resource Planning | 🌱 Emerging Bull | +19.1% | −8.5% |
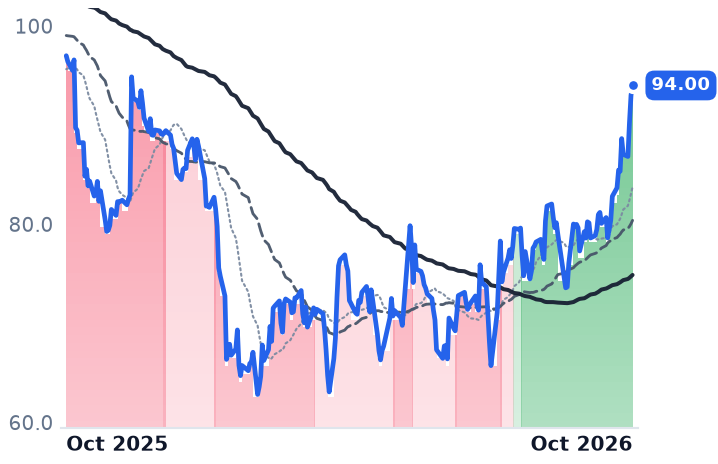
PTC | PTC | Software Development & Design | 🌱 Emerging Bull | +38.2% | −5.2% |
DSGX | The Descartes Systems | Industry-Specific Platforms | 🌱 Emerging Bull | +17.1% | −3.1% |
BLKB | Blackbaud | Industry-Specific Platforms | 🌱 Emerging Bull | +31.7% | −12.7% |
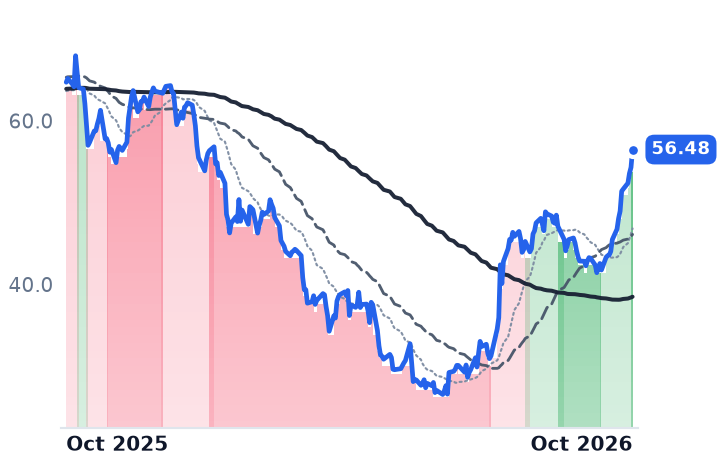
BSY | Bentley Systems, Incorporated | Software Development & Design | 🌱 Emerging Bull | +20.4% | −22.9% |
DOCU | DocuSign | Software Development & Design | 🌱 Emerging Bull | +21.5% | +18.8% |
AGYS | Agilysys | Industry-Specific Platforms | 🟢 Cont. Bull | +18.7% | +3.0% |
PCOR | Procore Technologies | Industry-Specific Platforms | 🌱 Emerging Bull | +22.0% | −15.2% |
PAR | PAR Technology | Commerce & Digital Payments | 🌱 Emerging Bull | +23.8% | −49.9% |
| Compared against · context, not the story | |||||
TYL | Tyler Technologies | Industry-Specific Platforms | 🌱 Emerging Bull | +18.0% | −24.0% |
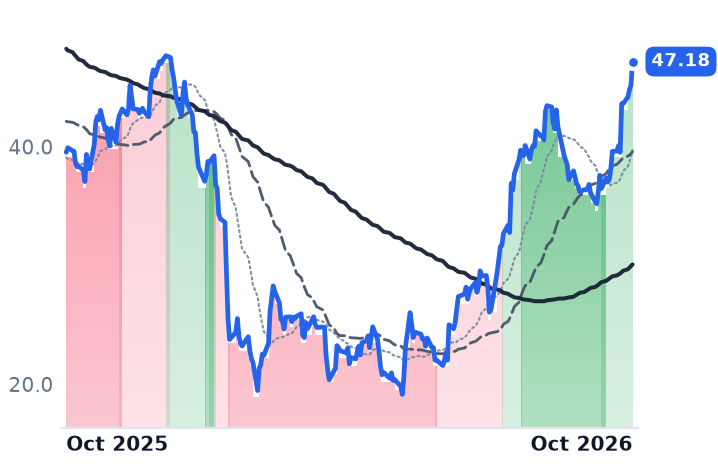
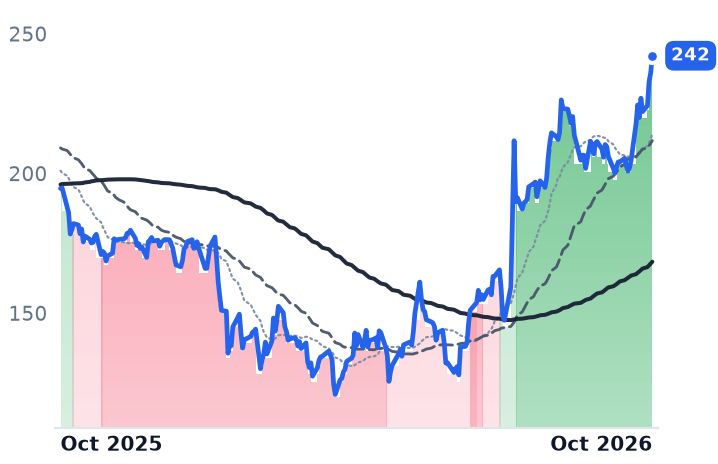
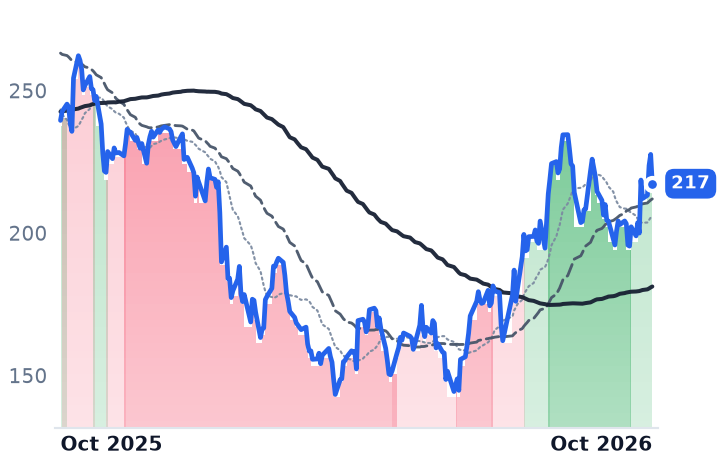
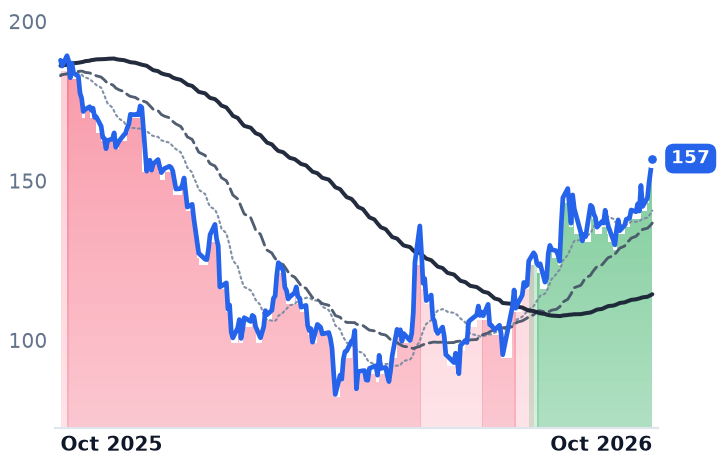
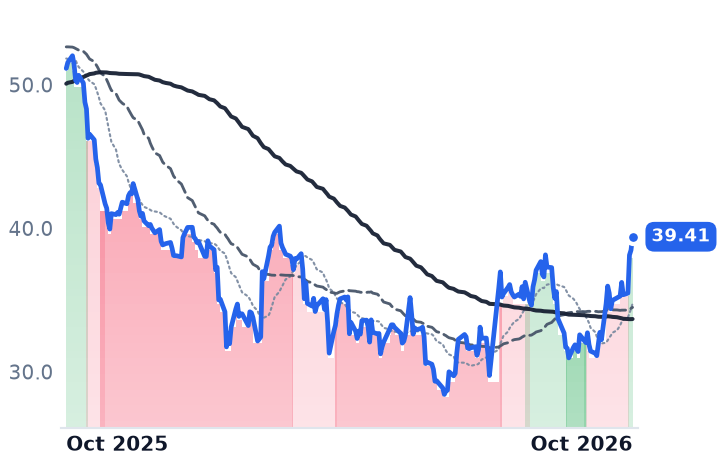
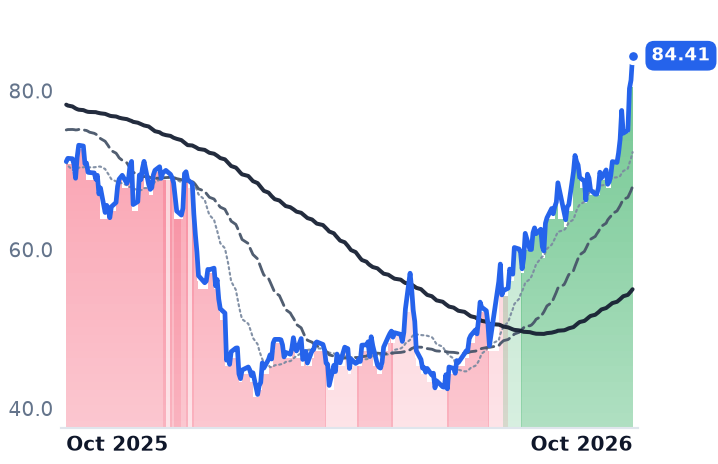
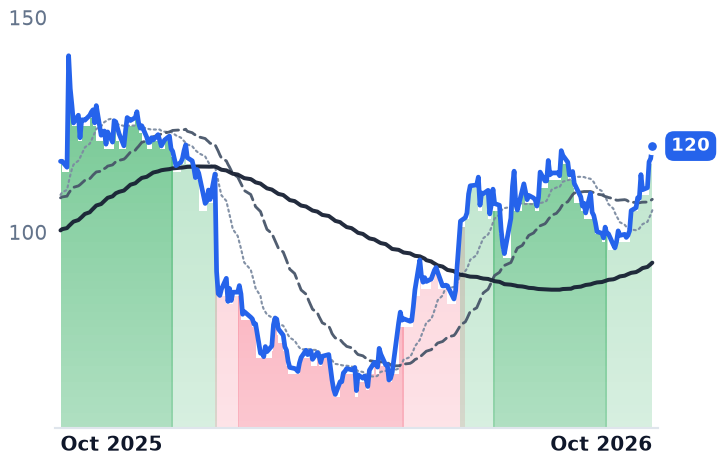
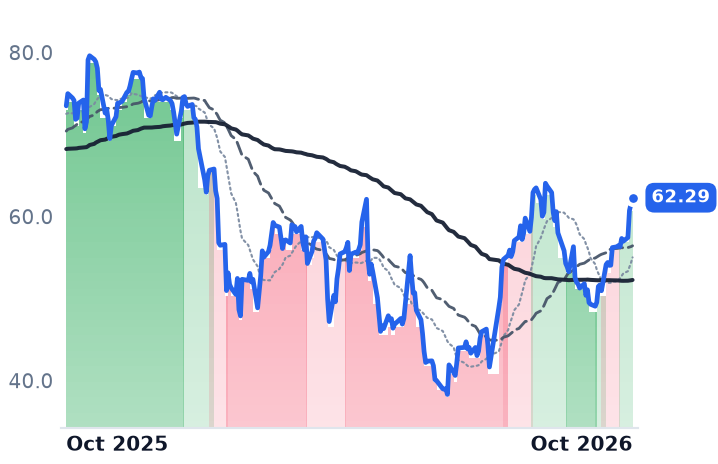
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
INTA | $3.6B | n/m | 29.5x | 6.3x | 5.5x | 8.3x | 7.2x | n/m | 3.8% |
MANH | $14.1B | 68.8x | 44.1x | 12.5x | 12.1x | 22.9x | 22.2x | 48.2x | 2.8% |
APPF | $7.7B | 45.6x | 31.5x | 7.1x | 6.8x | 11.2x | 10.8x | 32.3x | 3.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NOW | $162.3B | 97.5x | 38.5x | 11.0x | 10.0x | 14.7x | 13.4x | 48.2x | 2.8% |
ROP | $43.1B | 17.2x | 19.5x | 5.1x | 5.0x | 7.3x | 7.2x | 12.0x | 6.0% |
PTC | $21.1B | 18.7x | 21.8x | 7.1x | 7.3x | 8.5x | 8.7x | 13.3x | 4.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DSGX | $8.0B | 42.9x | 40.4x | 10.4x | 9.7x | 13.4x | 12.5x | 22.6x | 3.7% |
BLKB | $2.6B | 17.4x | 10.8x | 2.2x | 2.2x | 3.7x | 3.7x | 11.4x | 10.9% |
BSY | $11.5B | 42.8x | 28.1x | 7.1x | 6.8x | 8.7x | 8.3x | 26.2x | 4.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DOCU | $15.8B | 50.5x | 18.3x | 4.7x | 4.5x | 5.9x | 5.7x | 27.3x | 7.6% |
AGYS | $3.4B | 78.5x | 48.9x | 10.3x | 9.1x | 16.5x | 14.7x | 50.7x | 2.4% |
PCOR | $9.5B | n/m | 37.0x | 6.7x | 6.2x | 8.3x | 7.8x | 149.4x | 3.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PAR | $751.6M | n/m | 23.7x | 1.5x | 1.4x | 3.9x | 3.7x | n/m | -2.5% |
TYL | $16.1B | 51.4x | 30.0x | 6.6x | 6.3x | 14.2x | 13.5x | 29.4x | 4.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
INTA | Revenue | +14.7% | +14.6% | +15.0% |
| EPS | +36.8% | +29.9% | +22.3% | |
MANH | Revenue | +8.3% | +8.5% | +8.8% |
| EPS | +10.3% | +11.7% | +15.9% | |
APPF | Revenue | +18.5% | +17.2% | +16.9% |
| EPS | +33.9% | +22.0% | +23.5% | |
NOW | Revenue | +22.4% | +18.8% | +18.6% |
| EPS | +17.1% | +23.2% | +21.3% | |
ROP | Revenue | +8.2% | +6.0% | +5.7% |
| EPS | +12.0% | +10.1% | +7.8% | |
PTC | Revenue | +4.9% | +6.3% | +7.7% |
| EPS | +20.4% | +8.9% | +10.8% | |
DSGX | Revenue | +15.0% | +12.7% | +12.8% |
| EPS | +15.8% | +24.8% | +15.6% | |
BLKB | Revenue | +4.5% | +4.6% | +3.2% |
| EPS | +18.8% | +13.8% | −37.2% | |
BSY | Revenue | +13.6% | +10.5% | +10.2% |
| EPS | +18.5% | +12.4% | +16.3% | |
DOCU | Revenue | +8.4% | +9.2% | +8.0% |
| EPS | +6.9% | +22.1% | +12.8% | |
AGYS | Revenue | +16.5% | +16.6% | +16.9% |
| EPS | +26.9% | +49.3% | +30.3% | |
PCOR | Revenue | +15.3% | +13.9% | +14.4% |
| EPS | +24.2% | +46.2% | +19.0% | |
PAR | Revenue | +15.1% | +9.9% | +10.2% |
| EPS | +505.2% | +86.3% | +84.9% | |
TYL | Revenue | +8.7% | +10.1% | +8.8% |
| EPS | +14.7% | +17.6% | +13.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Intapp sells software to private capital firms, investment banks, law firms and accountants: DealCloud for deal and relationship management, client-onboarding and risk-monitoring compliance tools, time capture and billing. Its reported revenue grew 13.0% in the June quarter, the fourth consecutive quarter of slower growth, down from 17.0% three quarters earlier. Read on the top line alone, that is a company losing the argument about whether specialized workflow software survives generative artificial intelligence.
The company's own numbers describe something else. Cloud annual recurring revenue reached $495.7m at 30 June 2026, up 29% and now 84% of total recurring revenue against 79% a year earlier. Total annual recurring revenue rose 22% to $590.5m. The belief being tested across this corner of software — that the 2026 de-rating was a demand event — fails on Intapp's disclosure: demand inside the installed base got better, and the headline got worse, for the same reason.
The 14 points the license book is taking out
Software-as-a-service revenue grew 27% in the June quarter to $115.0m while total revenue grew 13% to $152.5m. The arithmetic of that gap is the legacy book: the on-premise license and maintenance base is in absolute decline, subtracting roughly 14 points of reported growth. Full-year revenue was $577.8m, up 14.6%. Guidance for fiscal 2027 subscription revenue is $528.7m to $532.7m.
The retention number is the one that settles whether this is managed transition or decay. Trailing-twelve-month cloud net revenue retention was 123%, improved from 119% fifteen months earlier. Existing clients are spending more per year, not less.
What a regulated vertical buys you
The reason that matters is where Intapp sells. Conflicts clearance, deal screening, lateral-hire diligence and client onboarding in law, accounting and private capital are workflows with regulatory consequences, which is the hardest ground for a general-purpose model to take. The company made Celeste, which it pitches as an "expert AI coworker," generally available in July 2026 and has since named Ropes & Gray and Forvis Mazars Capital Advisors as customers.
"We had an exceptional year advancing our Firm AI strategy, agentic capabilities with Celeste, and unique competitive position for highly regulated firms," chief executive John Hall said on 4 August 2026.
The cost side has not cooperated. Gross margin improved to 75.8% from 74.0%, but the fiscal 2026 operating loss widened to $40.1m, or -6.9% of revenue, against $27.4m a year earlier. The trailing price-to-earnings ratio of -90.7x is a byproduct of that, not a reading.
A price that moved with nothing behind it
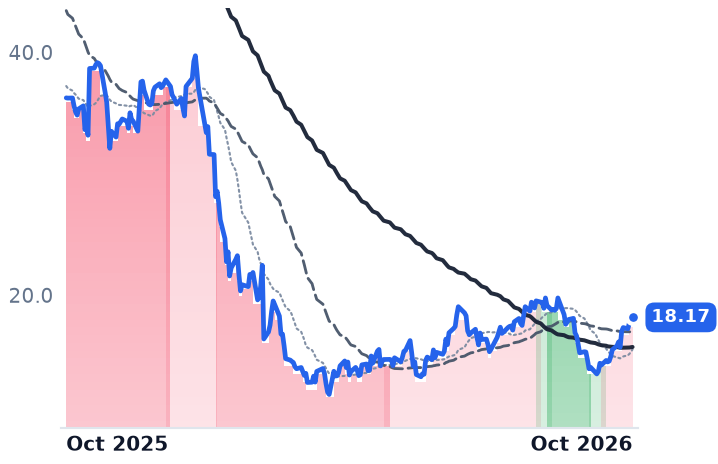
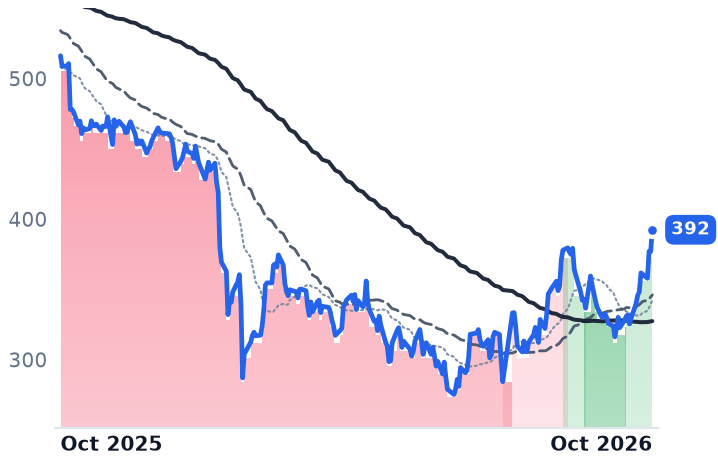
Intapp's last operating disclosure was 4 August. The stock is up 29.7% in the 30 days to 22 October and 79.6% over 90 days, and in the five weeks to 22 October its price-to-sales multiple went to 6.3x from 4.9x, with price-to-gross-profit at 8.3x against 6.4x. Nothing was published in between.
The company is not alone. Twelve of the thirteen members of its vertical-software shelf rose over those 30 days, median 21.7%, and the biggest gainer was an acquisition: PTC, the engineering software vendor, agreed on 5 October to be bought by Schneider Electric at $205 a share in cash, a 42.3% premium. The complex more broadly has been recovering from the first-quarter sell-off dubbed the "SaaSpocalypse," with software stocks reaching 2026 highs in early October as AI-disruption fears faded.
So the business and the move are both real, and they are not the same event. Essentially none of the last month's gain is accounted for by Intapp's results, because there were none; the summer leg of the recovery followed an August print in which the cloud engine and retention both improved. Forward multiples price the resolution of the mix problem — 5.5x forward sales, and a forward price-to-earnings ratio of 29.5x against GAAP losses today — while consensus models 14.6% revenue growth in fiscal 2027, above the 13.0% just reported. That is a bet that the license drag runs out before the cloud growth rate does.
The license base will finish shrinking eventually, and when it does the reported number and the cloud number converge somewhere near each other. Until then every quarter reads worse on the line most people look at than the business underneath it actually is, and the market has already paid for the convergence.