

Clearway Reset Its Wind Contracts Higher; Brookfield Renewable Leaned on Asset Sales
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Two renewable yield vehicles have been sold off together since the summer on the premise that the contracted revenue underneath them is decaying. Only one of them has a business that agrees.
Clearway restructured three Texas wind farms in June at better pricing with terms past 2040, grew June-quarter revenue 22.7% to $481m with operating income up 36.5%, and has banked tax-credit eligibility on 14.7 GW ahead of July's start-construction cliff; the only cut was an 8% trim to 2026 cash guidance on weak wind, with the 2027 target of $2.70 a share untouched. Brookfield Renewable's record quarter is a different animal: roughly $175m of $421m of funds from operations came from asset sales, interest expense rose to $658m, and the distribution now yields 5.42% against a 30-year Treasury at 5.42%.
The common leg is the discount rate. The business case splits.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
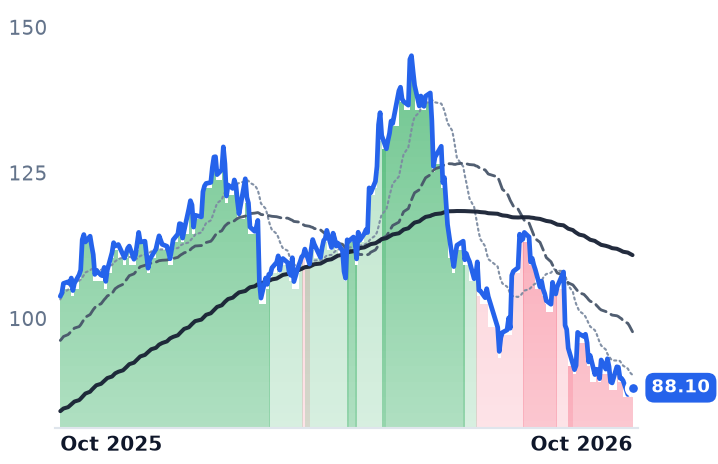
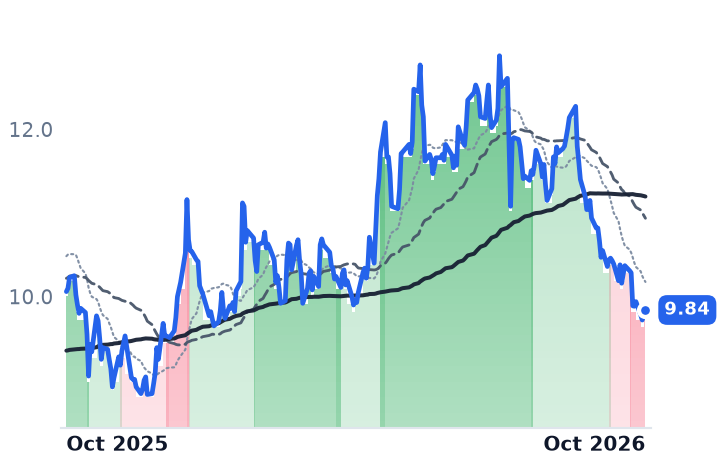
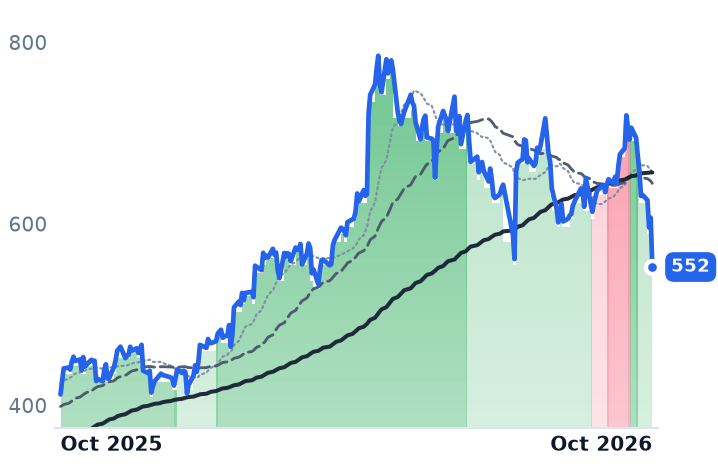
CWEN | Clearway Energy | Diversified Generators | 🔴 Cont. Bear | +2.5% | +3.9% |
BEP | Brookfield Renewable Partners | Diversified Generators | ⚠️ Emerging Bear | −3.3% | +3.3% |
BEPC | Brookfield Renewable | Diversified Generators | 🔴 Cont. Bear | −2.6% | −23.6% |
| Compared against · context, not the story | |||||
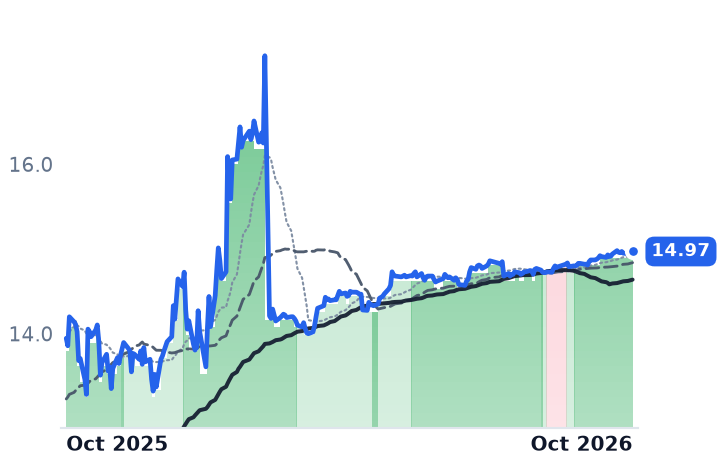
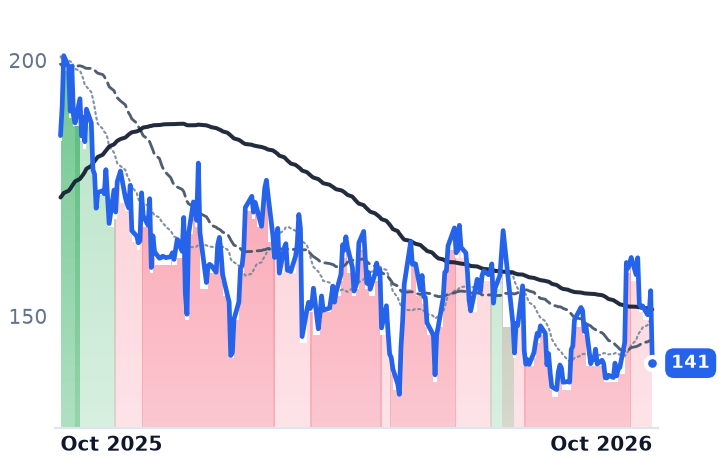
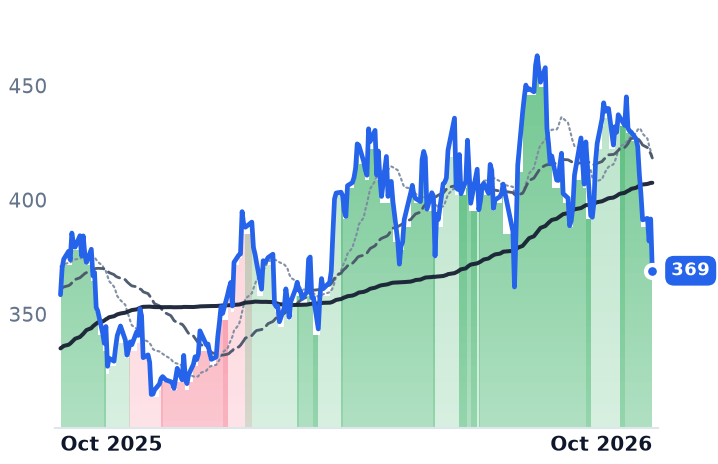
NEE | NextEra Energy | Diversified Multi-State | 🔴 Cont. Bear | +3.3% | +0.2% |
ORA | Ormat Technologies | Geothermal Specialists | 🔴 Cont. Bear | −9.4% | −15.1% |
XIFR | XPLR Infrastructure | Infrastructure Investor | ⚠️ Emerging Bear | −9.1% | −2.2% |
AES | The AES | International Power | 🟢 Cont. Bull | +1.0% | +7.3% |
VST | Vistra | Retail-Focused Operators | 🔴 Cont. Bear | +0.0% | −24.0% |
TLN | Talen Energy | Wholesale Generators | ⚠️ Emerging Bear | +12.5% | −12.9% |
CEG | Constellation Energy | Wholesale Generators | 🔴 Cont. Bear | −3.1% | −26.9% |
NRG | NRG Energy | Retail-Focused Operators | 🔴 Cont. Bear | −8.5% | −40.8% |
GEV | GE Vernova | Power Generation & Propulsion | ⚠️ Emerging Bear | −12.9% | +43.9% |
PWR | Quanta Services | Power Grid & Distribution | ⚠️ Emerging Bear | −14.0% | +34.1% |
ETN | Eaton | Power Distribution Systems | 🟢 Cont. Bull | −16.6% | +2.9% |
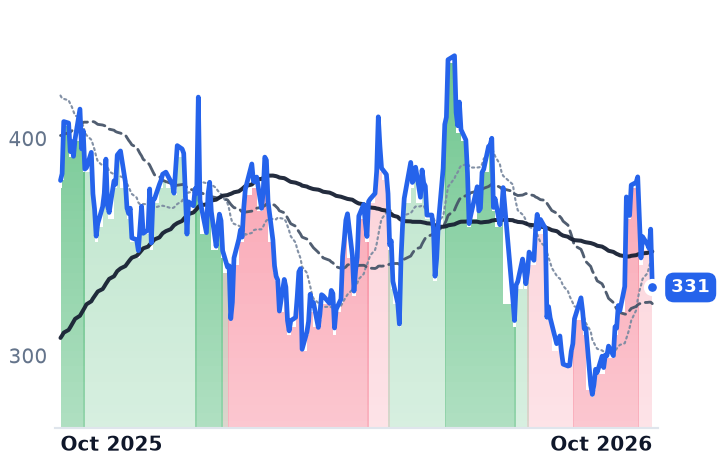
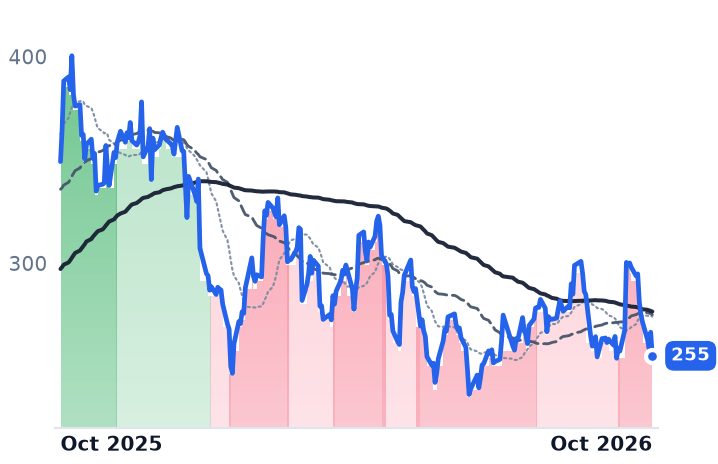
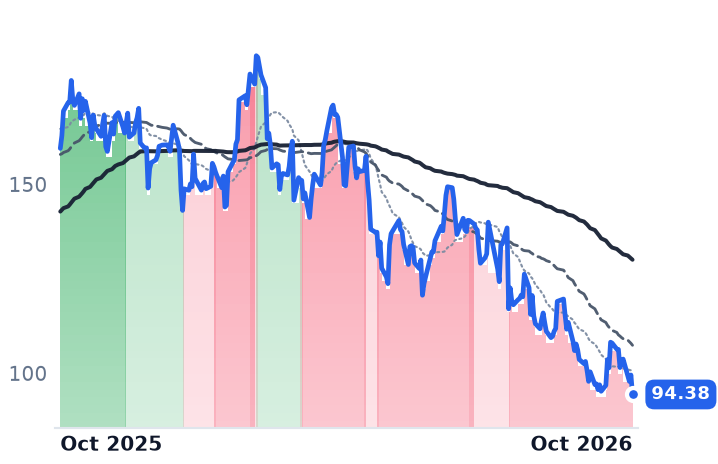
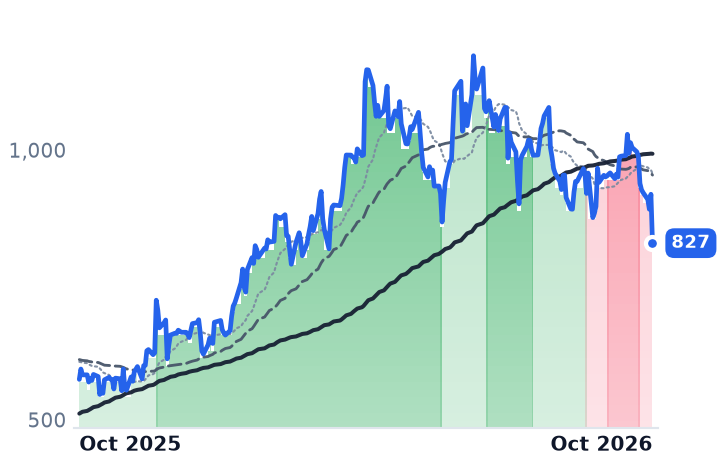
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CWEN | $6.5B | 41.4x | — | 4.1x | 3.9x | 7.7x | 7.4x | 13.8x | 10.4% |
BEP | $8.7B | 62.8x | — | 1.4x | 1.3x | 5.6x | 5.3x | 9.6x | -54.4% |
BEPC | $4.4B | n/m | — | 1.1x | 0.8x | 2.3x | 1.6x | n/m | -12.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NEE | $160.3B | 17.2x | 19.3x | 5.5x | 5.2x | 7.7x | 7.2x | 15.1x | -6.3% |
ORA | $5.7B | 44.6x | 36.5x | 4.8x | 4.8x | 17.2x | 17.3x | 19.8x | -4.6% |
XIFR | $972.0M | 15.4x | 8.6x | 0.8x | 0.7x | 4.7x | 4.2x | 8.5x | -65.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AES | $10.5B | 5.6x | 6.4x | 0.8x | 0.8x | 4.0x | 4.0x | 9.0x | -16.4% |
VST | $54.4B | 27.0x | 18.7x | 3.4x | 2.4x | 26.3x | 18.7x | 11.3x | 2.5% |
TLN | $17.2B | n/m | 18.4x | 4.9x | 3.9x | 10.9x | 8.7x | 36.8x | 3.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CEG | $107.0B | 29.0x | 24.7x | 3.5x | 3.2x | 20.0x | 18.4x | 15.8x | 0.3% |
NRG | $21.2B | — | 11.3x | — | 0.6x | — | — | 10.5x | 1.6% |
GEV | $267.6B | 28.5x | 33.0x | 6.5x | 5.8x | 32.0x | 28.6x | 28.5x | 4.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PWR | $82.2B | 61.8x | 32.6x | 2.5x | 2.1x | 17.4x | 14.4x | 28.5x | 2.9% |
ETN | $149.2B | 39.0x | 28.2x | 5.0x | 4.5x | 13.8x | 12.6x | 26.3x | 3.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CWEN | Revenue | +13.9% | +12.1% | +13.2% |
| EPS | −104.5% | −951.7% | +33.6% | |
BEP | Revenue | +3.4% | +9.5% | −3.3% |
| EPS | +11.4% | −10.5% | +9.0% | |
BEPC | Revenue | +3.3% | +17.4% | +9.3% |
| EPS | +282.2% | −93.2% | +450.2% | |
NEE | Revenue | +8.9% | +9.7% | +9.0% |
| EPS | +7.5% | +9.0% | +8.6% | |
ORA | Revenue | +21.4% | −2.1% | +10.6% |
| EPS | +16.4% | −4.2% | +27.8% | |
XIFR | Revenue | +0.8% | +4.7% | +1.3% |
| EPS | −889.4% | −39.7% | −94.7% | |
AES | Revenue | +6.3% | +5.3% | +3.0% |
| EPS | +8.0% | +7.1% | +5.5% | |
VST | Revenue | +16.7% | +9.7% | +5.4% |
| EPS | +80.8% | +18.5% | +18.5% | |
TLN | Revenue | +84.0% | +16.0% | +4.9% |
| EPS | +247.2% | +49.2% | +17.7% | |
CEG | Revenue | +37.2% | +2.5% | +5.3% |
| EPS | +28.9% | +10.4% | +26.4% | |
NRG | Revenue | +17.7% | +0.8% | +3.7% |
| EPS | +14.0% | +24.5% | +15.8% | |
GEV | Revenue | +24.0% | +14.6% | +14.9% |
| EPS | +319.0% | −19.6% | +41.4% | |
PWR | Revenue | +41.1% | +16.3% | +14.1% |
| EPS | +57.7% | +17.9% | +18.3% | |
ETN | Revenue | +20.2% | +11.4% | +9.9% |
| EPS | +12.8% | +19.7% | +17.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
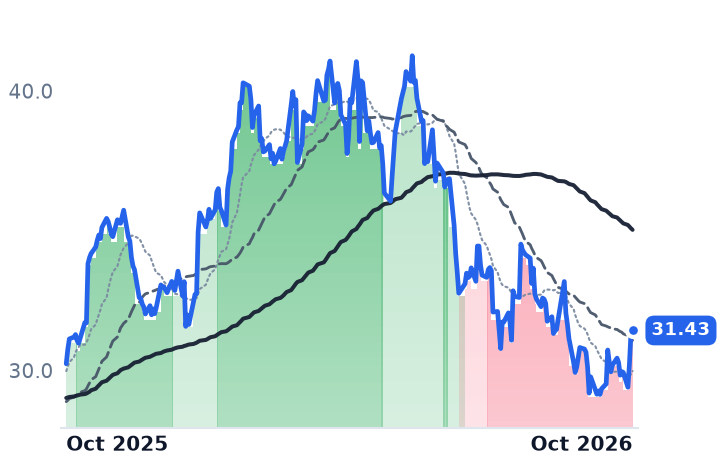
Clearway Energy, which owns roughly 5,000 net megawatts of American wind and solar alongside a gas-fired fleet, restructured the offtake contracts on its Texas wind farms in June at higher prices, with terms now running past 2040. In January it had signed nearly 1.2 GW of twenty-year power purchase agreements with Google across three states, more than $2.4bn of investment with first power due in 2027. The shares are down about a fifth over six months.
The reading on offer for the renewable yield vehicles is that the long-dated contracted revenue which is their whole earnings engine is quietly decaying: agreements recontracted below the expiring ones, tax credits phasing out, interest absorbing the distribution. Clearway's disclosures record the reverse, and so does the market for new power contracts. What moved both it and Brookfield Renewable, the owner of hydro, wind and solar across the Americas that sells most of its output under long-term contracts, was the price of money: the Federal Reserve raised its target a quarter point on 16 September, its first increase since 2023, the 30-year Treasury printed 5.42% on 20 October against 4.60% a year earlier, and utilities fell 6% in a month to 17% below their 52-week high.
The guidance cut was weather
Clearway's June quarter grew revenue 22.7% to $481m, with operating income up 36.5% to $116m and gross margin at 69.0% against 66.6% a year earlier. In August it cut the midpoint of 2026 cash available for distribution about 8%, to $430-470m from $470-510m, on below-normal wind and solar output, and left the 2027 target of $2.70 a share and the 2030 range of $2.90-3.10 where they were.
"While we are lowering our 2026 financial guidance due to factors outlined in our mid-July operational preview, our team is focused on maintaining our trademark operational excellence to uphold our historic track record of meeting our financial targets," chief executive Craig Cornelius said in the 5 August results release.
The policy channel has gone the same way. Clearway has safe-harbored tax-credit eligibility on 14.7 GW of wind and solar, with 9 GW and more qualified for service in 2031-2034, and has sourced equipment for its entire development program through 2027 and substantially all of 2028 — all of it predating the 4 July start-construction cliff that accelerated the credit's termination. Transfer discounts on those credits remain narrow, $0.92 to $0.945 on the dollar for production credits. And new contracts are getting dearer: the average North American solar agreement rose 4.9% in the third quarter to $64.23 per MWh, with wind up 13.8% on the year.
The constraint is the balance sheet, and Clearway named it. The company needs $0.5-1.0bn of external equity through 2029 to fund a $3bn capital program and has raised about $50m, which has paused third-party purchases. "When it's not where we want it to be or valuations for third-party acquisitions, we think, are not really reflective of their intrinsic value, then we step out," Cornelius told investors on the 5 August call. At $31.43 the shares sit at 0.70 times book — below the accounting value of the plants — on 13.8 times trailing EV/EBITDA and a 10.4% trailing free-cash-flow yield, or about 11.6 times the 2027 cash target, a figure derived from the reaffirmed guidance rather than one the company prints.
Brookfield's record came partly out of the sale ledger
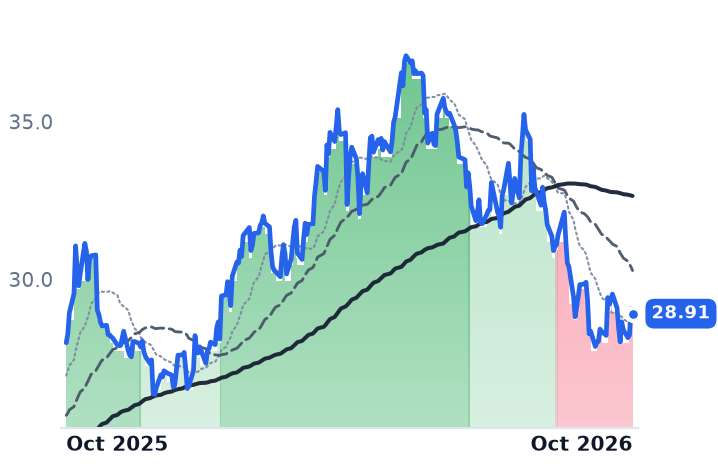
"We delivered another record quarter, generating FFO of $421 million, or $0.62 per unit, up 13% or 11% per unit year-over-year," Connor Teskey said on Brookfield Renewable's 31 July call. Roughly $175m of that sat in the hydro segment as other income from developed-asset and non-core sales; the partnership closed two-thirds of a sale of about 2,100 MW to the Northview platform in the quarter. Strip the gains and per-unit funds from operations fall near $0.36 against a declared distribution of $0.392, coverage of about 0.92 times on that derived basis. Interest expense rose 5.4% to $658m, more than the whole quarter's funds from operations. Reported revenue fell 1.8%.
At $28.91 the $1.568 annualized distribution yields 5.42%, the same as the 30-year Treasury on 20 October, leaving nothing for equity risk. Clearway's $1.90 annualized dividend yields 6.05%, roughly 63 basis points of spread, down from about 90 in late September.
Demand is not the dispute. Brookfield's framework with Microsoft commits it to 10.5 GW delivered between 2026 and 2030, and Teskey argued in October that supply will trail demand for compute and power by three to ten times through the decade: "There's a lot of growth in the market and that can overwhelm slightly higher cost of capital."
The year's loss belongs to a share class
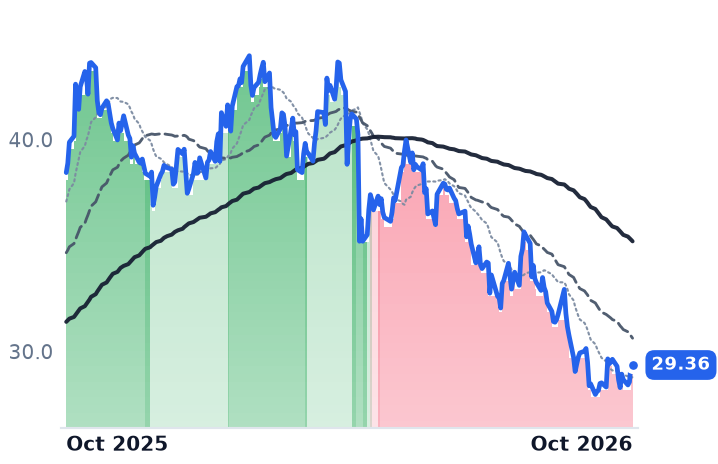
The twelve-month decline attributed to this corner of the market is largely an artifact of the corporate simplification. BEPC, the corporate twin exchangeable one-for-one into Brookfield Renewable units, fell 25.0% over the year as its premium collapsed from 38% to 1.6%; the partnership units themselves rose 2.1% and Clearway 1.4%. Holders of the corporate shares approved the transaction on 14 October with more than 99.7% in favor; the unitholder meeting was adjourned to 29 October.
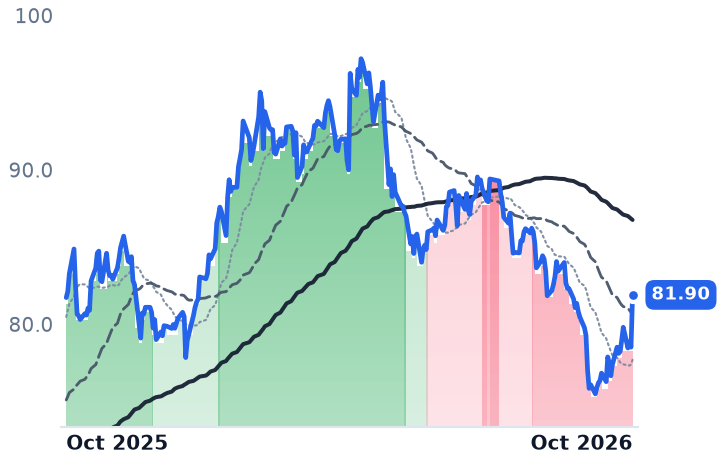
So the selloff is mostly explained, and explained the same way for both: a long-dated, indexed stream of cash discounted at a rate that has moved almost a full point in a year, which is why NextEra fell 17.6% and Ormat 21.8% over the same six months. What the rate does not explain is why the two deserve the same multiple. Brookfield's de-rating has a business counterpart — a payout with no spread over government paper and coverage that depends on continuing to sell plants — while Clearway's contract meter is lengthening and its credits are locked.
Clearway's fuel costs nothing and its competitors' fuel is getting scarcer. What it cannot buy cheaply, at 0.70 times the value of its own turbines, is its own equity.