

Fair Isaac's $10 Mortgage Score Is Now Undercut at $1 Through the End of 2028
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Fair Isaac's growth in mortgage credit scoring has come almost entirely from the fee it charges, and the two bureaus that distribute its score have now committed to selling a rival model for about a dollar until the end of 2028.
In the June quarter the company's mortgage origination revenue rose 97% while mortgage score volumes grew low single digits, tracking a wholesale royalty taken from $4.95 to $10.00 a score for 2026. Mortgage is 62% of Scores revenue. Equifax says more than 165 lenders now use VantageScore 4.0 exclusively at $1, and Rocket Mortgage defaults to it this quarter.
Reported results are not the problem: group revenue grew 25.7% with operating margin at 53.8%. The fiscal-2027 consensus of $48.92 a share still assumes the $10 fee holds.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
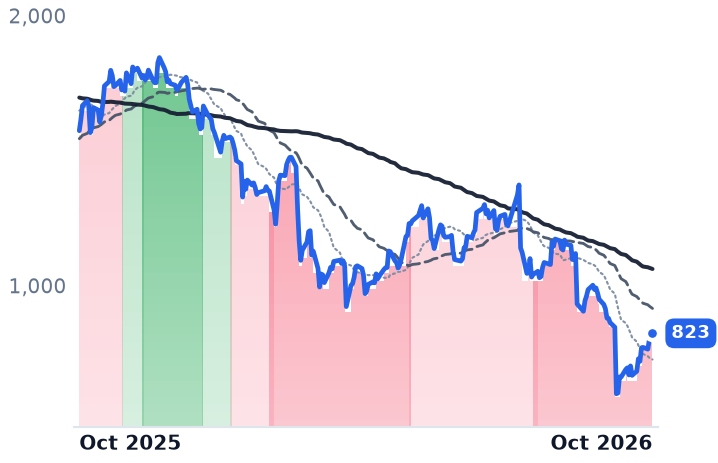
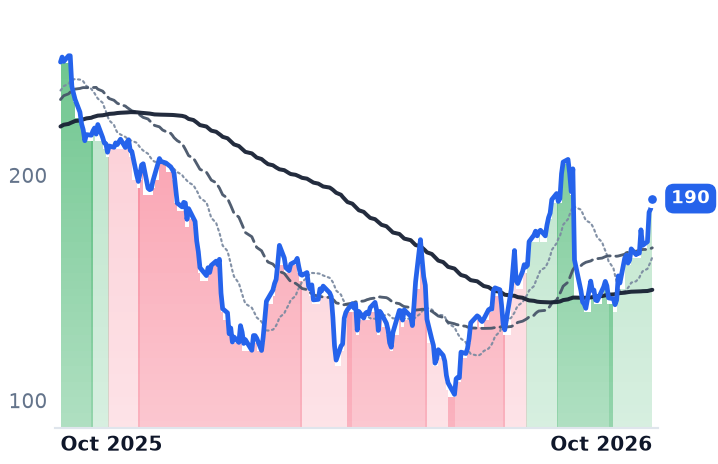
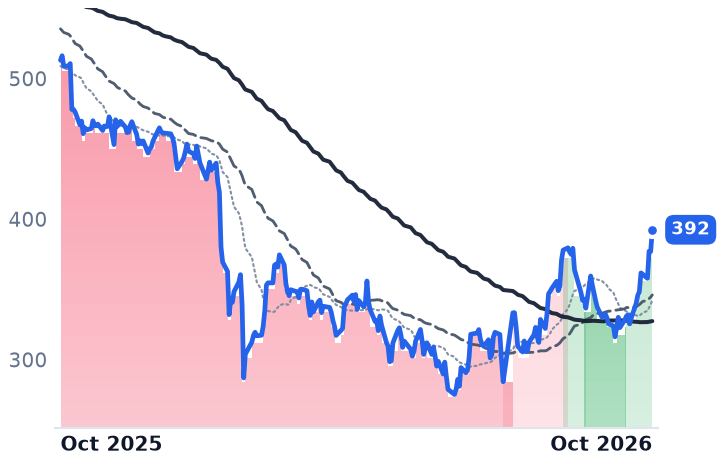
FICO | Fair Isaac | Data, Analytics & Intelligence | 🔴 Cont. Bear | −10.0% | −47.7% |
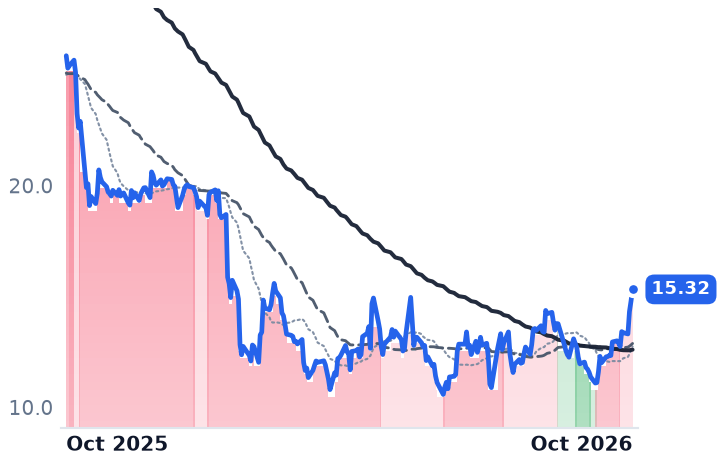
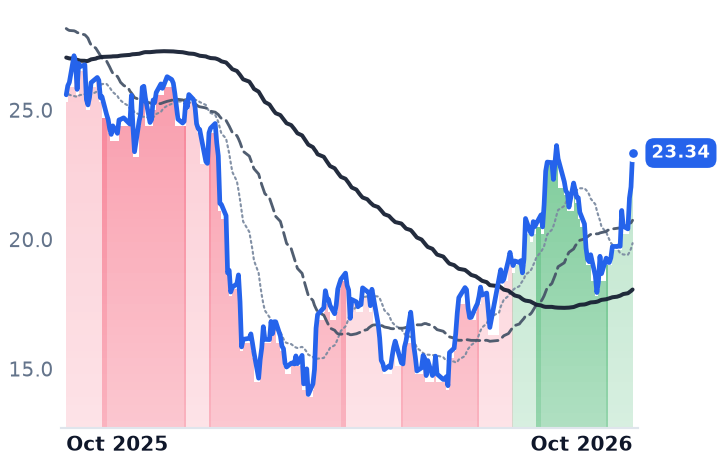
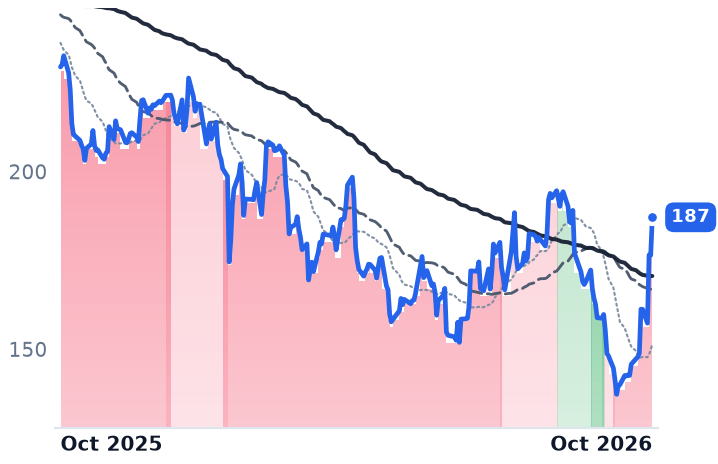
VERX | Vertex | Commerce & Digital Payments | 🌱 Emerging Bull | +29.9% | −40.8% |
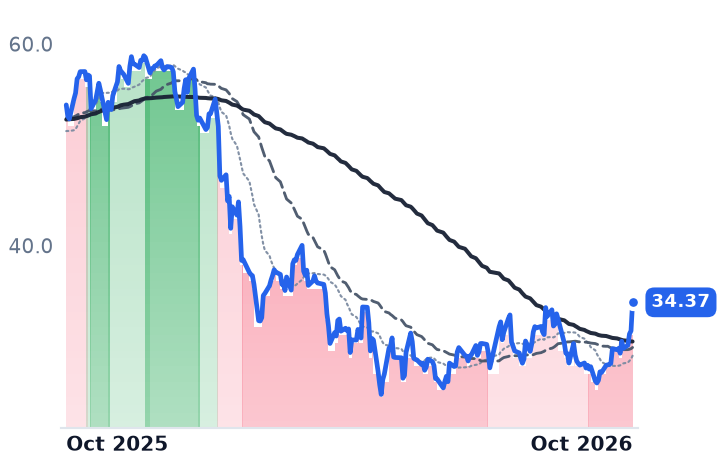
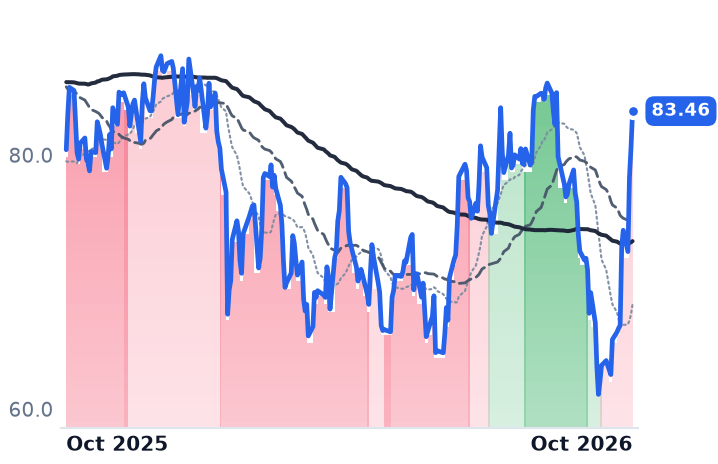
BL | BlackLine | Other | 🔴 Cont. Bear | +23.4% | −36.3% |
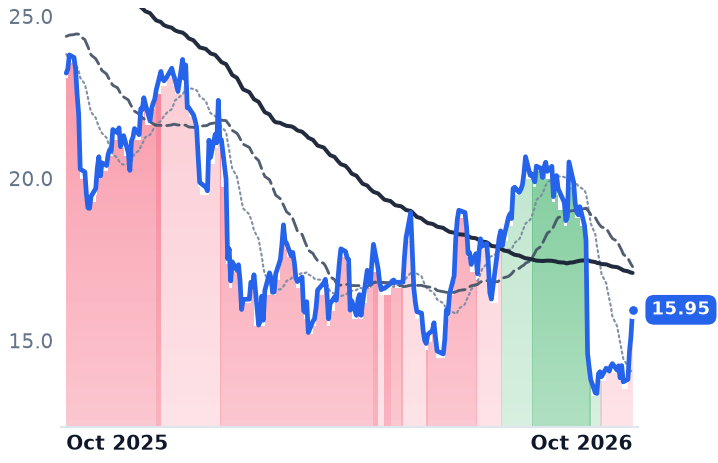
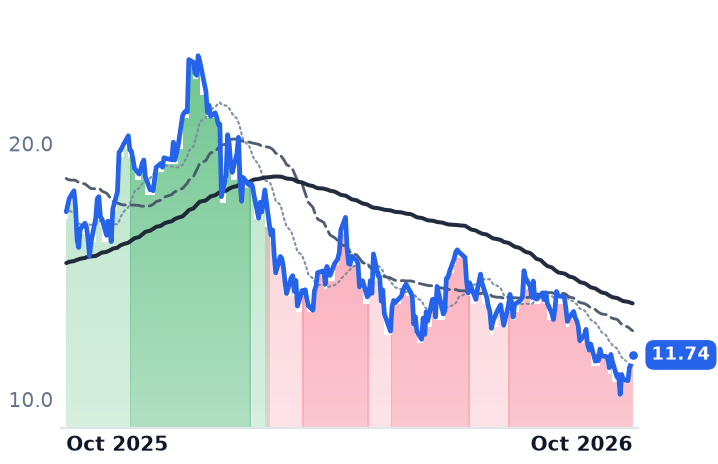
ALKT | Alkami Technology | Commerce & Digital Payments | 🌱 Emerging Bull | −11.8% | −31.4% |
GWRE | Guidewire Software | Industry-Specific Platforms | 🌱 Emerging Bull | +26.0% | −24.2% |
NCNO | nCino | Commerce & Digital Payments | 🌱 Emerging Bull | +18.7% | −8.8% |
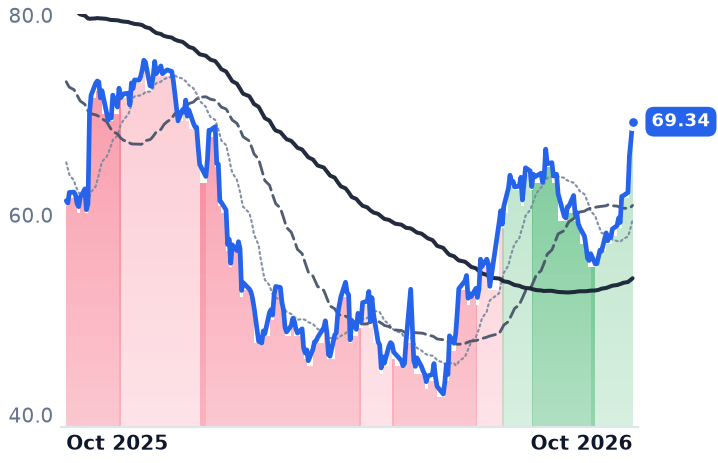
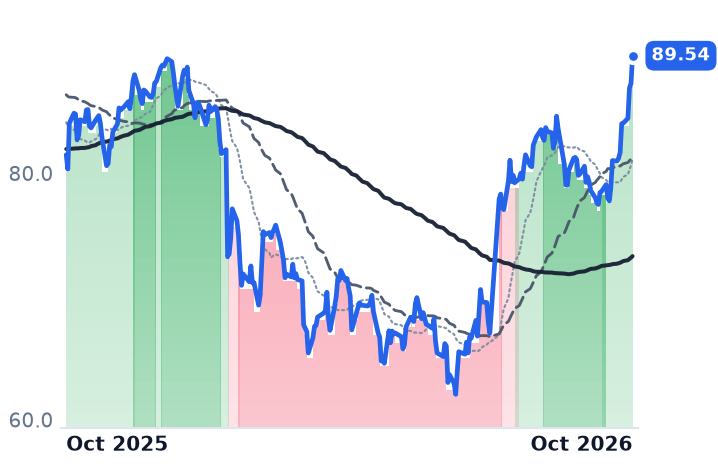
QTWO | Q2 | Commerce & Digital Payments | 🌱 Emerging Bull | +21.9% | +12.9% |
SSNC | SS&C Technologies | Enterprise Resource Planning | 🌱 Emerging Bull | +13.0% | +9.9% |
TYL | Tyler Technologies | Industry-Specific Platforms | 🌱 Emerging Bull | +18.5% | −23.5% |
| Compared against · context, not the story | |||||
EFX | Equifax | Workforce Data & Analytics | 🔴 Cont. Bear | +17.1% | −18.5% |
TRU | TransUnion | Consumer Credit Reporting | 🌱 Emerging Bull | +16.1% | +3.8% |
RKT | Rocket Companies | Residential Loan Originators | 🔴 Cont. Bear | −7.8% | −32.3% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FICO | $14.9B | 19.9x | 14.8x | 6.2x | 5.6x | 7.3x | 6.5x | 16.0x | 6.7% |
VERX | $2.4B | 483.7x | 18.1x | 3.0x | 2.9x | 4.9x | 4.7x | 48.0x | 2.4% |
BL | $2.0B | 57.9x | 13.7x | 2.7x | 2.6x | 3.6x | 3.4x | 24.0x | 8.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ALKT | $1.6B | n/m | 19.5x | 3.4x | 3.1x | 5.9x | 5.4x | n/m | 4.0% |
GWRE | $13.9B | 102.5x | 40.4x | 9.4x | 8.1x | 14.6x | 12.6x | 66.4x | 2.1% |
NCNO | $2.4B | 73.9x | 17.4x | 3.9x | 3.8x | 6.3x | 6.1x | 29.0x | 5.5% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
QTWO | $4.2B | 46.0x | 23.6x | 5.0x | 4.8x | 8.8x | 8.4x | 28.2x | 4.8% |
SSNC | $18.8B | 22.5x | 11.2x | 2.8x | 2.8x | 5.8x | 5.8x | 11.6x | 9.3% |
TYL | $15.5B | 49.6x | 28.9x | 6.4x | 6.1x | 13.7x | 13.0x | 28.4x | 4.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EFX | $17.7B | 26.2x | 17.6x | 2.7x | 2.6x | 4.9x | 4.7x | 12.1x | 6.3% |
TRU | $12.8B | 17.5x | 13.8x | 2.6x | 2.5x | 4.7x | 4.5x | 9.6x | 6.1% |
RKT | $29.7B | 67.3x | 17.7x | 3.1x | 2.7x | 3.4x | 3.0x | 24.1x | -2.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
FICO | Revenue | +27.3% | +6.3% | +7.2% |
| EPS | +44.8% | +9.6% | +12.3% | |
VERX | Revenue | +10.6% | +10.5% | +11.5% |
| EPS | +28.4% | +23.9% | +21.1% | |
BL | Revenue | +9.5% | +10.4% | +10.3% |
| EPS | +19.7% | +10.9% | +18.0% | |
ALKT | Revenue | +19.6% | +16.7% | +14.5% |
| EPS | +51.0% | +37.6% | +24.0% | |
GWRE | Revenue | +23.8% | +17.2% | +15.7% |
| EPS | +41.5% | +20.8% | +27.4% | |
NCNO | Revenue | +9.8% | +8.9% | +8.6% |
| EPS | +25.2% | +45.3% | +20.0% | |
QTWO | Revenue | +11.8% | +10.1% | +10.3% |
| EPS | +21.8% | +20.8% | +28.9% | |
SSNC | Revenue | +8.4% | +5.1% | +4.9% |
| EPS | +17.7% | +8.6% | +8.4% | |
TYL | Revenue | +8.6% | +10.1% | +8.7% |
| EPS | +14.6% | +17.6% | +13.8% | |
EFX | Revenue | +11.2% | +8.3% | +9.7% |
| EPS | +11.8% | +17.4% | +21.0% | |
TRU | Revenue | +13.8% | +8.2% | +8.1% |
| EPS | +13.5% | +15.0% | +15.8% | |
RKT | Revenue | +72.1% | +5.7% | +7.9% |
| EPS | +146.1% | +34.6% | +21.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Fair Isaac's competitor in mortgage credit scoring now has a published price and a published expiry date. Equifax said on 8 October that it will keep selling VantageScore 4.0 to mortgage lenders at $1 through the end of 2028, a commitment it claims could save the industry about $1bn, and TransUnion has fixed its standalone price at 99 cents through December 2028, saying it will not charge separately for that score when a customer also buys a FICO score. Both bureaus distribute Fair Isaac's score for a living.
The company's fall since September has been read as the market pricing one lost customer and a weaker origination forecast. The bureaus' commitments describe a slower problem. Price, not volume, is what has been growing the Scores segment at Fair Isaac, which sells credit scores and decision-management software from Bozeman, Montana, and the price of the alternative is now set for three more years.
Nearly all of the mortgage gain was the fee
In the June quarter Scores revenue rose 41% to $458.9m, with the business-to-business half up 49%, which the company attributed "primarily" to a higher mortgage origination scores unit price. Mortgage origination revenue rose 97%; mortgage score volumes grew low single digits. Mortgage is 62% of Scores revenue.
The royalty shows the arithmetic. Fair Isaac took its wholesale mortgage fee from $4.95 to $10.00 a score for 2026, after moving it from $0.60 to $4.95 over the prior five years. A roughly 102% price step produced a 97% revenue gain, so units and mix contributed close to nothing. Group revenue grew 25.7% to $674.2m with operating margin at 53.8%, against 48.9% a year earlier.
The rival is already inside agency underwriting
Fannie Mae's Lender Letter LL-2026-06 and Freddie Mac's Bulletin 2026-H, both dated 9 September, made VantageScore 4.0 available to every approved seller without prior written approval, and 37% of conventional applications created in Fannie Mae's Desktop Underwriter in September included a VantageScore 4.0 score. Equifax says nearly 2,000 mortgage lenders and resellers now access the model, that pulls rose 230% between April and August, and that more than 165 lenders use it exclusively at the $1 price for certain loan types. Rocket Mortgage said on 28 September that it will default to VantageScore 4.0 this quarter on all eligible loans, including loans delivered to Fannie Mae and Freddie Mac, citing average closing savings of $1,600 for borrowers who benefited. Senator Josh Hawley asked the Federal Trade Commission on 23 March to investigate the price increases.
"We're not crazy about lenders choice as a policy. We think it's bad policy because it encourages gaming," chief executive William Lansing said on Fair Isaac's 29 July earnings call, adding that volumes were not falling, "which suggests that they're pulling both scores." Rocket's decision came two months later.
What the company is doing about the dollars
Fair Isaac's answer is its Mortgage Direct License Program, which lets tri-merge resellers calculate and distribute FICO scores without going through the bureaus, at $4.95 a score plus a $33 fee on funded loans, or $10 flat. Six resellers are under contract — Xactus, Cotality, Ascend Companies, CIC Credit, MeridianLink and Credit Interlink — together more than half the reseller market by origination volume. "This change eliminates unnecessary mark-ups on the FICO Score," Lansing said announcing the program on 1 October 2025. FICO Score 10T becomes available to FHA-approved lenders on 1 January 2027. On 1 October the company also committed to eliminating about 15% of its positions, with roughly $27.0m of pre-tax charges in the fiscal fourth quarter, which protects margin on the revenue that arrives and does nothing for the score count.
A 10% fall inside a software rebound
The shares closed at $823.27 on 22 October, 23.7x trailing earnings against roughly 62x in January, and 16.8x the fiscal-2027 consensus of $48.92 a share drawn from 13 analysts. Fair Isaac fell 10% over the month to that date while most of the application-software names beside it rose, in a rebound that carried the S&P 500 software and services index to its highest level since November 2025. Vertex, which sells the indirect-tax engine that sits inside customers' SAP and Oracle systems, gained 29.9% and trades at 4.84x forward gross profit against 3.70x in late September, with revenue growth decelerating to 10.5%. BlackLine, whose software automates the corporate accounting close, rose 23.4% to 3.45x forward gross profit from 2.85x, on annual recurring revenue of $719m growing 6%. Neither has reported since early August.
The fee, not the quarter, is what is being priced
Fair Isaac's reported figures account for none of its decline, and the consensus estimate is where the argument actually sits: $48.92 assumes the $10 score survives into a year in which the Mortgage Bankers Association's 11 October forecast puts origination counts at 5.0 million, 5.6% below 2026. The signed direct-license channel and 10T's entry into FHA lending are genuine defences of that fee. Against them sit a rival locked near a dollar until 2028, a large lender switching its default, and a third of agency applications already carrying the other score. If lenders keep pulling both, the price holds and the forward earnings arrive. If they stop, the price step unwinds into a shrinking loan count, and the Software segment is too small to cover the gap: Platform recurring revenue grew 62% to $413m, but total Software revenue rose 2% to $215m.
Fair Isaac reports fiscal fourth-quarter and full-year results after the close on 4 November, a quarter billed before Rocket's switch took effect. The question those results cannot answer is what a score is worth to a lender who already has a cheaper one sitting in the same credit file.