

A Stopgap Pentagon Budget Bars New Program Starts, Sparing L3Harris's Record Backlog
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
The shelf of intelligence, surveillance and reconnaissance contractors has been read as a demand story going backwards. Their June quarters carry the strongest order books any of them has reported.
L3Harris booked $7.3bn of orders into a record $42bn backlog, Leonardo DRS logged its 18th consecutive quarter of book-to-bill at or above 1.0 with funded backlog up 17%, and Elbit's backlog reached $32.0bn with 73% of it outside Israel. What splits the group is whether the revenue is already appropriated. The stopgap Pentagon budget signed in September bars new program starts, and HawkEye 360, whose only business is signals intelligence gathered from satellites, sits at an all-time low despite consensus revenue growth of 85%. L3Harris has de-rated to 20.7x forward earnings from 38.0x trailing at the start of May.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
LHX | L3Harris Technologies | ISR & Mission Systems | 🔴 Cont. Bear | +0.2% | −14.6% |
DRS | Leonardo DRS | ISR & Mission Systems | ⚠️ Emerging Bear | −11.3% | −15.7% |
ESLT | Elbit Systems | ISR & Mission Systems | 🔴 Cont. Bear | −1.4% | +52.5% |
HAWK | HawkEye 360 | ISR & Mission Systems | 🔴 Cont. Bear | −27.3% | −65.1% |
LYNX | Lyntris | ISR & Mission Systems | 🔴 Cont. Bear | −15.0% | −24.5% |
| Compared against · context, not the story | |||||
NOC | Northrop Grumman | Integrated Defense Contractors | 🔴 Cont. Bear | +2.1% | −9.8% |
LMT | Lockheed Martin | Integrated Defense Contractors | ⚠️ Emerging Bear | +2.2% | +13.2% |
GD | General Dynamics | Integrated Defense Contractors | 🟢 Cont. Bull | −3.1% | +1.8% |
RTX | RTX | Integrated Defense Contractors | 🟢 Cont. Bull | −2.2% | +10.9% |
LDOS | Leidos | Defense & Government Services | 🔴 Cont. Bear | −0.5% | −33.5% |
AVAV | AeroVironment | Unmanned & Autonomous Systems | 🔴 Cont. Bear | −28.5% | −69.1% |
KTOS | Kratos Defense & Security Solutions | Unmanned & Autonomous Systems | 🔴 Cont. Bear | −20.8% | −57.4% |
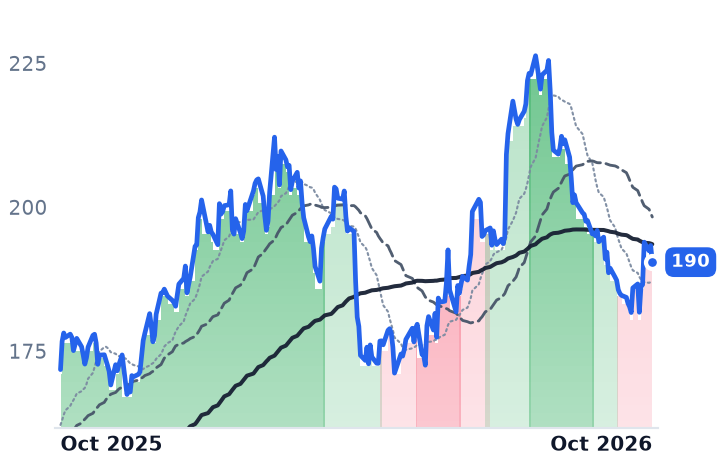
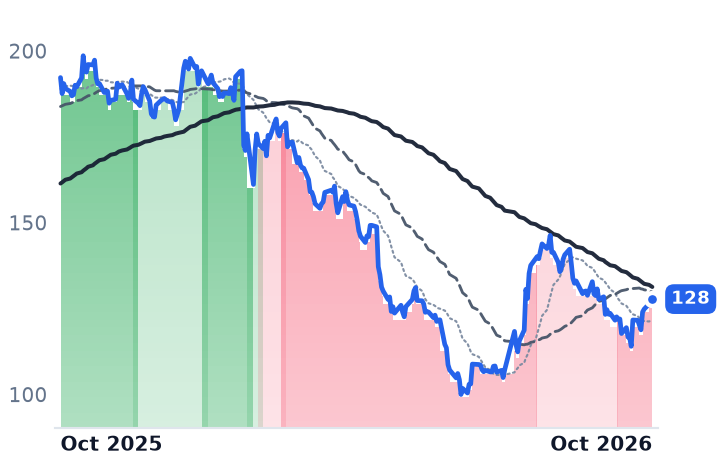
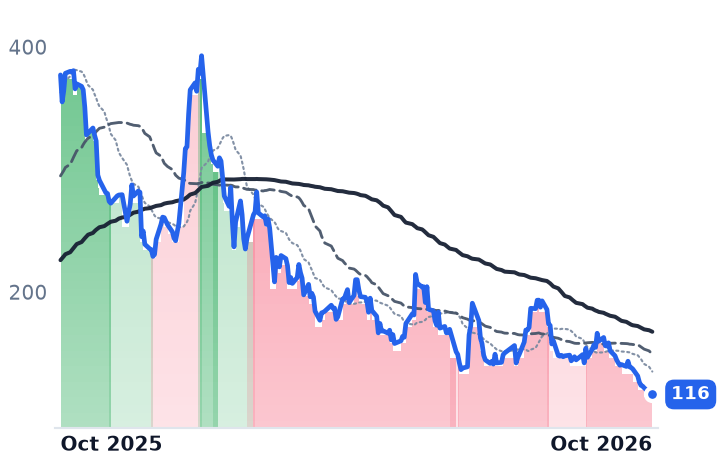
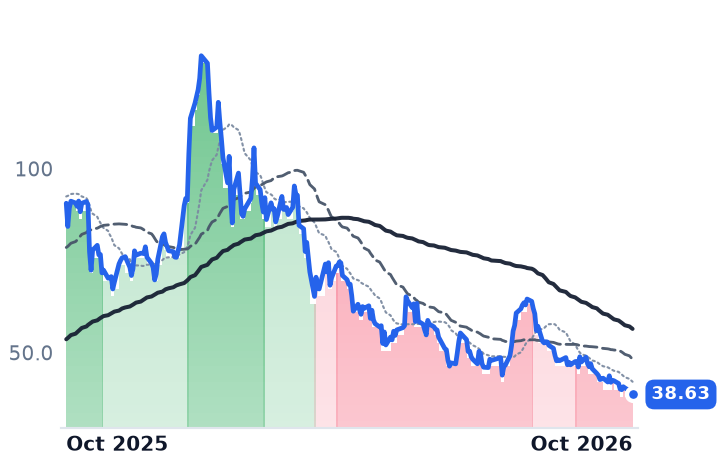
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LHX | $46.1B | 24.9x | 20.7x | 2.0x | 2.0x | 7.9x | 7.7x | 13.9x | 6.1% |
DRS | $9.0B | 28.2x | 24.3x | 2.4x | 2.3x | 9.6x | 9.2x | 18.2x | 4.0% |
ESLT | $35.0B | 54.1x | 50.8x | 4.1x | 3.8x | 16.2x | 15.3x | 38.0x | 2.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
HAWK | $1.2B | n/m | — | 7.0x | 5.4x | 10.8x | 8.4x | 68.7x | -0.2% |
LYNX | $1.3B | — | — | — | — | — | — | — | — |
NOC | $70.4B | 15.7x | 17.1x | 1.6x | 1.6x | 8.2x | 8.0x | 11.3x | 5.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LMT | $120.5B | 19.2x | 17.2x | 1.6x | 1.5x | 13.3x | 12.6x | 13.4x | 7.2% |
GD | $90.5B | 20.1x | 19.7x | 1.7x | 1.6x | 10.7x | 10.5x | 14.3x | 7.1% |
RTX | $248.9B | 32.1x | 25.5x | 2.7x | 2.6x | 13.1x | 12.7x | 17.4x | 4.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LDOS | $14.8B | 10.9x | 9.5x | 0.8x | 0.8x | 4.8x | 4.6x | 9.0x | 14.6% |
AVAV | $7.5B | n/m | 45.6x | 3.8x | 3.4x | 15.0x | 13.5x | n/m | -1.6% |
KTOS | $9.8B | 302.5x | 62.0x | 6.4x | 5.5x | 29.1x | 24.8x | 71.8x | -1.3% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
LHX | Revenue | +3.2% | +7.1% | +7.4% |
| EPS | −18.5% | +12.2% | +13.6% | |
DRS | Revenue | +10.2% | +7.0% | +6.1% |
| EPS | +27.1% | +6.0% | +9.7% | |
ESLT | Revenue | +15.5% | +12.2% | +10.6% |
| EPS | +37.5% | +19.7% | +15.4% | |
HAWK | Revenue | +84.6% | +25.3% | +23.6% |
| EPS | −3595.0% | −108.1% | +1992.6% | |
NOC | Revenue | +5.3% | +6.9% | +6.2% |
| EPS | +11.0% | +5.0% | +8.1% | |
LMT | Revenue | +8.5% | +6.1% | +6.1% |
| EPS | +40.6% | +7.7% | +6.9% | |
GD | Revenue | +7.7% | +5.0% | +4.4% |
| EPS | +10.5% | +9.5% | +8.0% | |
RTX | Revenue | +10.6% | +7.6% | +7.3% |
| EPS | +16.8% | +9.2% | +10.5% | |
LDOS | Revenue | +5.2% | +6.1% | +4.7% |
| EPS | +17.1% | +4.6% | +2.9% | |
AVAV | Revenue | +140.3% | +15.9% | +15.0% |
| EPS | −5.6% | +13.3% | +37.2% | |
KTOS | Revenue | +34.7% | +23.3% | +21.7% |
| EPS | +57.7% | +34.4% | +28.7% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Congress's stopgap funding law lets the Pentagon keep paying for work already underway and forbids it from beginning anything new. That one rule has done more to sort defense share prices over the past month than any change in what the armed services want to buy.
The companies that build airborne and ground sensing systems have fallen far enough to be read as proof that money is draining out of manned sensor platforms and into satellites. Their June quarters say something else. L3Harris Technologies, Leonardo DRS and Elbit Systems each reported faster revenue growth, wider operating margins and a record order book. The name marked down hardest in the group is the one whose entire business is sensing from space.
The rule inside the stopgap
The continuing resolution signed on 2 September 2026 runs to 11 December and holds the department at the extended fiscal 2026 baseline of $838.5bn against a $1.5 trillion request. It bars any project, program or activity that was not already funded and active in the prior year. Breaking Defense counts more than 150 fiscal 2027 initiatives blocked from starting, including $17.5bn of Golden Dome missile-defense work. A rule written that way penalizes a contractor waiting on a new start and leaves a contractor sitting on funded backlog untouched.
What L3Harris already has under contract
L3Harris, which integrates reconnaissance aircraft, space payloads, tactical radios and electronic warfare systems for governments, took $7.3bn of orders in the June quarter for a 1.2x book-to-bill, lifting backlog above $42bn. Revenue rose 8.4% to $5.88bn and operating margin widened to 11.1% from 10.8%. Its Space & Mission Systems unit grew 7% to about $3bn on higher volume in reconnaissance and missionized aircraft, classified space and F-35 control systems; the segment's 9.8% margin was 60 basis points lower only because a prior-year gain on a product-line sale did not repeat.
"We are actively negotiating more than $20 billion in new contracts, potentially tripling our backlog," chief executive Christopher Kubasik told investors on the 29 July 2026 call.
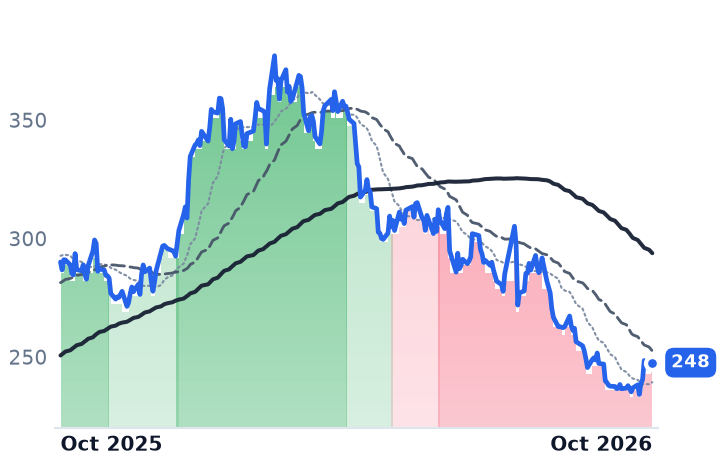
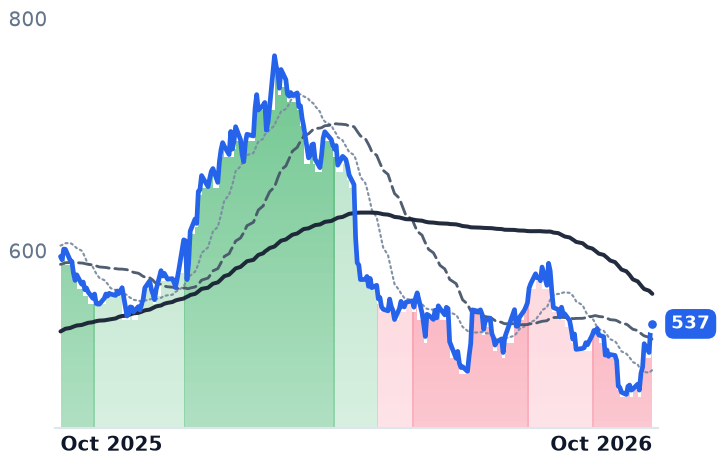
The shares are flat over thirty days, down 10.8% over ninety and 15.3% over a year. That leaves 24.9x trailing and 20.7x forward earnings against 38.0x trailing at the start of May, when the market capitalization was $60.7bn rather than today's $46.1bn, with consensus fiscal 2027 earnings per share of $11.94 still climbing at 12%. The propulsion franchise bought with Aerojet Rocketdyne in 2023 and the classified sensor portfolio are intact.
Leonardo DRS fell furthest and bought the software layer
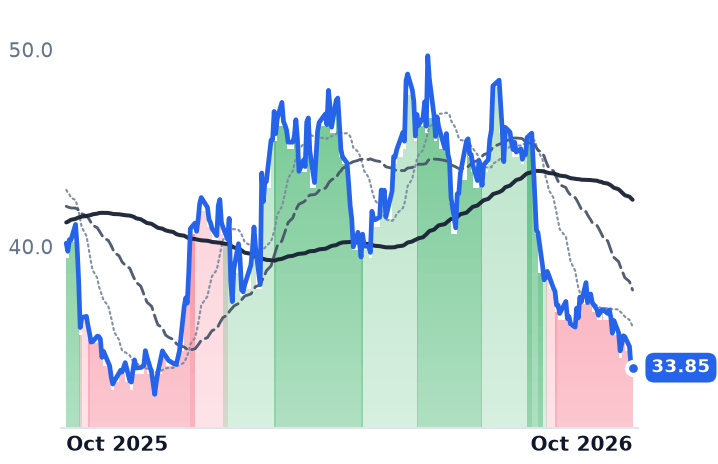
DRS, which supplies infrared sensing, tactical radars and rugged computing to the US military and prime contractors, is down 25.5% over ninety days. Its bookings exceeded $1.1bn for a 1.2x book-to-bill, the 18th consecutive quarter at or above 1.0x, with record funded backlog of $5.1bn, up 17%. Operating margin widened 273 basis points to 11.2% on revenue up 10.1%. The Advanced Sensing and Computing segment that carries the reconnaissance franchise grew 8% to $587m with adjusted EBITDA margin up 110 basis points to 11.8%. "Organic revenue growth accelerated to 10% year-over-year," chief executive John Baylouny said on 30 July 2026.
Far from losing work to software-defined sensing, DRS agreed on 28 July to buy Raft, a McLean, Virginia mission-software firm, for $450m in cash. At 24.3x forward earnings it remains dearer than L3Harris, and consensus has its earnings growth decelerating from 27% this year to 6% next.
The space pure-play that should have won
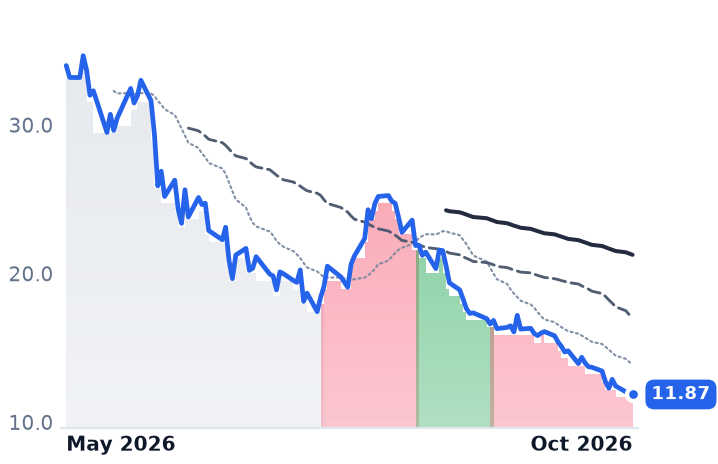
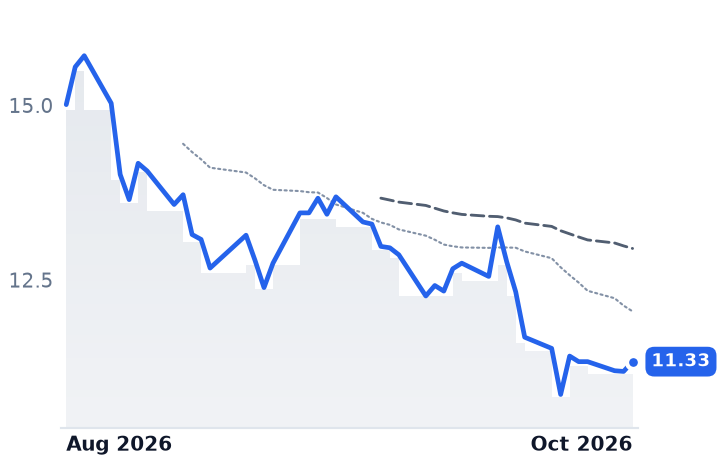
If reconnaissance dollars were migrating to orbit, HawkEye 360 would be the beneficiary. It operates more than 30 satellites mapping radio-frequency emissions for government and allied customers, and consensus has revenue of $217m this year, up 85%, on a 70% gross margin. Instead it set an all-time low of $11.92 on 19 October, down 27.3% in thirty days from an IPO at $26 in May, and trades at 8.36x forward gross profit against 9.18x for DRS. The budget record points the same way: fiscal 2027 defense authorization drafts would dissolve the Space Development Agency into Space Force portfolio executives, after the prior request cut its transport layer by 20%.
Elbit's funding is European
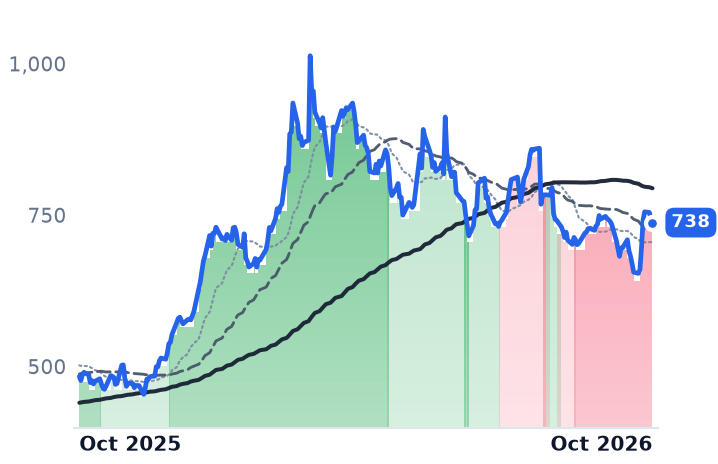
Elbit, the Haifa prime that makes electro-optics, electronic warfare and rocket artillery, is up 52.2% over a year with a record $32.0bn backlog, 73% of it outside Israel and the quarter's increase mainly European. North America was 20% of June-quarter sales. Its largest award of the year was a roughly $1.4bn five-year modernization contract for a European customer in May. At 50.8x forward earnings and 8.1x book it is the most expensive name here, and no part of a bear case.
What the order books do and do not explain
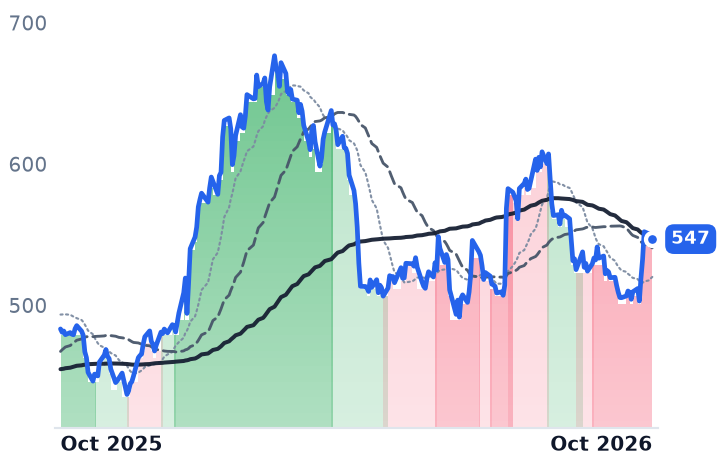
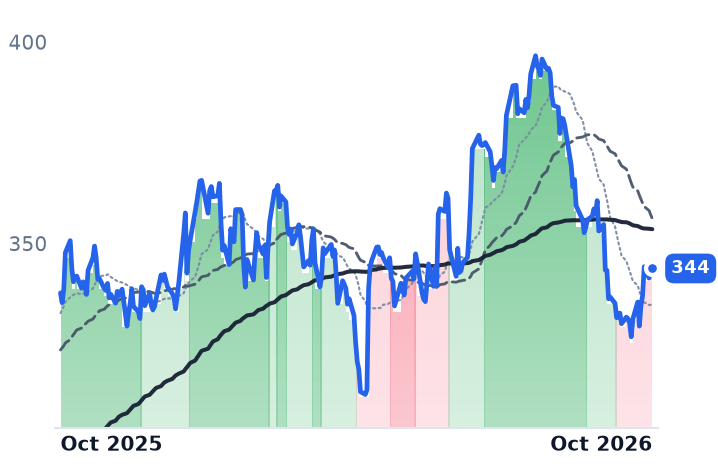
None of the three order books explains the de-rating; neither drawdown traces to a dated catalyst, with no single session worse than about 3% for either L3Harris or DRS. The dividing line is whether a company's revenue has already been appropriated. Lockheed Martin and Northrop Grumman each rose about 2% over thirty days, while AeroVironment lost 28.5% and Kratos 20.8% — both dependent on programs the stopgap will not let the Pentagon begin. DRS sits between: funded backlog at a record, and a premium multiple that needed the new starts to justify it.
Both L3Harris and Leonardo DRS report third-quarter results on 29 October, six weeks before the stopgap expires. Until the appropriation passes, the safest thing a defense contractor can own is a contract somebody already signed.