

AppFolio's Growth Comes From Fees on Rent Payments, Not From Signing Up More Apartments
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
A property-management software company that collects most of its money from transactions rather than subscriptions is the weakest performer in a group that has spent three months re-rating on the view that artificial intelligence will not hollow out software subscriptions after all. Of AppFolio's $281.1m of June-quarter revenue, $219.5m was fees on rent payments, tenant screening and insurance, and that line grew 22% while the units on the platform grew only 8% to 9.6 million.
The business supports the recovery: revenue up 19.3%, operating margin to 18.8% from 17.2%, guidance raised. The de-rating does not have much left to give back, though. On unchanged consensus earnings the shares sit at roughly 95% of their year-ago multiple, so further gains have to come from the fee count rather than from repair.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
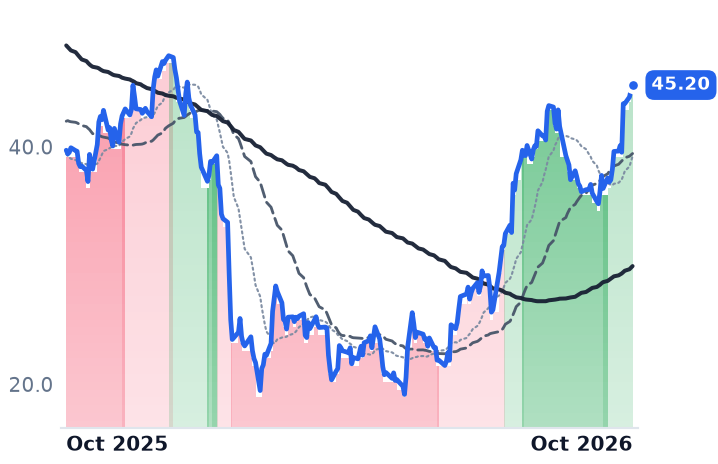
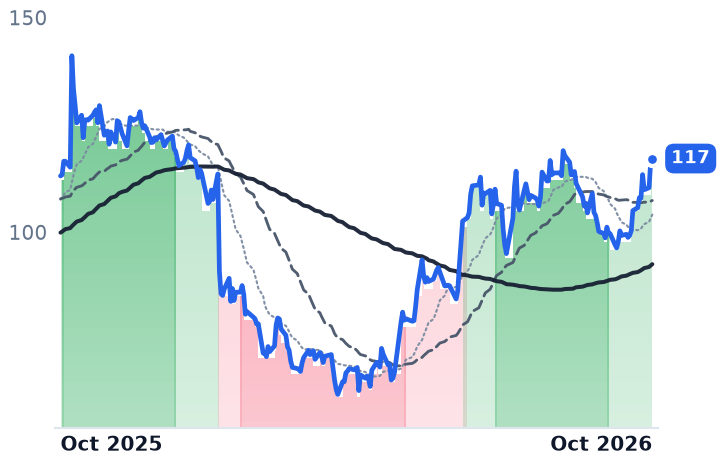
APPF | AppFolio | Industry-Specific Platforms | 🌱 Emerging Bull | +7.6% | −5.3% |
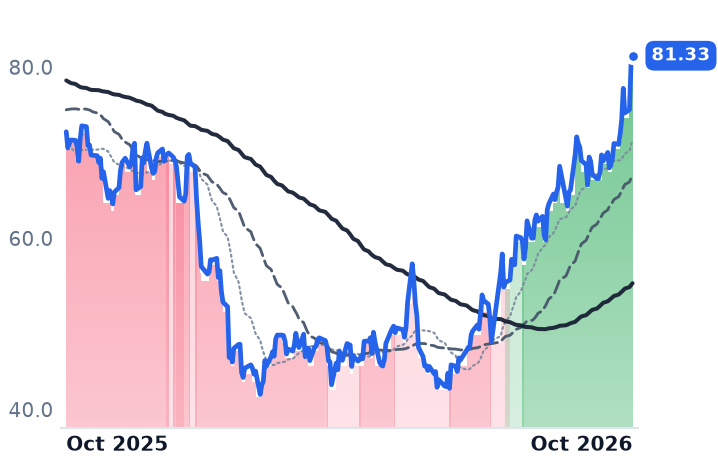
DSGX | The Descartes Systems | Industry-Specific Platforms | 🌱 Emerging Bull | +17.4% | −4.5% |
MANH | Manhattan Associates | Industry-Specific Platforms | 🟢 Cont. Bull | +13.1% | +15.3% |
BLKB | Blackbaud | Industry-Specific Platforms | 🌱 Emerging Bull | +26.8% | −16.8% |
INTA | Intapp | Sales, Service & Customer Management | 🌱 Emerging Bull | +24.2% | +13.8% |
DOCU | DocuSign | Software Development & Design | 🌱 Emerging Bull | +18.5% | +12.3% |
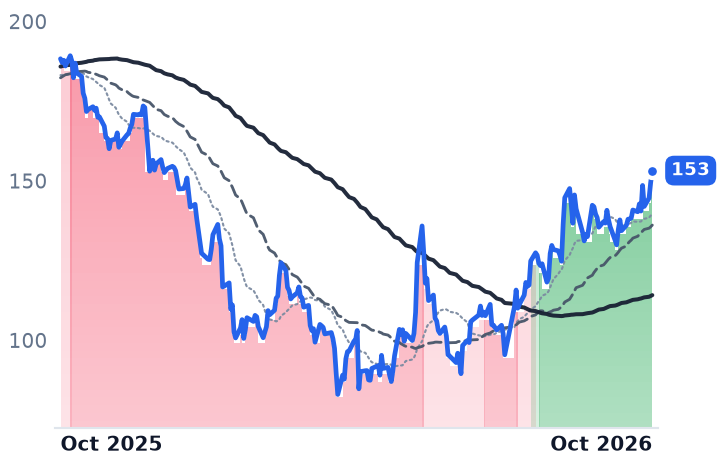
NOW | ServiceNow | Sales, Service & Customer Management | 🌱 Emerging Bull | +11.7% | −18.6% |
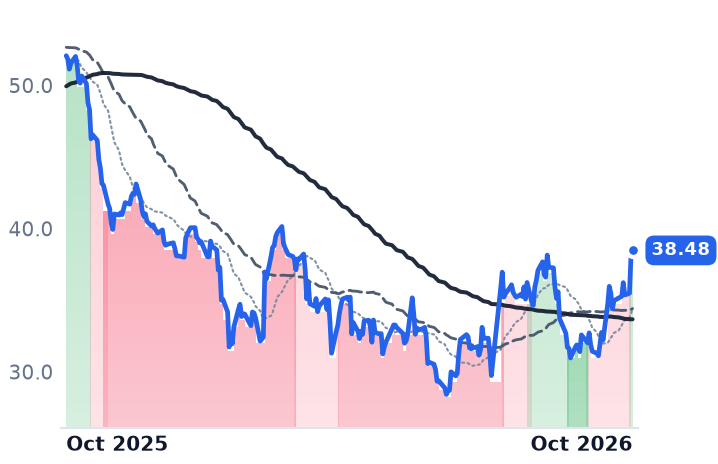
BSY | Bentley Systems, Incorporated | Software Development & Design | 🌱 Emerging Bull | +19.7% | −26.1% |
AGYS | Agilysys | Industry-Specific Platforms | 🟢 Cont. Bull | +17.5% | +3.6% |
ROP | Roper Technologies | Enterprise Resource Planning | 🌱 Emerging Bull | +7.8% | −22.1% |
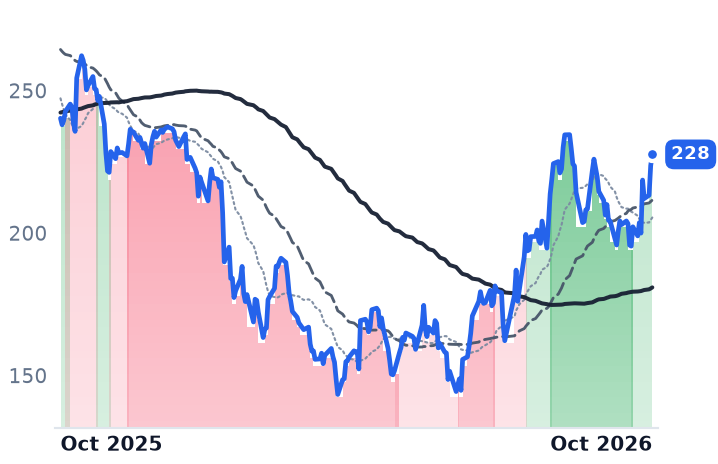
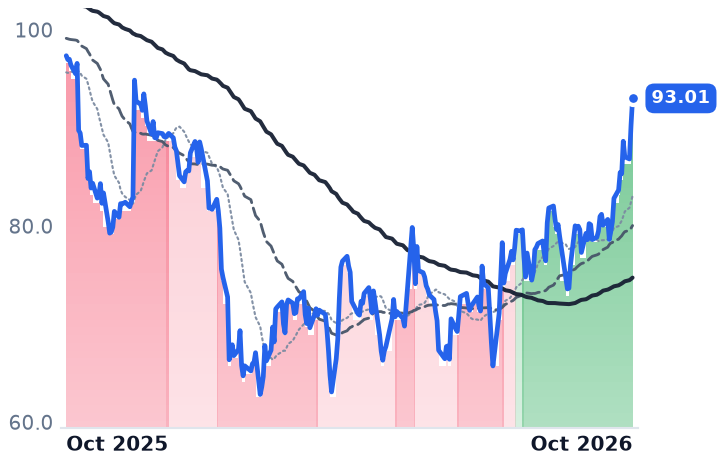
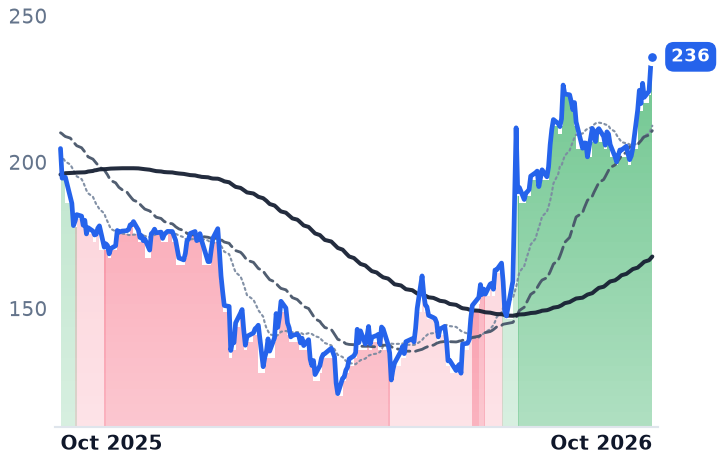
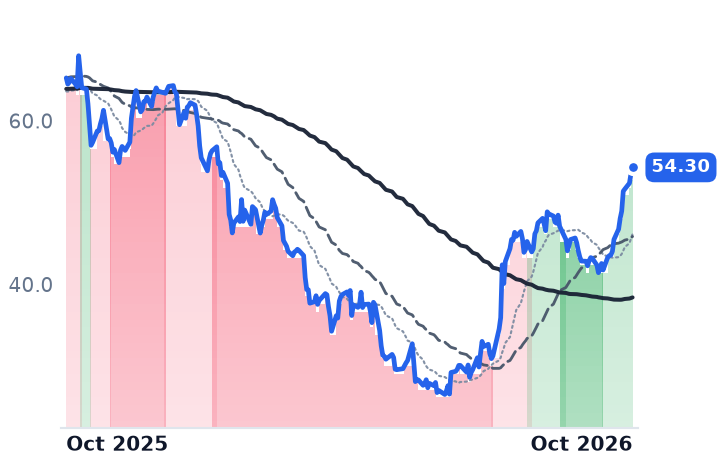
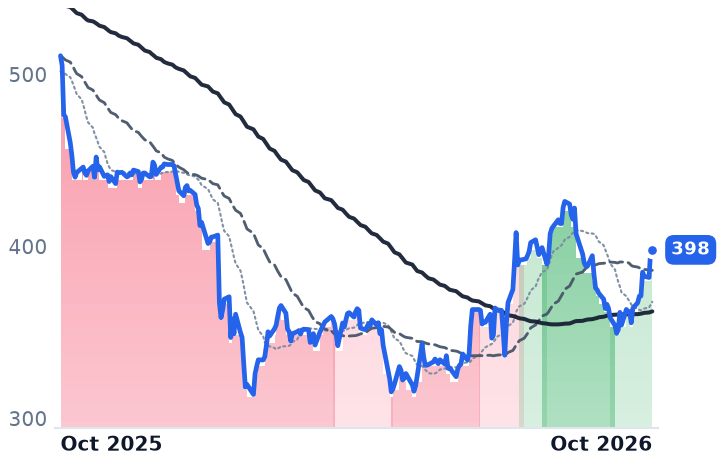
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
APPF | $8.0B | 51.1x | 32.7x | 7.7x | 7.1x | 12.2x | 11.3x | 37.4x | 3.4% |
DSGX | $7.9B | 42.2x | 39.7x | 10.2x | 9.5x | 13.1x | 12.3x | 22.3x | 3.8% |
MANH | $13.7B | 67.0x | 42.9x | 12.2x | 11.8x | 22.3x | 21.6x | 46.9x | 2.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BLKB | $2.4B | 16.5x | 10.2x | 2.1x | 2.1x | 3.6x | 3.5x | 11.1x | 11.4% |
INTA | $3.5B | n/m | 28.2x | 6.0x | 5.2x | 7.9x | 6.9x | n/m | 4.0% |
DOCU | $15.2B | 48.6x | 17.6x | 4.5x | 4.3x | 5.7x | 5.4x | 26.3x | 7.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NOW | $158.5B | 95.2x | 37.6x | 10.8x | 9.8x | 14.4x | 13.1x | 47.1x | 2.9% |
BSY | $11.2B | 42.0x | 27.5x | 7.0x | 6.6x | 8.6x | 8.1x | 25.7x | 4.4% |
AGYS | $3.3B | 76.5x | 47.7x | 10.0x | 8.9x | 16.0x | 14.3x | 49.4x | 2.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ROP | $39.3B | 16.5x | 17.9x | 4.8x | 4.6x | 6.8x | 6.6x | 11.7x | 6.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
APPF | Revenue | +18.5% | +17.2% | +16.9% |
| EPS | +33.9% | +22.0% | +23.5% | |
DSGX | Revenue | +15.0% | +12.7% | +12.8% |
| EPS | +15.8% | +24.8% | +15.6% | |
MANH | Revenue | +8.3% | +8.5% | +8.8% |
| EPS | +10.3% | +11.7% | +15.9% | |
BLKB | Revenue | +4.5% | +4.6% | +3.2% |
| EPS | +18.8% | +13.8% | −37.2% | |
INTA | Revenue | +14.7% | +14.6% | +15.0% |
| EPS | +36.8% | +29.9% | +22.3% | |
DOCU | Revenue | +8.4% | +9.2% | +8.0% |
| EPS | +6.9% | +22.1% | +12.8% | |
NOW | Revenue | +22.4% | +18.8% | +18.6% |
| EPS | +17.1% | +23.2% | +21.3% | |
BSY | Revenue | +13.6% | +10.5% | +10.2% |
| EPS | +18.5% | +12.4% | +16.3% | |
AGYS | Revenue | +16.5% | +16.6% | +16.9% |
| EPS | +26.9% | +49.3% | +30.3% | |
ROP | Revenue | +8.1% | +5.9% | +5.6% |
| EPS | +11.5% | +9.9% | +8.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
AppFolio sells cloud software to American property managers, and most of what it collects is not a subscription. Of $281.1m in June-quarter revenue, $219.5m came from value-added services — electronic rent payments, FolioScreen tenant screening, FolioGuard risk cover — against $59.8m of core subscription revenue, according to the company's results exhibit. The company reports third-quarter results after the close on Thursday 22 October, with consensus at $1.79 a share on revenue of $294.19m.
That split matters because the year's de-rating in application software ran on an argument about seats: that artificial-intelligence agents would eat the per-user subscription. The argument has reversed, hard — the software index has risen 21.92% over three months while investors concluded AI is being embedded in existing platforms rather than replacing them. "AI has been more of an enabler for a lot of these software companies, more than a disruptor," Adam Turnquist, chief cross-asset strategist at LPL Financial, said in October. Yet the least seat-dependent name in the specialized enterprise software group is its laggard: AppFolio is up 7.6% over 30 days against the index's near-11% month.
The fee meter runs on move-ins, not rent increases
Value-added services revenue grew 22% year on year to $219m while units under management grew 8% to 9.6 million. More fees are being charged against each unit, because each unit is transacting more payments, screens and policies.
What drives that is tenant turnover rather than rent inflation, and turnover is improving. Year-to-date US multifamily net absorption reached nearly 350,000 units, up 14% year on year, while deliveries fell 25% to just over 250,000, RealPage's analytics unit reported, with effective asking rents up only 0.9% and occupancy at 95.4%. Every one of those leases carries a screening fee and a new payment relationship. On rents themselves the data disagree: Apartments.com puts asking rents up 2.3% to $1,950, a gap that reflects effective-versus-asking methodology. Both describe a recovery from the 2024-25 trough. A rate headwind sits underneath it: the Federal Reserve raised its target range to 3.75-4.00% on 16 September, its first increase in three years, and higher financing costs slow property transactions.
Profit is growing about 60% faster than revenue
June-quarter revenue rose 19.3%, operating margin widened to 18.8% from 17.2%, and operating income rose 30.8%. The deceleration in the top line has been gentle — 21.9%, then 20.4%, then 19.3% — against 19.7% for full-year 2025. The transformation underneath is larger: annual operating margin has gone from -15.3% in 2022 to 16.1% in 2025 on revenue of $950.8m. Full-year 2026 revenue guidance was raised to $1.117-1.127bn with non-GAAP operating margin guided to 26.5-28.0%.
"For the first time, we've crossed $1 billion in revenue on a trailing twelve-month basis, a milestone we believe reflects the success customers are having by adopting our products and services," Shane Trigg, chairman and chief executive, said in prepared remarks on 23 July.
The socket is contested. RealPage and Yardi Systems are both larger by revenue; AppFolio's strength is the mid-market, where more than 10,000 property-management companies use the platform, and third-party share estimates for the category conflict sharply enough to be read only as directional.
The repair trade is mostly done
The group's recovery has tracked the depth of each member's fall rather than how it bills: the deepest drawdowns produced the biggest bounces, and AppFolio's 45.3% decline to a 10 April low was middling, so its 58.8% recovery is too. Its lag is therefore not a verdict on the fee meter. The meter is the part of the story with evidence behind it.
What has gone is the discount. On unchanged consensus earnings of $6.90, the shares implied roughly 20.8x at the April low and about 33.0x now, against 34.8x a year ago — some 95% of the way back, with the price still 5.3% below its year-ago close. That consensus is a non-GAAP line, and the distance is not small: second-quarter non-GAAP earnings were $1.71 a share against $1.17 reported, and KeyCorp models $5.21 for 2026. On forward price to gross profit, where margins spanning 53% to 78% across the group are neutralized, AppFolio stands at 11.3x against Manhattan Associates' 21.6x — the cheaper of the two, on faster growth.
So the business explains the recovery and the multiple explains what is left of it: from here the gains have to be earned by the fee count, not handed back by a reversing discount. Thursday's report is the first read on whether units and transactions per unit are still diverging the right way, and the line to watch is not the rent roll. A transaction meter only spins when somebody moves.