

A 195-Week Wait for Gas Engines Caps Archrock's Fleet and Fills Enerflex's Order Book
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Two gas compression lessors have been marked down hard through the autumn while every meter that sets a compression dollar improved. Kodiak Gas Services' average price reached $23.80 per revenue-generating horsepower per month, up 4.5%, on 98.2% fleet utilisation and record quarterly adjusted EBITDA of $216.8m; Archrock's contract operations revenue rose 3% at a 71% adjusted gross margin.
What soured sits outside the lease: Archrock's parts-and-overhaul book fell 35% year on year, and make-ready and lube-oil costs took $30m off the top of its EBITDA guidance. Enerflex, filed on the same industry shelf, is a manufacturer rather than a lessor — its Engineered Systems backlog went from $1.1bn to $1.5bn — and the engine shortage that caps the lessors' fleet additions is what is filling its factories.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
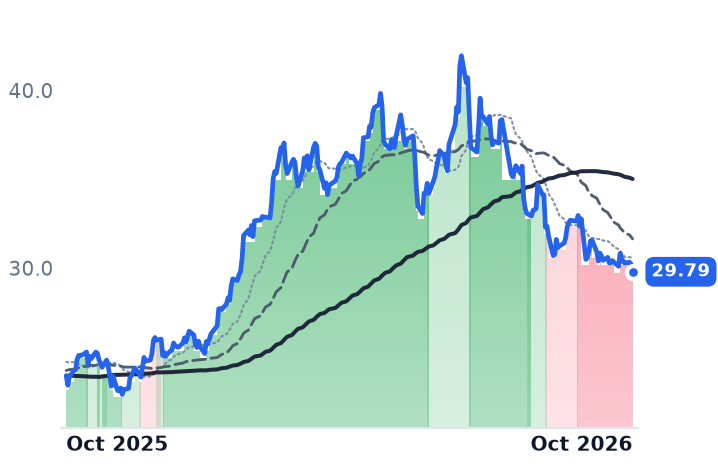
AROC | Archrock | Compression & Gas Processing | ⚠️ Emerging Bear | −2.6% | +24.5% |
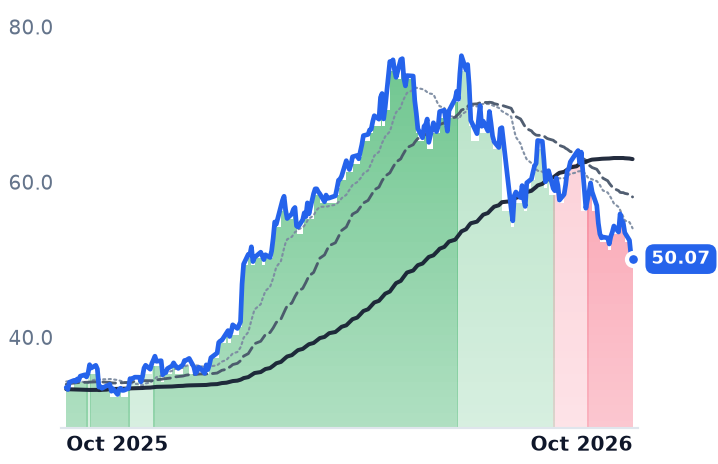
KGS | Kodiak Gas Services | Compression & Gas Processing | ⚠️ Emerging Bear | −13.2% | +49.3% |
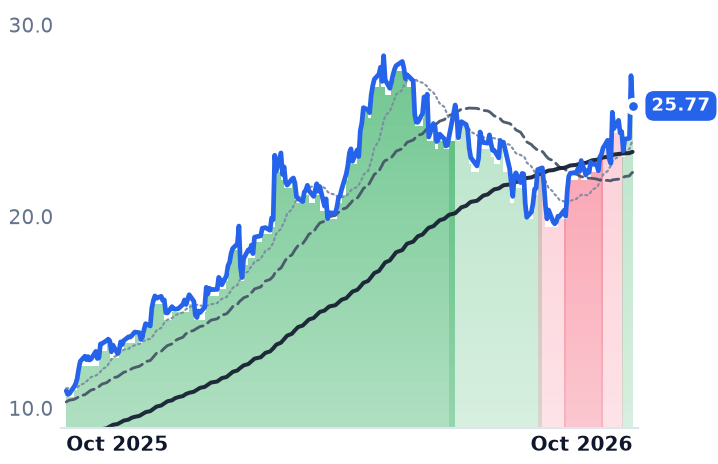
EFXT | Enerflex | Compression & Gas Processing | ⚠️ Emerging Bear | +15.0% | +136.3% |
| Compared against · context, not the story | |||||
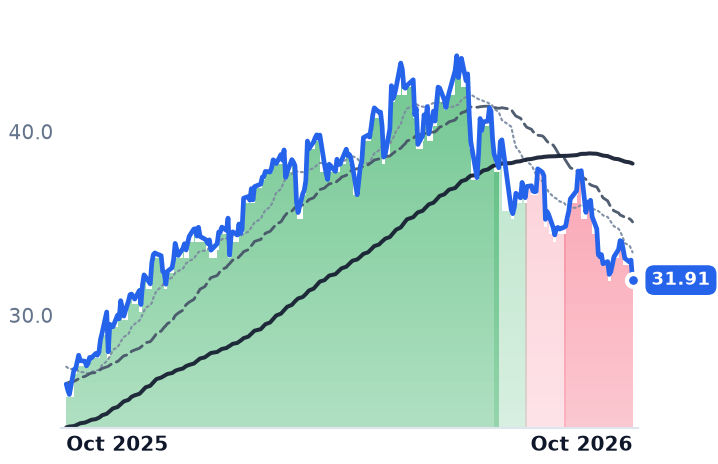
NGS | Natural Gas Services | Compression & Gas Processing | ⚠️ Emerging Bear | −11.8% | +21.6% |
USAC | USA Compression Partners | Compression & Gas Processing | ⚠️ Emerging Bear | −5.6% | +15.2% |
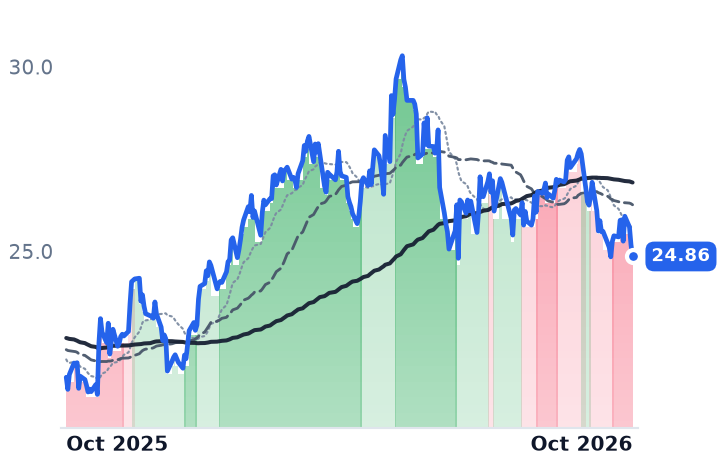
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AROC | $5.2B | 16.0x | 17.3x | 3.5x | 3.4x | 6.0x | 5.9x | 9.4x | 5.6% |
KGS | $5.1B | 56.9x | 25.3x | 3.6x | 3.3x | 9.1x | 8.3x | 8.3x | 0.1% |
EFXT | $3.1B | 47.8x | 13.3x | 1.1x | 0.9x | 4.8x | 4.0x | 7.8x | 9.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NGS | $481.1M | 23.4x | 21.9x | 2.5x | 2.2x | 5.7x | 5.1x | 7.8x | -6.5% |
USAC | $4.0B | 25.9x | 21.5x | 3.4x | 2.9x | 7.6x | 6.5x | 10.4x | 7.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
AROC | Revenue | +1.9% | +7.6% | +7.7% |
| EPS | +9.4% | +19.2% | +15.9% | |
KGS | Revenue | +16.3% | +14.9% | +17.6% |
| EPS | +77.8% | +43.1% | +38.7% | |
EFXT | Revenue | +0.8% | +11.7% | +31.6% |
| EPS | +23.0% | +37.5% | +39.5% | |
NGS | Revenue | +25.8% | +18.8% | +8.3% |
| EPS | +7.2% | +45.8% | +14.5% | |
USAC | Revenue | +37.8% | +6.9% | +4.6% |
| EPS | +38.5% | +26.7% | +20.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Gas engines for new compressor packages now take about 195 weeks to arrive, and the orders going in are for 2029 delivery. Brad Childers, Archrock's president and chief executive, told investors as much on the company's August call: "For equipment required, lead times are now at 195 weeks with ordering for 2029." The cause sits outside the oilfield. Hyperscale data-centre demand has pushed engine manufacturers to full production, limiting engine availability for the gas compression industry, where waits traditionally ran 40 to 60 weeks.
That one constraint splits a group the market prices as a single shelf. Archrock and Kodiak Gas Services lease horsepower by the month and have been read as geared to the gas price and the drill bit; both inputs moved the wrong way for that reading. Henry Hub was $3.03 per million British thermal units on 6 October, down 8.7% from a year earlier, while the US rig count reached 603, some 56 rigs above last year, with the Permian at 274. Meanwhile the numbers that actually set a lease dollar went up.
A compression dollar is a monthly fee, and the fee rose
Revenue in contract compression is three numbers multiplied: horsepower on revenue-generating contracts, a monthly rate per horsepower, and utilisation. Kodiak, the large-horsepower operator concentrated in the Permian Basin, reported average pricing of $23.80 per revenue-generating horsepower per month in the June quarter, up 4.5% year on year, with compression fleet utilisation at 98.2% against 97.2% and compression adjusted gross margin 1.7 points wider at 70%. Adjusted EBITDA of $216.8m was a company record, up 22%, and Kodiak raised full-year EBITDA and discretionary cash flow guidance in the same release.
Archrock, which operates roughly 35% of the US outsourced compression market, showed the same shape. Contract operations revenue rose 3% to $329.3m, period-end utilisation was 94.4%, and adjusted gross margin was 71% against 70%; the operating fleet shrank from 4.7m horsepower to 4.5m because Archrock sold about 165,000 non-strategic horsepower. The same release disclosed an agreement with an existing strategic customer covering approximately 665,000 horsepower on an eight-year base term with a two-year extension. Compression demand follows the producing well count and the rising gas-to-oil ratio of ageing Permian wells, which calls for more horsepower per barrel even when the oil rig count flattens.
Archrock's shortfall sat in parts and overhauls
Where Archrock did disappoint, the mechanism lives away from the lease. Aftermarket services, the parts and maintenance book billed on customer-owned units, took $42.0m against $64.8m a year earlier, about 11% of group revenue; the company attributed the fall to the absence of non-recurring sales of overhauled engines and to customers skipping the usual mid-year maintenance uptick. Full-year aftermarket revenue is guided to $175m-$185m. The top of EBITDA guidance came down to $885m from $915m on four items: make-ready cost to put idle units back to work, second-half lube-oil pressure, the weaker aftermarket and higher long-term incentive compensation. Contract operations margin guidance held at 71.0%-71.5%. Childers called 2026 "a bit like the calm before the storm".
Enerflex sells what the lessors cannot get
Enerflex earns its money the other way: it manufactures compression and gas-processing packages, recognising Engineered Systems revenue as projects are built, and separately owns build-own-operate infrastructure carrying about $1.2bn of contracted revenue. Engineered Systems bookings were $488m in the June quarter against a trailing eight-quarter average of $363m, a 1.5x book-to-bill for the first half, with backlog up to $1.5bn from $1.1bn at the end of 2025. Then came the power awards: 450 MW of gas-fired generation for a North American data-centre developer on 1 October, and on 13 October more than a gigawatt, taking behind-the-meter backlog above 1.75 GW with deliveries through 2028. Enerflex also authorised roughly $85m of extra Engineered Systems facility investment, mostly for 2027 — a manufacturer adding factory capacity while the lessors stand in the engine queue.
The shares have moved accordingly. Over the three months to 14 October Archrock fell 22.7% and Kodiak 27.5%, while Enerflex rose 6.2% and has been in an uptrend since 7 October. Archrock's turn came at the earnings event itself, from $35.74 on 4 August to $33.08 on 7 August. Kodiak sits 34% below its twelve-month high and 29.5% below the $71.00 at which it sold 10.56m shares for about $758m in May, a raise that lifted diluted shares 10.6% in one quarter to 96.8m.
Cheaper than May, and one of them cheaper still
Archrock at $29.79 trades at 5.97x trailing gross profit, against 7.12x in May, on 9.4x trailing EV/EBITDA and a 5.6% free cash flow yield. Kodiak's forward price-to-earnings is 25.3x, against roughly 29x in May; the honest offset is a 0.10% trailing free cash flow yield and credit-agreement leverage of 3.2x, the cost of a fleet in growth mode.
Enerflex, up 137.5% over twelve months, is the cheapest of the three on price-to-gross-profit at 4.05x forward. That is the comparable measure because the margins differ by a factor of three: 23.9% gross margin at Enerflex against Archrock's disclosed 71% adjusted figure makes price-to-sales meaningless across them.
So the lessors' autumn is a change in what the market will pay for horsepower rather than a change in what horsepower earns. What the results do explain is narrower and real: Archrock's second, thinner dollar shrank by a third, and Kodiak's fastest-growing line is its least profitable, with Other Services revenue up 47% to $43.1m and guided at a 13%-16% adjusted gross margin against 70% on the lease, so mix alone can move reported margin. Kodiak's power optionality is also unsigned. Of the West Texas data-centre project, chief executive Mickey McKee said on the August call: "We've invoiced them for an initial deposit to reserve power equipment for the project while we negotiate a long-term contract." Neither lessor has reported since; Archrock's quarter is expected around 27 October and Kodiak's around 3 November.
Archrock says the industry needs roughly a million more horsepower to meet forecast gas demand growth by the end of the decade, and has set out growth capital predominantly for large-horsepower and electric-motor-drive units. The engines for it are already on order. Whoever holds a place in that queue sets the next lease rate.