

Equinix and Digital Realty Both Accelerated Into a Selloff That Hit Every Kind of REIT
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
The shelf these two landlords sit on is labelled as weakening data-center demand. Their June quarters say the opposite. Equinix's revenue growth went from 9.8% to 16.4% year on year between the March and June quarters, and Digital Realty signed more than $261m of renewals at cash re-leasing spreads above 25%, with hyperscale renewals above one megawatt repricing 66.7% higher.
What moved was the discount rate. The 10-year Treasury yield rose from 4.68% in mid-August to 5.28% on 2 October, and the median share price across 158 listed real estate investment trusts fell about a tenth. Equinix's price-to-gross-profit has compressed to 19.1x from 21.6x in May.
Two qualifiers belong in the record: Equinix's interconnection revenue grew only 9%, slower than its rent, and $0.52 of Digital Realty's $2.65 of Core funds from operations per share was joint-venture promote income rather than rent.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
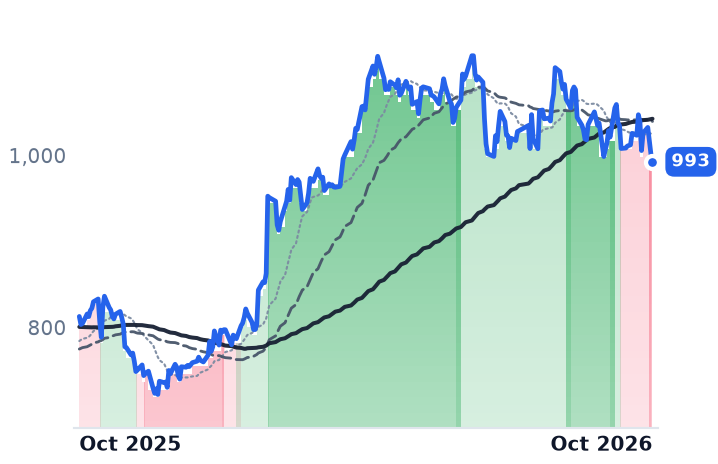
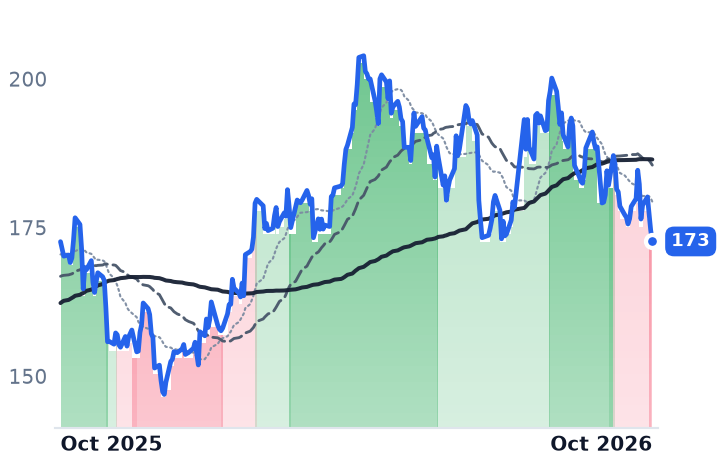
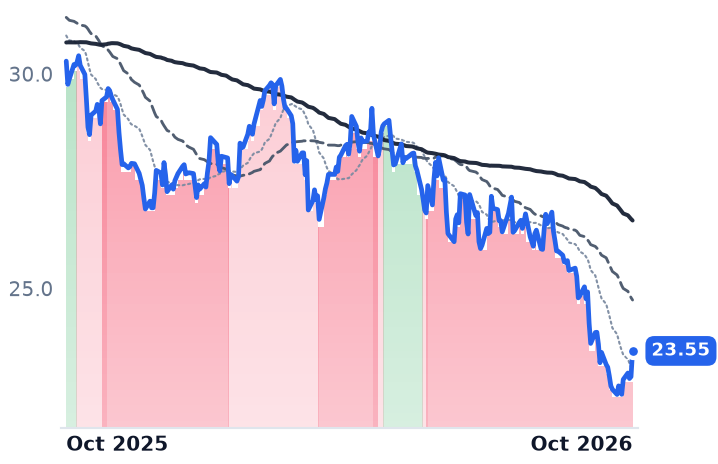
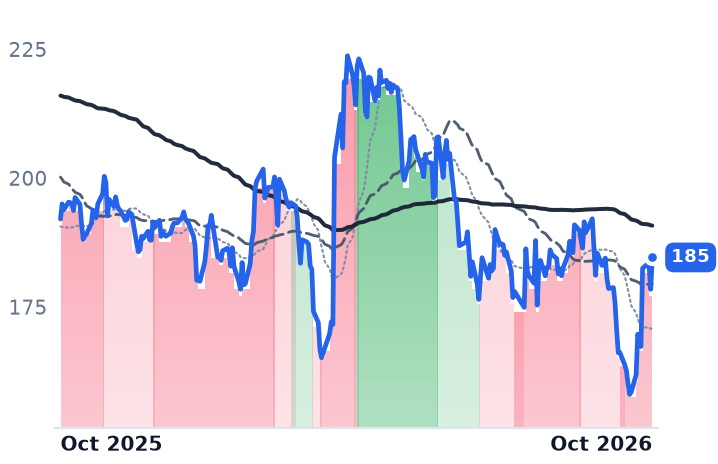
EQIX | Equinix | Data Center Operators | 🟢 Cont. Bull | −1.4% | +22.1% |
DLR | Digital Realty Trust | Data Center Operators | 🟢 Cont. Bull | −3.7% | +0.0% |
| Compared against · context, not the story | |||||
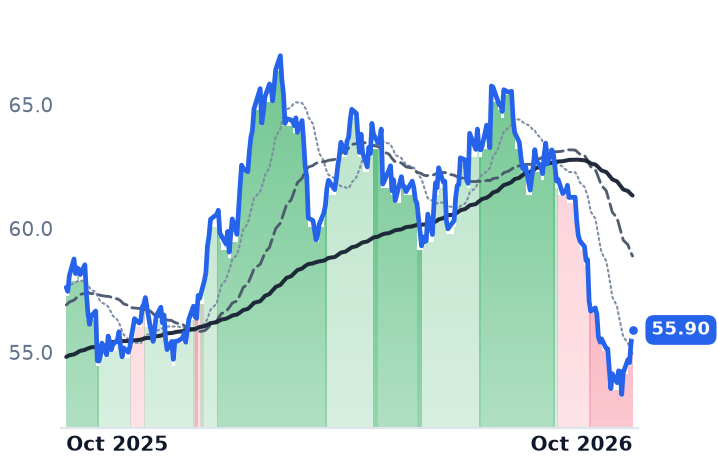
O | Realty Income | Single-Tenant Net Lease | ⚠️ Emerging Bear | −4.8% | −3.0% |
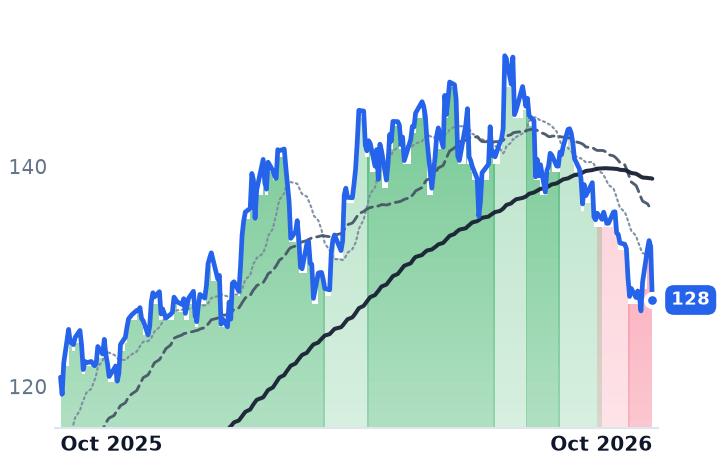
PLD | Prologis | Industrial Logistics | ⚠️ Emerging Bear | −5.9% | +5.8% |
VICI | VICI Properties | Gaming & Hospitality | 🔴 Cont. Bear | −4.9% | −22.3% |
SBAC | SBA Communications | Tower & Fiber Infrastructure | 🔴 Cont. Bear | +0.8% | −3.9% |
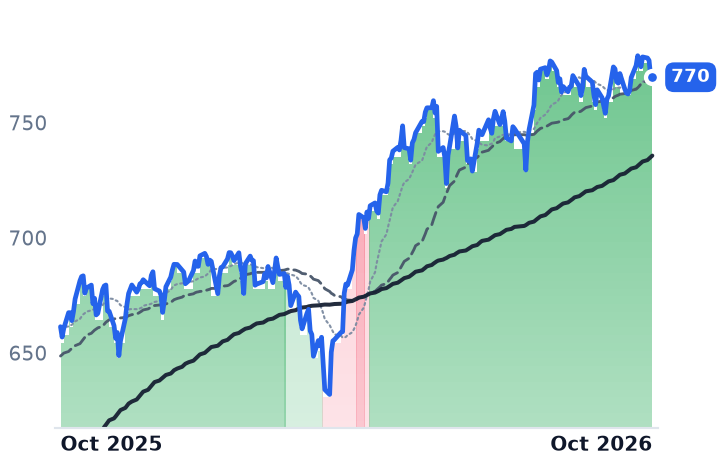
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | +1.6% | +16.4% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EQIX | $97.0B | 63.1x | 57.2x | 9.9x | 9.4x | 19.1x | 18.3x | 26.6x | 1.4% |
DLR | $63.6B | 79.0x | 62.4x | 9.3x | 8.9x | 67.5x | 64.9x | 23.5x | 2.1% |
O | $52.2B | 40.3x | 36.3x | 8.8x | 9.2x | 12.8x | 13.4x | 12.2x | 4.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
PLD | $120.4B | 28.7x | 35.1x | 13.1x | 14.0x | 45.1x | 48.1x | 18.6x | 4.4% |
VICI | $25.3B | 8.9x | 8.3x | 6.2x | 6.0x | 6.2x | 6.1x | 11.7x | 10.4% |
SBAC | $19.4B | 19.6x | 23.7x | 6.7x | 6.8x | 10.6x | 10.6x | 17.0x | 5.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
EQIX | Revenue | +11.1% | +10.8% | +11.6% |
| EPS | +16.6% | +10.4% | +10.1% | |
DLR | Revenue | +17.5% | +11.0% | +14.4% |
| EPS | −25.0% | −6.2% | +24.6% | |
O | Revenue | +7.4% | +4.9% | +9.9% |
| EPS | +26.1% | +10.1% | −2.4% | |
PLD | Revenue | +5.6% | +9.4% | +7.5% |
| EPS | +33.6% | −5.2% | +13.2% | |
VICI | Revenue | +5.2% | +3.5% | +2.8% |
| EPS | +0.5% | +7.7% | +3.1% | |
SBAC | Revenue | +1.5% | +2.5% | +3.6% |
| EPS | −21.8% | +8.2% | +10.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Equinix raised both its 2026 guidance and its long-term outlook when it reported the June quarter on 29 July, and its shares have drifted lower ever since. Digital Realty had done the same thing six days earlier, on the back of a record backlog of leases signed but not yet billing.
The slide in listed data-center shares through the autumn has been read as the AI leasing cycle cracking. At these two names it cannot be: neither has disclosed an operational number since July. Equinix's third-quarter call is scheduled for 28 October and Digital Realty releases on 29 October. What the last filed quarters show is acceleration on both sides.
Cabinets and kilowatts, billed monthly
Equinix is a specialty real estate investment trust with 273 colocation facilities in 36 countries, renting cabinet space and billable power to more than 10,000 customers and charging separately for the cross-connects between them. Its revenue line is structurally late: it bills recurring rent on capacity already installed, while the growth investors are pricing sits in leases signed and not yet commenced. The line accelerated anyway, from 9.8% year-on-year growth in the March quarter to 16.4% in June, against 5.2% in the September 2025 quarter. Operating margin went from 21.9% to 25.3% over the year, with operating income rising more than twice as fast as sales. Adjusted funds from operations reached $11.78 a share, up 18% normalized and in constant currency, and annualized gross bookings of $424m were the second-highest the company has recorded.
"The AI-driven infrastructure cycle continues to accelerate, and it's playing directly to our strengths," chief executive Adaire Fox-Martin told investors on the 29 July call. "Demand for neutral, interconnected, sovereign infrastructure is compounding across our business."
One meter dissents. Interconnection — the near-pure-margin annuity of cross-connects between tenants already in the building, and the quantified basis of the moat at over 500,000 live connections — brought in $453m in the quarter, up 9%, roughly 17% of revenue. That is slower than monthly recurring revenue at 11% and slower than the rent, even with a record 9,700 net interconnections added. Monthly recurring revenue per cabinet was $2,538 and churn ran at 1.8%, below the company's usual 2.0%-2.5%, though management attributed part of that to delayed churn and renewal timing.
The cost-of-capital link is explicit. Equinix lifted 2026 capital spending to $5bn-$6bn from $3bn-$4bn and guided $5bn-$7bn a year through 2029 across 52 projects, to be funded with debt: $8bn refinanced plus $8bn incremental, with average cost of debt expected to rise to about 4.9% from 3.4%. Shares at 19.1x trailing gross profit compare with 21.6x in May.
A quarter of Digital Realty's earnings was not rent
Digital Realty operates 309 data centers, 89 of them held through unconsolidated joint ventures, with about 3.0 gigawatts in service and selling wholesale multi-megawatt blocks to hyperscalers. Its backlog of signed-but-uncommenced leases hit $1.9bn at 100% share, close to 30% of in-place data-center revenue. Renewals priced up where the bear case said they would price down: above-one-megawatt hyperscale renewals, 44% of the $261m signed, repriced 66.7% higher on a cash basis. The development pipeline doubled in the first half to 1.4 gigawatts and $20bn of cost, 63% pre-leased at an expected 11.5% stabilized yield.
Two caveats travel with it. Roughly $0.52 of the $2.65 of Core funds from operations per share was $188m of net promote income on three data centers inside a development venture; stripped out, the figure is $2.13, up 14%. And the concentration is literal: two US hyperscale leases signed after the quarter closed carry about $410m of annualized rent at 100% share, while the largest single customer is 10.8% of annualized recurring revenue. Price-to-sales has compressed to 9.29x from 11.14x in May.
Bank of America had already cut the stock to Neutral, target $170 from $210, arguing the company "hasn't participated in AI-related demand at the level we anticipated" while keeping a Buy on Equinix; it reaffirmed that Neutral on 8 January, which makes the call context for the six-month fade rather than the trigger for October.
The repricing came from the bond market
Neither share price has crashed. Equinix is down 1.4% over thirty days and up 20.7% over twelve months; Digital Realty is down 3.7% and 1.4%. Over six months Equinix fell 5.7% and Digital Realty 11.8%, against Realty Income down 12.6%, Prologis 8.5% and VICI Properties 16.3%, while the S&P 500 tracker rose 10.0%. Across the same stretch the 10-year Treasury yield went from 4.68% in mid-August to 5.28% on 2 October and the median share price of 158 REITs fell 9.9%.
So the operating results account for none of the de-rating, and the likelier reading is a discount rate repricing contracted rent, with two aggravators: new listed data-center equity competing for the same allocation after Blackstone's infrastructure trust listed in May and Brookfield's Csquare floated in July, and a worry set of permitting moratoriums, tenant concentration and refinancing risk. The sensitivities differ by name. Equinix's is arithmetic on a debt-funded build program whose interest bill is set by the same yield that sets its multiple. Digital Realty's is composition — a slab of fee and promote economics plus a rent roll where one signature moves a quarter. "I'm not suggesting today is an end-of-the-world storm or anything like that," chief executive Andrew Power told CNBC on 15 September, adding that demand in his markets "has been outpacing supply now for several years."
The tenants' own books show where the money has gone and why none of it is visible yet in a landlord's revenue. Microsoft now carries $329.1bn of lease commitments that have not commenced — rent contracted, buildings unfinished, and nobody's income statement any the wiser until the meters are switched on.