

Fair Isaac's Mortgage Fee Is Charged Per Loan, and the Loan Count Is Forecast to Shrink
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Fair Isaac's credit-score royalty earns money the way a tollbooth does: a per-pull price the company sets itself, multiplied by a volume of mortgage closings it does not control. Both legs moved against it this month.
The company committed on 1 October to eliminating roughly 15% of positions for a $27m fourth-quarter charge, and on 11 October the Mortgage Bankers Association cut its 2027 forecast to 5.0 million loans from 5.3 million. The June quarter had shown what the price lever alone can do: Scores revenue up 41% to $458.9m, mortgage-origination revenue up 97% against a wholesale list price taken from $4.95 to $10.00, and score units up only low single digits.
The operations never deteriorated. Revenue grew 25.7% and operating margin reached 53.8%. But the 14.5x forward earnings rests on a fiscal-2027 consensus of $49.65 a share that still assumes the $10 list.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
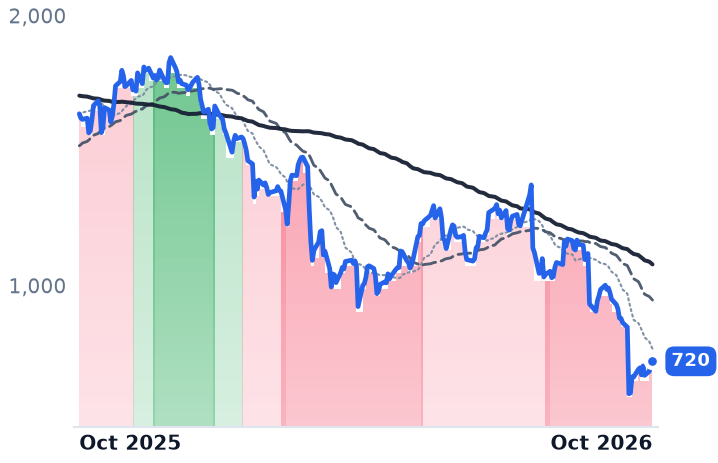
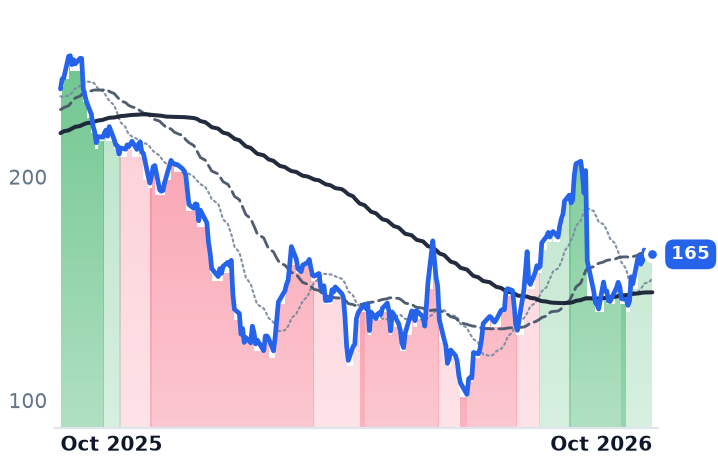
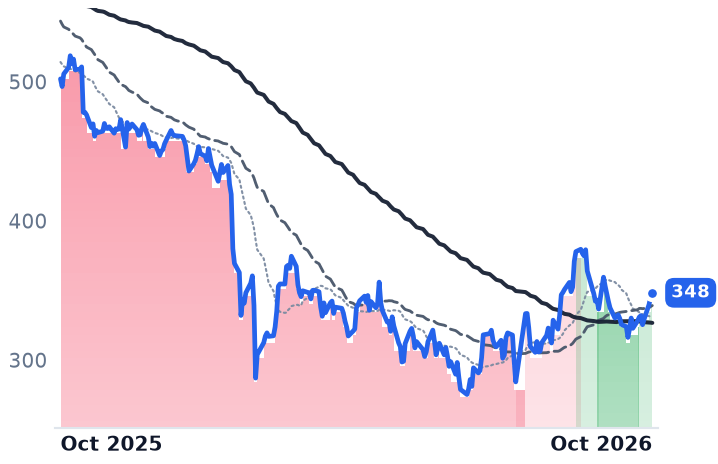
FICO | Fair Isaac | Financial Services Software | 🔴 Cont. Bear | −27.0% | −56.0% |
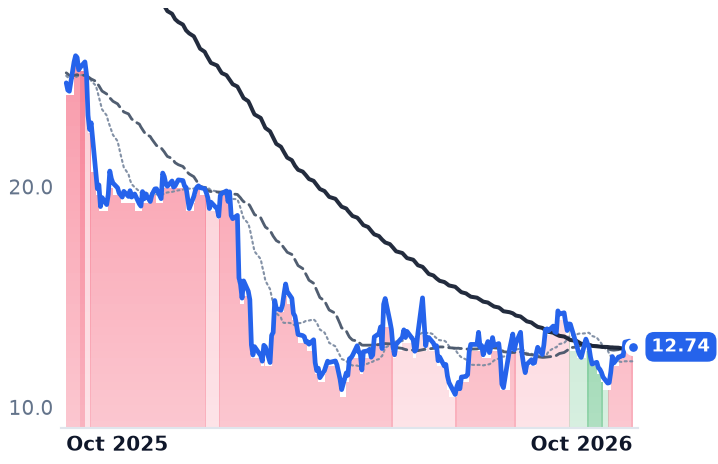
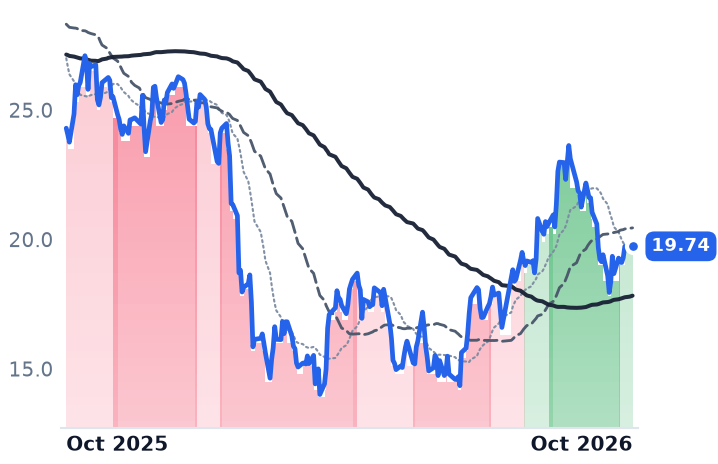
VERX | Vertex | Financial Services Software | 🔴 Cont. Bear | −1.2% | −48.4% |
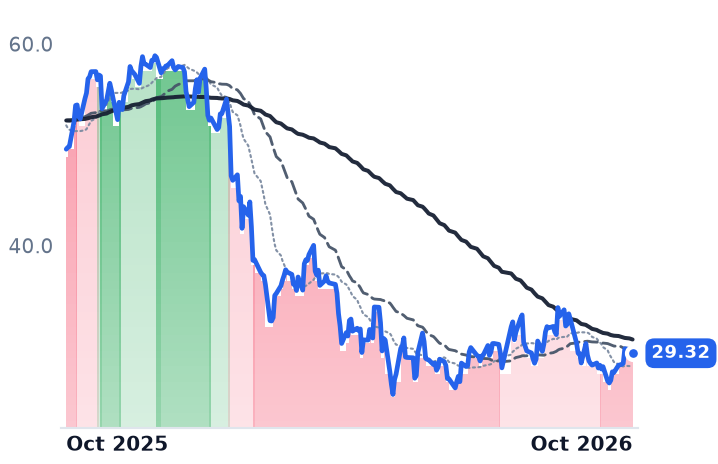
BL | BlackLine | Financial Services Software | 🔴 Cont. Bear | +0.6% | −40.8% |
| Compared against · context, not the story | |||||
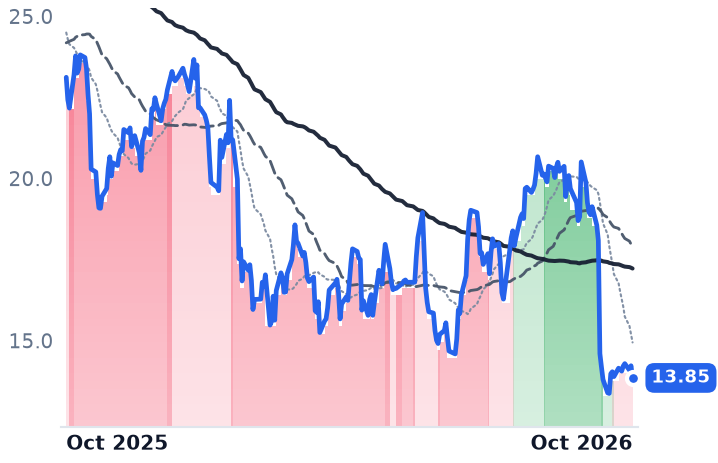
ALKT | Alkami Technology | Financial Services Software | 🌱 Emerging Bull | −28.1% | −40.1% |
GWRE | Guidewire Software | Financial Services Software | 🌱 Emerging Bull | +11.1% | −30.9% |
NCNO | nCino | Financial Services Software | 🌱 Emerging Bull | −9.9% | −18.8% |
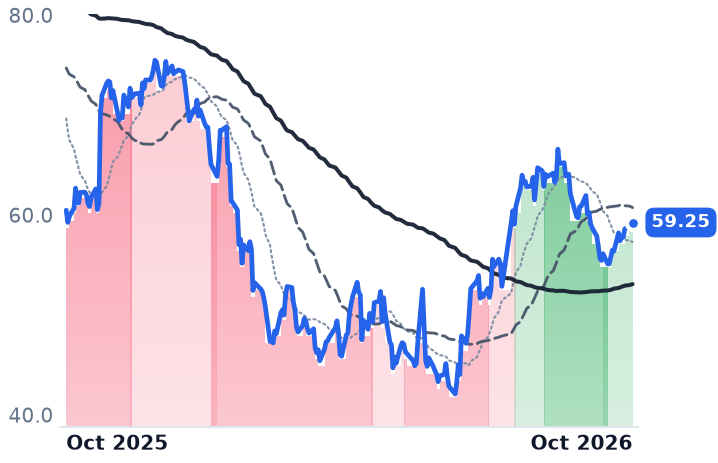
QTWO | Q2 | Financial Services Software | 🌱 Emerging Bull | −1.4% | −2.0% |
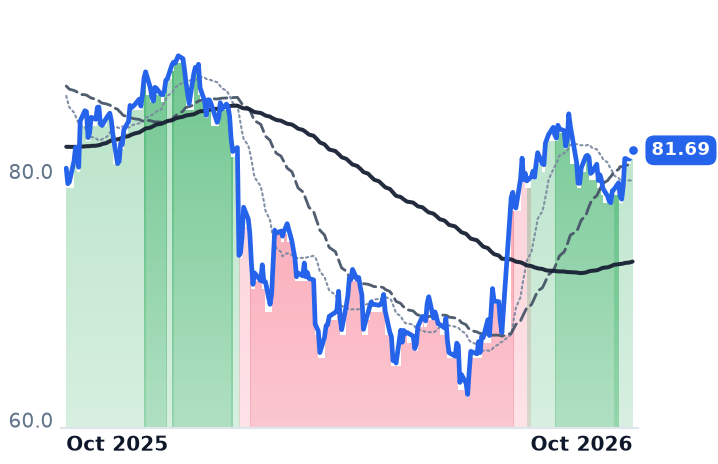
SSNC | SS&C Technologies | Financial Services Software | 🌱 Emerging Bull | +0.5% | +1.8% |
TYL | Tyler Technologies | Financial Services Software | 🌱 Emerging Bull | −1.4% | −30.6% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FICO | $15.5B | 20.7x | 14.5x | 6.5x | 5.6x | 7.6x | 6.5x | 16.5x | 6.4% |
VERX | $2.1B | 416.3x | 15.5x | 2.6x | 2.5x | 4.2x | 4.0x | 41.6x | 2.8% |
BL | $1.7B | 49.8x | 11.8x | 2.3x | 2.2x | 3.1x | 3.0x | 21.4x | 9.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ALKT | $1.5B | n/m | 18.0x | 3.1x | 2.9x | 5.4x | 5.0x | n/m | 4.3% |
GWRE | $14.0B | 101.9x | 40.1x | 9.5x | 8.1x | 14.8x | 12.7x | 67.0x | 2.1% |
NCNO | $2.2B | 63.6x | 15.1x | 3.5x | 3.3x | 5.6x | 5.4x | 26.1x | 6.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
QTWO | $3.7B | 39.9x | 20.4x | 4.4x | 4.2x | 7.6x | 7.3x | 24.4x | 5.5% |
SSNC | $18.7B | 22.3x | 11.2x | 2.8x | 2.8x | 5.9x | 5.7x | 11.7x | 9.4% |
TYL | $13.6B | 43.6x | 25.4x | 5.6x | 5.3x | 12.0x | 11.4x | 29.7x | 5.2% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
FICO | Revenue | +27.5% | +10.0% | +8.6% |
| EPS | +45.1% | +16.0% | +13.8% | |
VERX | Revenue | +10.6% | +10.5% | +11.5% |
| EPS | +28.4% | +23.9% | +21.1% | |
BL | Revenue | +9.5% | +10.4% | +10.3% |
| EPS | +19.7% | +10.9% | +18.0% | |
ALKT | Revenue | +19.6% | +16.7% | +14.5% |
| EPS | +51.0% | +37.7% | +21.9% | |
GWRE | Revenue | +23.8% | +17.2% | +15.7% |
| EPS | +41.5% | +20.8% | +27.4% | |
NCNO | Revenue | +9.8% | +9.0% | +8.5% |
| EPS | +25.2% | +44.5% | +20.0% | |
QTWO | Revenue | +11.8% | +10.1% | +10.6% |
| EPS | +22.1% | +19.5% | +32.6% | |
SSNC | Revenue | +8.6% | +5.0% | +4.8% |
| EPS | +17.2% | +9.6% | +7.4% | |
TYL | Revenue | +8.8% | +9.9% | +8.9% |
| EPS | +14.7% | +17.5% | +14.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Fair Isaac, the Bozeman, Montana company whose FICO credit scores lenders buy through Equifax, Experian and TransUnion, committed on 1 October to eliminating about 15% of its positions, a plan carrying roughly $27.0m of pre-tax charges in the fiscal fourth quarter, with affected employees notified from the week of 5 October. Ten days later the Mortgage Bankers Association cut the forecast that governs the company's largest profit line, putting 2027 originations by loan count at 5.0 million against the 5.3 million expected this year, with the 30-year mortgage rate averaging 7.3% in the current quarter and holding above 7% through next year.
September's collapse in the shares was read as a fight over which score lenders are allowed to use. The count is the other half of the machine. The royalty is a price Fair Isaac publishes multiplied by the number of times a lender pulls a score, and the company controls only the first term. The cost cut defends the margin on the dollars that arrive; it does nothing to the number of pulls, and that number is now forecast lower.
The June quarter was a price increase
How much of the growth was price is not a matter of inference. Scores revenue reached $458.9m in the June quarter from $324.3m, up 41%, with the business-to-business half up 49% "primarily attributable to a higher mortgage origination scores unit price"; mortgage-origination revenue rose 97% while mortgage score volumes grew low single digits. Mortgage was 62% of total Scores revenue. The list price behind that: Fair Isaac took its wholesale mortgage royalty from $4.95 to $10.00 a score for 2026, after moving it from $0.60 to $4.95 over the prior five years. A roughly 102% price step produced a 97% revenue gain, so units and mix contributed close to nothing.
The other business bears no resemblance to it. Software revenue grew 2% to $215m, with Platform annual recurring revenue up 62% to $413m and net retention of 148% on Platform against 82% on the older non-Platform book that is shrinking beneath it. One consolidated revenue line cannot say which half moved.
The $10 is harder to collect than it was
On 1 October the Federal Housing Finance Agency moved Fannie Mae and Freddie Mac to a single loan-level price adjustment grid for Classic FICO and VantageScore 4.0, removing a 20-point adjustment that had made the rival model's pricing less favorable. The bureaus that distribute FICO jointly own that rival: TransUnion has cut VantageScore 4.0 to $0.99 a score and supplies it free with a FICO purchase, and Equifax has priced it at $4.50 through end-2027, also free alongside FICO. Fair Isaac's answer routes around them: a direct licence for tri-merge resellers at $4.95 a score plus a $33 funded-loan fee, or $10 flat, the first option described by the company as a 50% reduction in average per-score fees into resellers.
"We're not crazy about lenders choice as a policy. We think it's bad policy because it encourages gaming," chief executive William Lansing said on the 29 July earnings call, adding that volumes were not falling, "which suggests that they're pulling both scores." Pulling both is what United Wholesale Mortgage has said it will do; Rocket Mortgage said in early October it will make VantageScore 4.0 its preferred model on all eligible loans from this quarter.
The cheap number nobody has cut
Nothing in the reported results explains the share price. Revenue grew 25.7% in the June quarter, operating margin widened to 53.8% from 48.9%, and diluted earnings were $10.45 against $7.40. The stock fell 16.7% on 4 September and 29.2% on 29 September, closed at $719.63 on 14 October, 56.4% below a year earlier, then rose 9.2% on 12 October and 6.75% on 13 October as Needham cut its target to $1,100 from $1,650 and Raymond James to $1,230 from $1,750 without cutting ratings.
So the de-rating is about the price list rather than the business as reported, and that is also what makes the valuation conditional. At 20.7x trailing earnings against roughly 62x in January, the shares have lost two-thirds of their multiple; the 14.5x forward figure is computed against a fiscal-2027 consensus of $49.65 a share that embeds the $10 score and has not been revised. Senator Josh Hawley asked the Federal Trade Commission on 23 March to investigate the price increases, a second claim on the same lever.
The fiscal fourth-quarter and full-year report is scheduled for 11 November. It is the first occasion on which Fair Isaac can publish a price list for next year, and the first look at score units since the largest retail mortgage lender in the country said it would prefer somebody else's model.