

Applied Materials Skipped Its Tool-Spending Forecast; Camtek Raised Its Outlook and Fell
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
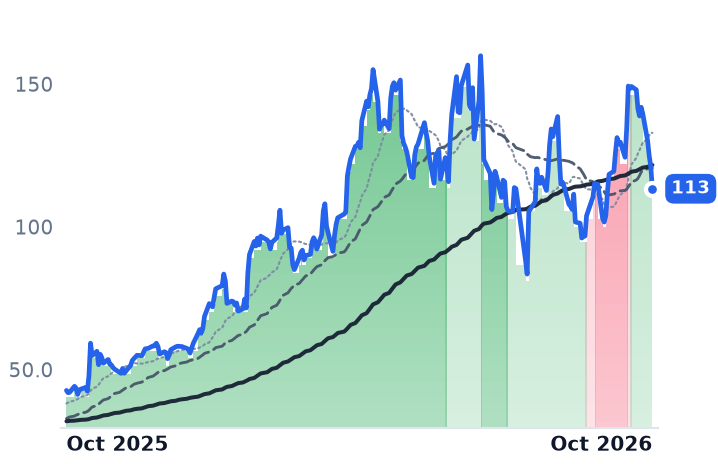
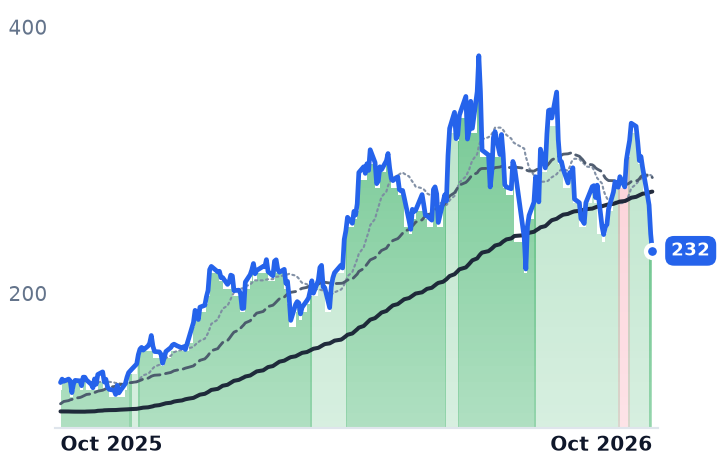
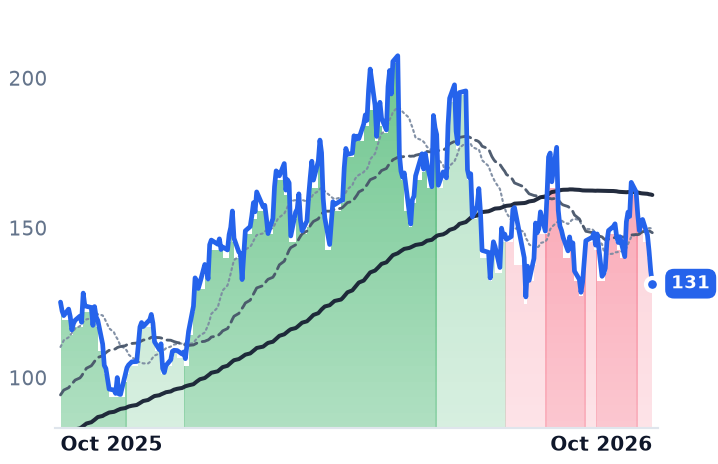
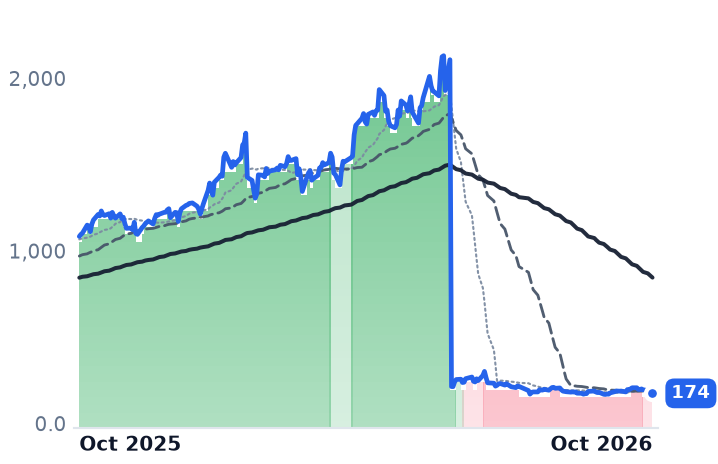
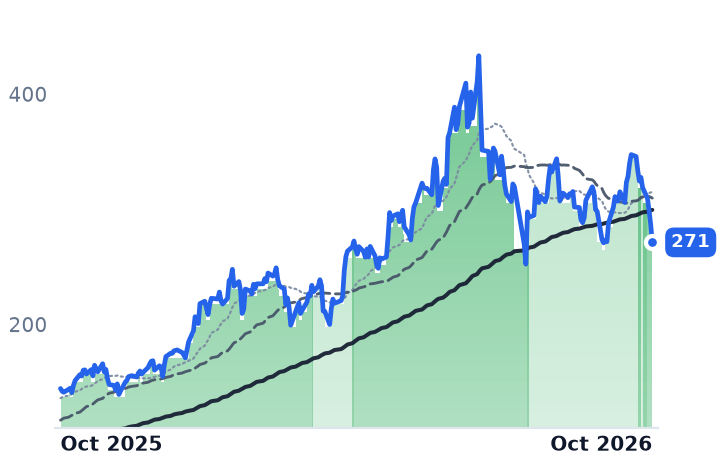
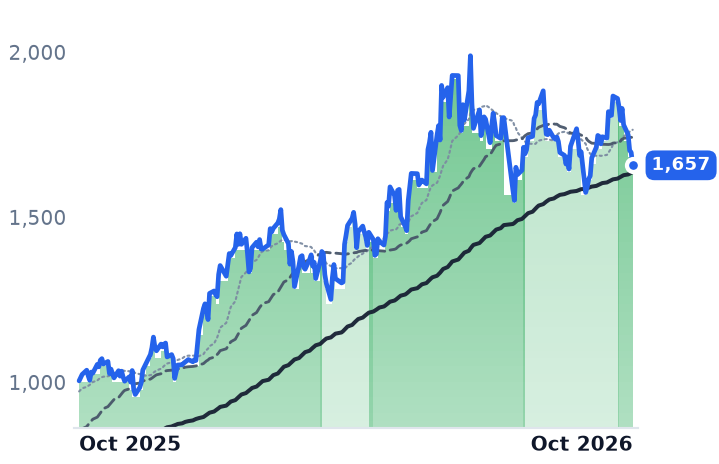
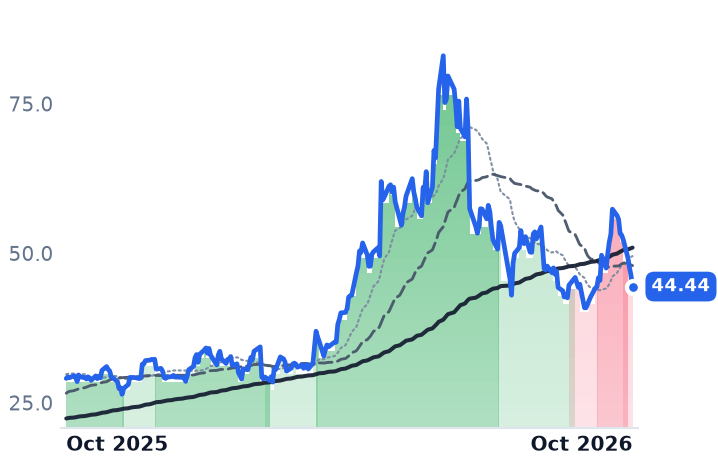
A scare about how much chipmakers will spend on fab tools took between 18% and 25% out of three test and inspection companies in eight sessions, and the only one of the three to speak after it raised its own numbers.
Camtek said on 14 October that third-quarter revenue would land slightly above its guidance at $160-161m and sketched a 2027 of more than $800m against $756m of analyst consensus; its shares fell that same session. Applied Materials had declined the day before to put a figure on 2027 wafer-fab equipment spending.
None of the three bills for tool budgets. FormFactor's revenue counts chip designs entering test, where flash probe cards fell 48% last quarter while memory probe cards rose 49%, and Onto Innovation's backlog crossed $1.1bn for the first time. The reported businesses explain almost none of the markdown.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
FORM | FormFactor | Test & Assembly Services | 🟢 Cont. Bull | +11.5% | +165.4% |
ONTO | Onto Innovation | Fabrication Equipment & Materials | 🟢 Cont. Bull | −5.0% | +74.3% |
CAMT | Camtek | Test & Assembly Services | 🔴 Cont. Bear | −2.4% | +4.9% |
| Compared against · context, not the story | |||||
AMAT | Applied Materials | Fabrication Equipment & Materials | 🟢 Cont. Bull | +2.1% | +89.6% |
KLAC | KLA | Fabrication Equipment & Materials | 🔴 Cont. Bear | +3.8% | −83.9% |
LRCX | Lam Research | Fabrication Equipment & Materials | 🟢 Cont. Bull | +0.1% | +87.9% |
ASML | ASML | Fabrication Equipment & Materials | 🟢 Cont. Bull | +4.1% | +65.0% |
VECO | Veeco Instruments | Fabrication Equipment & Materials | ⚠️ Emerging Bear | +8.7% | +52.9% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FORM | $9.4B | 80.9x | 39.3x | 10.4x | 9.1x | 22.7x | 19.8x | 55.9x | 1.5% |
ONTO | $11.8B | 90.1x | 29.7x | 10.6x | 8.2x | 21.0x | 16.3x | 48.6x | 2.1% |
CAMT | $6.3B | 169.6x | 37.6x | 12.4x | 10.7x | 24.9x | 21.3x | 222.0x | 0.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AMAT | $425.0B | 45.9x | 43.6x | 13.8x | 12.7x | 27.9x | 25.7x | 37.3x | 1.5% |
KLAC | $268.8B | 55.9x | 37.5x | 19.8x | 14.8x | 32.3x | 24.2x | 47.4x | 1.4% |
LRCX | $430.0B | 59.4x | 36.7x | 18.5x | 12.4x | 36.7x | 24.6x | 49.2x | 1.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ASML | $725.8B | 56.9x | 49.4x | 17.1x | 16.8x | 32.4x | 31.8x | 43.4x | 1.7% |
VECO | $3.3B | 142.0x | 34.9x | 4.9x | 4.2x | 12.9x | 11.1x | 62.8x | 2.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
FORM | Revenue | +32.4% | +17.0% | +21.7% |
| EPS | +170.2% | +24.8% | +32.3% | |
ONTO | Revenue | +2.2% | +43.1% | +30.8% |
| EPS | −5.1% | +63.3% | +44.9% | |
CAMT | Revenue | +19.8% | +27.5% | +16.7% |
| EPS | +12.9% | +35.6% | +19.3% | |
AMAT | Revenue | +18.3% | +28.9% | +20.8% |
| EPS | +31.2% | +38.7% | +28.8% | |
KLAC | Revenue | +12.2% | +33.9% | +19.0% |
| EPS | +14.5% | +47.8% | +21.0% | |
LRCX | Revenue | +27.0% | +49.0% | +18.6% |
| EPS | +41.9% | +64.7% | +25.5% | |
ASML | Revenue | +33.7% | +27.3% | +20.6% |
| EPS | +54.0% | +37.1% | +28.6% | |
VECO | Revenue | +18.6% | +35.6% | — |
| EPS | +17.4% | +101.8% | — |
Forward fiscal years only. Blank means no analyst coverage for that year.
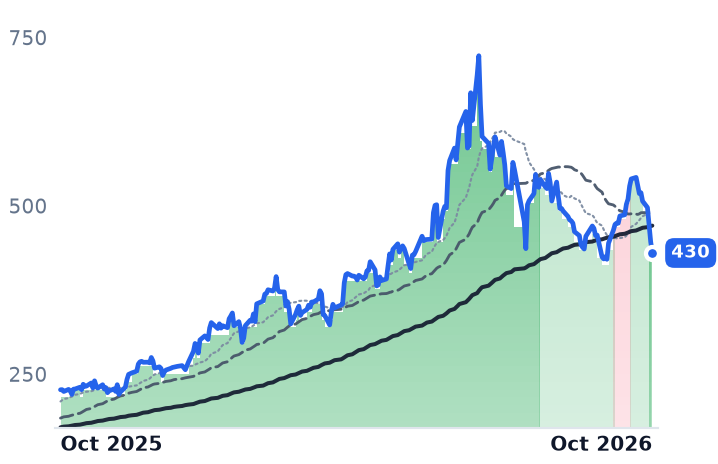
Applied Materials, which sells the tools chipmakers use to process wafers, presented to investors at SEMICON West in San Francisco on 13 October and stopped short of giving a specific forecast for wafer-fabrication-equipment spending, the industry's headline demand number. Its shares closed down 6.7% at $471.66, Lam Research and KLA each fell about 4%, and by the close on 14 October the equipment group had given up between 9% and 19% of its 2 October value, Applied Materials itself down 17.3% and ASML down 9.1%.
The deepest marks in that group landed on three companies whose revenue a tool budget does not describe. FormFactor sells probe cards, the custom contactors that touch a wafer to test chips before they are cut. Onto Innovation sells inspection and metrology steps qualified into a customer's process, plus the software that runs them. Camtek sells automated optical inspection and 3D metrology systems qualified at manufacturers of high-bandwidth memory, the stacked DRAM that sits beside an AI accelerator. The eight sessions were read as a verdict on capital spending.
The one of the three that published numbers after the scare published better ones.
Billed per design, not per tool
FormFactor's probe cards are engineered around a specific chip design, which is why its own filing attributes the quarter to designs: foundry and logic growth came from stronger demand for networking and high-performance compute microprocessor designs. Inside one capital-spending cycle the end markets moved in opposite directions. In the quarter ended 27 June, foundry and logic probe cards were $121.8m, 47% of revenue and up 22% year on year; DRAM probe cards were $85.0m and up 49%; flash probe cards were $2.9m, down 48%.
Group revenue of $258.2m rose 31.9%, the fourth straight quarter of acceleration, and gross margin reached 50.7% against 37.2% a year earlier. "FormFactor's second quarter revenue, gross profit, and earnings per share set all-time records," chief executive Mike Slessor told investors on 29 July.
The guidance carries the mechanism. FormFactor expects third-quarter revenue of $270m give or take $10m at a 54% non-GAAP gross margin, with DRAM revenue comparable to the record second quarter but containing "a significant underlying shift from HBM to DDR, as customers are shifting their wafer start mix to DDR designs to capture profit opportunity from significant DDR price increases". High-bandwidth memory was roughly two-thirds of second-quarter DRAM revenue. A flat line, produced by customers re-mixing wafer starts between designs, with nothing said about tools at all.
What a reader cannot check is the granularity: the filing discloses that three customers were 35.3% of revenue, and nowhere discloses probe-card unit volume or average selling price. For a business whose output is consumed design by design, the two most natural meters do not exist in public data.
The shares are up 216% over twelve months, yet the trailing multiple fell from 199.3x on 3 May to 80.9x while the market capitalization dropped 11%: earnings did that, not price. Forward, it is 39.3x consensus 2026 earnings of $3.05 and about 31.5x 2027, against the roughly 30x forward anchor the business carried in May.
Onto crossed $1bn of backlog, then lost a fifth
Onto Innovation's June quarter revenue of $343.1m grew 35.3% with operating income up 97%, and it raised its second-half growth outlook to 25% or more over the first half from 15%, lifting expected advanced-packaging growth for the year to about 80%. "Visibility continues to be strong with customers maintaining investments in their multi-year growth plans, resulting in a backlog exceeding $1 billion for the first time in company history," chief executive Michael Plisinski said on 6 August. Backlog later exceeded $1.1bn, 30% to 40% of it covering 2027.
The stock is down 19.6% over three months. It trades at 29.7x consensus 2027 earnings of $8.12, against the 101.9x trailing multiple it carried in May.
Camtek answered with a number
On 14 October, the session its shares fell 4.6%, Camtek pre-announced third-quarter revenue of $160-161m, slightly above its own guidance and 27% higher year on year, guided the fourth quarter to about $180m, and gave a first 2027 outlook above $800m. Consensus for 2027 was $756m. More than $800m of orders have come in since the start of the year.
Camtek is also the one with real deterioration behind it: GAAP operating margin fell to 20.4% in the June quarter from 25.9%, operating income declining 14.8% on revenue up 8%. Its order book rests on two memory manufacturers for more than $260m of expected revenue across 2026 and 2027, and it expects China to be roughly 45% of 2026 revenue, down from 49%, under export controls its filings warn could reduce demand across the Chinese sector. At 37.6x 2026 and 27.7x 2027 forward earnings it is priced off numbers the company has just raised; its 169.7x trailing multiple is an artifact of a one-off $53.2m loss booked in the third quarter of 2025.
What the eight sessions actually priced
None of the three has reported into the de-rating. The most recent calls were 29 July, 6 August and 10 August, so every word of management commentary predates the markdown by two months, and the only fresh disclosure, Camtek's, went the other way. On the evidence available, the reported businesses account for almost none of the move; what moved was the price paid for each dollar of forward earnings, from triple-digit trailing multiples in May to high-twenties and thirties on 2027 numbers.
Two real risks sit underneath. FormFactor's third quarter is guided flat in DRAM because customers are moving wafer starts to commodity double-data-rate designs, and a card count is only as good as the designs running against it. And the same investor day that cut the group named optical inspection as an opportunity for Applied Materials, which is the step Onto and Camtek are paid for; KLA, already the larger rival, expects nearly $1bn of advanced-packaging revenue in 2026 against roughly $635m in 2025, more incremental revenue in one year than Camtek's entire base. Applied Materials also said about 75% of incremental equipment growth should come from leading-edge foundry logic, DRAM and advanced packaging, the three sockets these companies serve.
The next word from inside any of these businesses comes on 28 October, when FormFactor reports the quarter it guided to $270m and says whether commodity memory designs replaced high-bandwidth ones card for card. Whatever Applied Materials would not forecast about 2027 will not be in that answer.