

Bel Fuse Grew Operating Profit 47% and Fell With a Chip Selloff Over Chinese Memory
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Bel Fuse makes the magnetics, circuit protection and interconnects that go into data-center racks and defense programs, and its last reported quarter was the strongest of the three listed companies levered to the 800-volt rack transition. Revenue rose 25.2% to $210.7m, gross margin widened to 39.9%, and bookings ran ahead of sales for a sixth consecutive quarter.
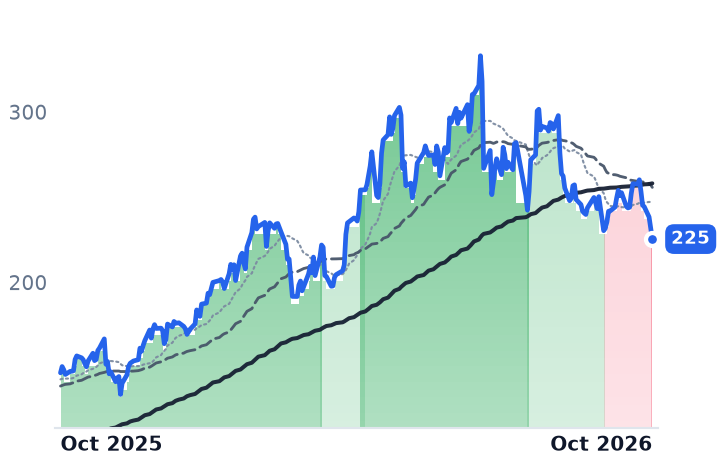
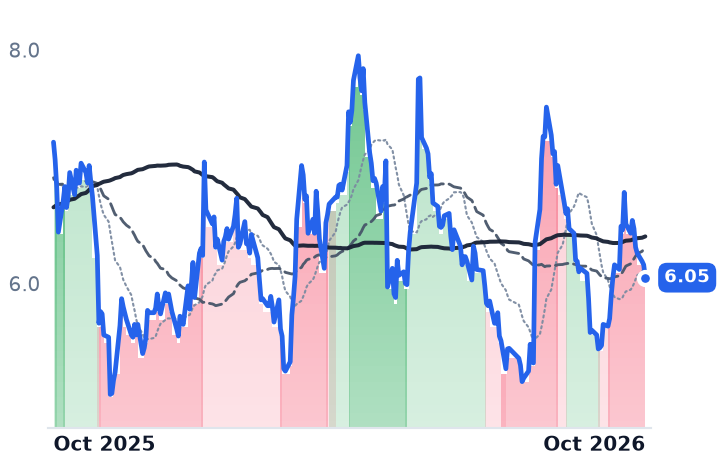
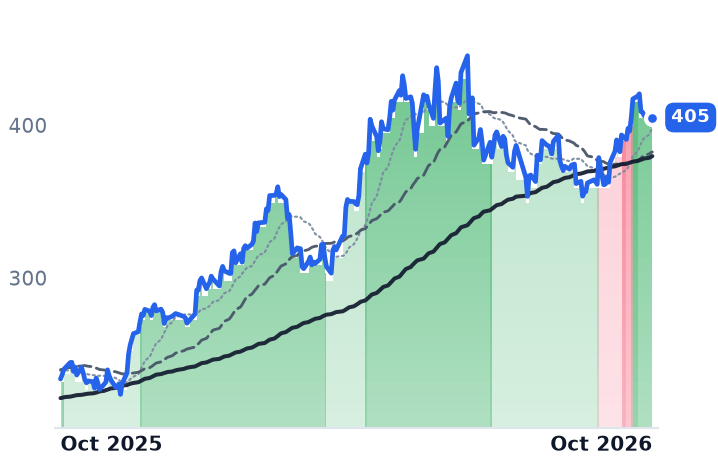
Between 6 and 14 October the shares fell 13.4%. So did Wolfspeed, onsemi, Monolithic Power and Nvidia, in a decline the Philadelphia Semiconductor Index carried through six straight sessions on news out of a Chinese memory maker. Nothing Bel Fuse disclosed changed.
What separates the group is price. Bel Fuse trades at 22.7x forward earnings; Vicor at 62.3x after royalty income drove two guidance raises in nine days; Navitas at 51x forward sales with no gross profit at all.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
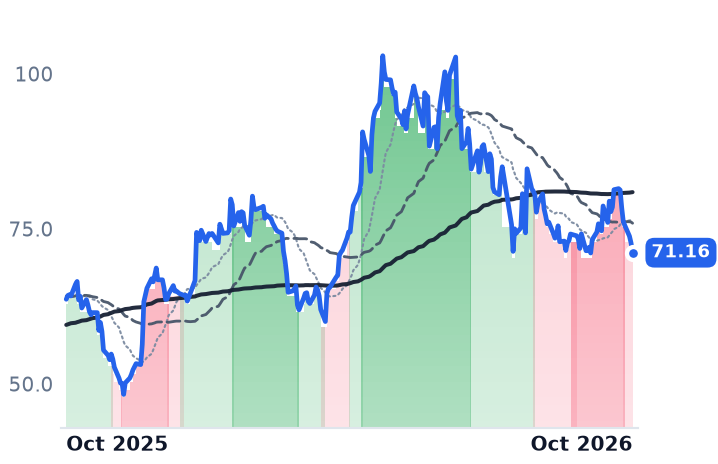
BELFB | Bel Fuse | Connectors & Interconnect Systems | ⚠️ Emerging Bear | −2.1% | +53.4% |
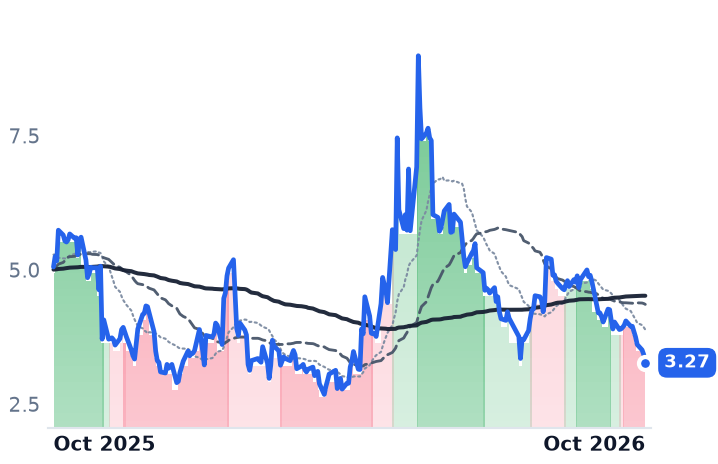
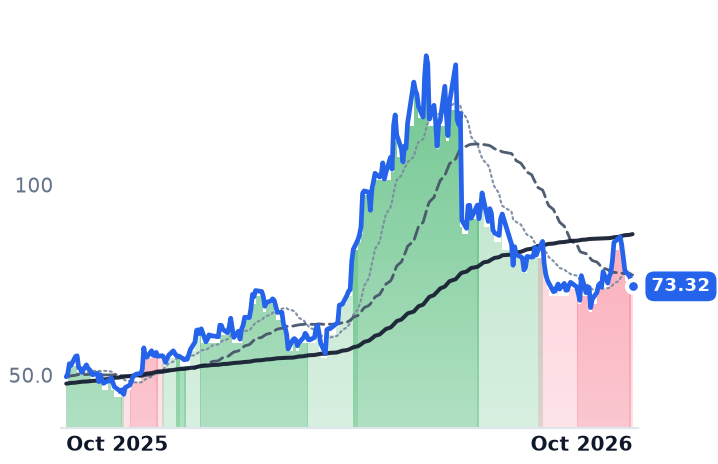
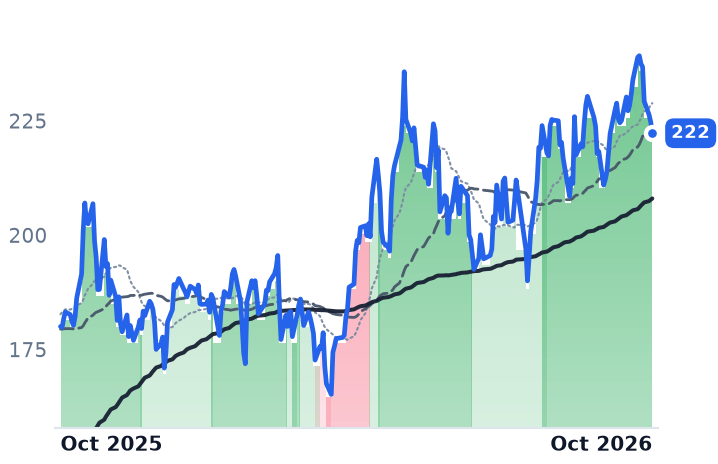
VICR | Vicor | Other | ⚠️ Emerging Bear | +35.4% | +366.1% |
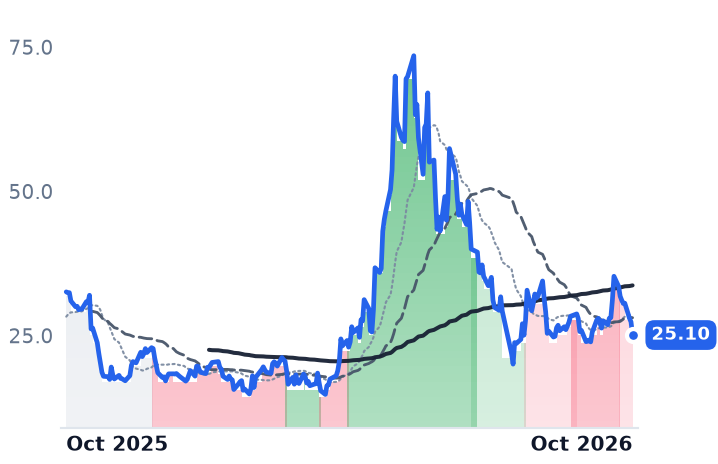
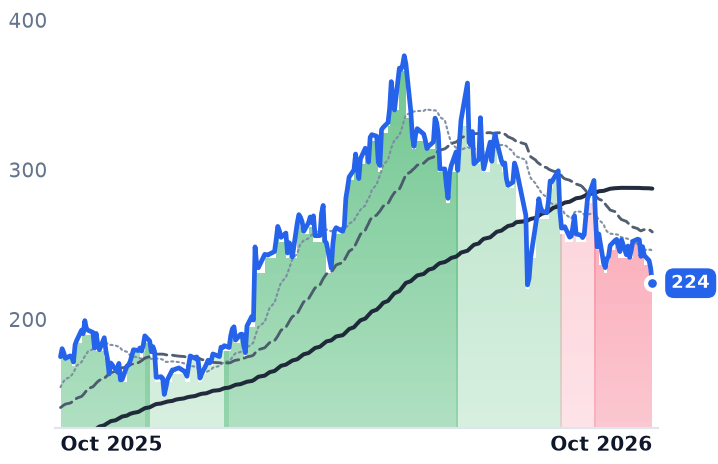
NVTS | Navitas Semiconductor | Other | ⚠️ Emerging Bear | −12.1% | −23.8% |
| Compared against · context, not the story | |||||
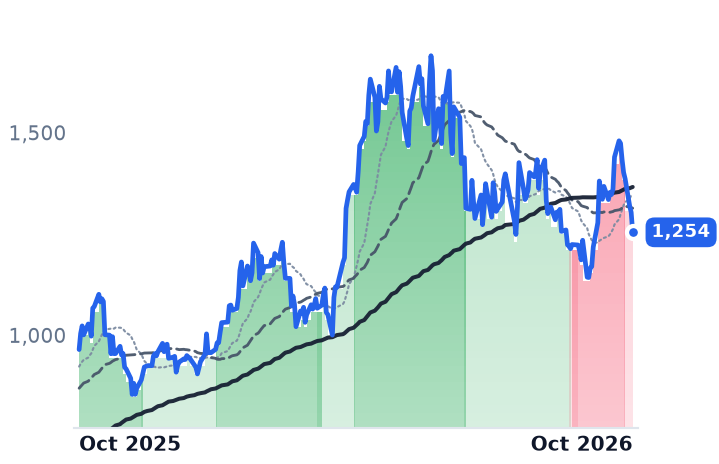
BELFA | Bel Fuse | Hardware, Equipment & Parts | ⚠️ Emerging Bear | −4.6% | +55.3% |
ULBI | Ultralife | Electrical Equipment & Parts | 🔴 Cont. Bear | +8.8% | −16.1% |
IPWR | Ideal Power | Semiconductors | 🔴 Cont. Bear | −24.8% | −35.3% |
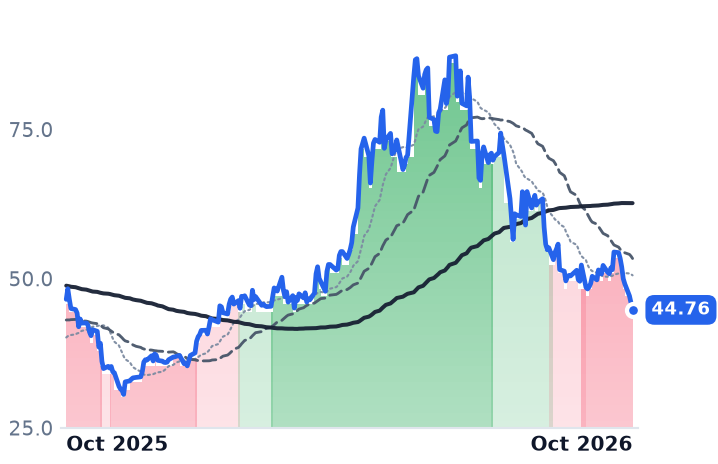
MPWR | Monolithic Power Systems | Analog & Mixed-Signal | ⚠️ Emerging Bear | +9.7% | +30.0% |
POWI | Power Integrations | Analog & Mixed-Signal | ⚠️ Emerging Bear | −7.7% | −3.8% |
WOLF | Wolfspeed | Discrete & Power | ⚠️ Emerging Bear | +4.8% | −23.0% |
ON | ON Semiconductor | Analog & Mixed-Signal | ⚠️ Emerging Bear | +2.3% | +48.0% |
MCHP | Microchip Technology Incorporated | Analog & Mixed-Signal | ⚠️ Emerging Bear | −0.4% | +11.8% |
TXN | Texas Instruments Incorporated | Analog & Mixed-Signal | 🟢 Cont. Bull | +6.8% | +65.1% |
ADI | Analog Devices | Analog & Mixed-Signal | 🟢 Cont. Bull | +12.2% | +73.2% |
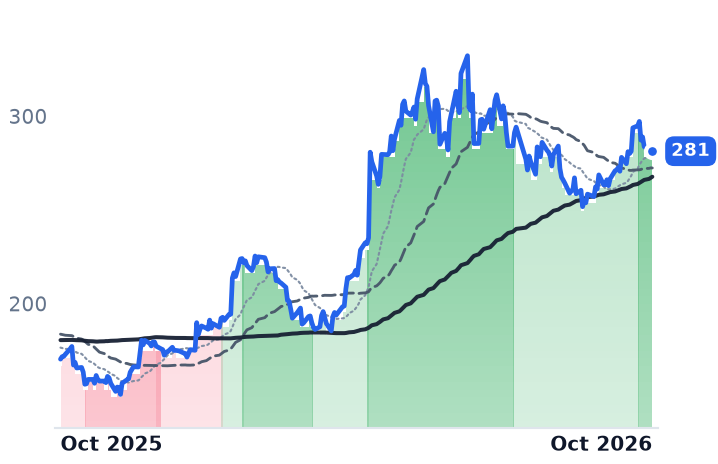
NVDA | NVIDIA | AI & Data Center GPUs | 🟢 Cont. Bull | +5.4% | +23.5% |
VRT | Vertiv | Data Center Power & Thermal | ⚠️ Emerging Bear | −5.6% | +28.1% |
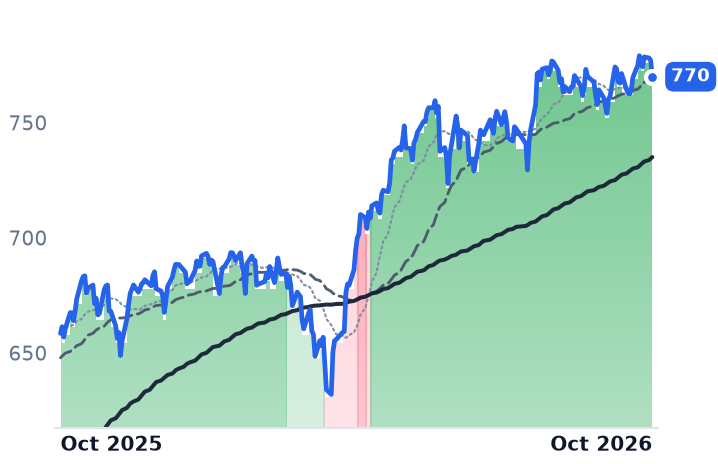
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | +1.2% | +16.9% |
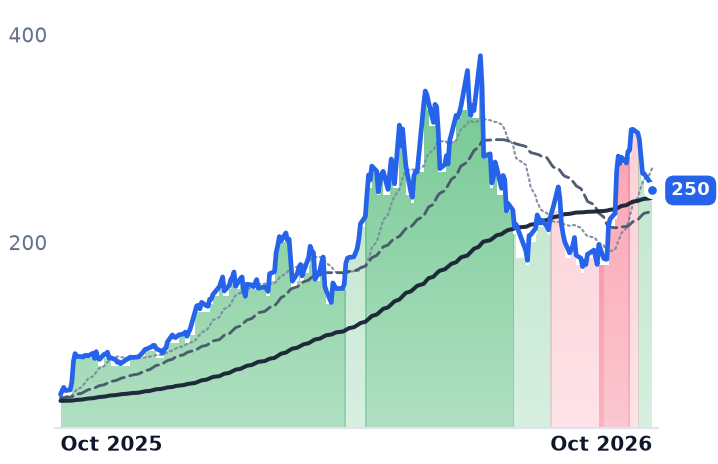
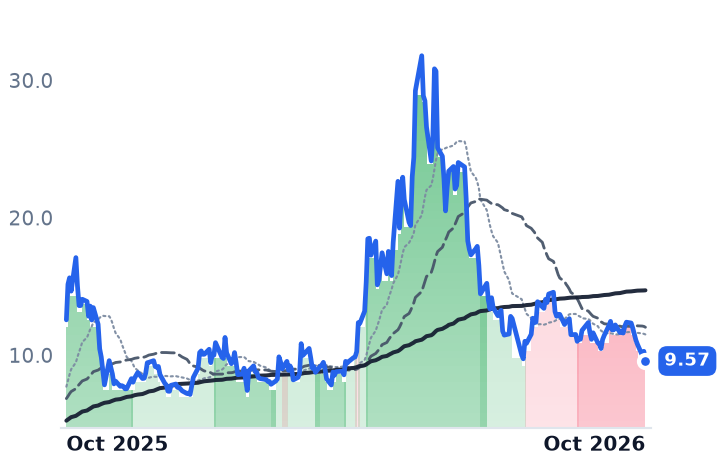
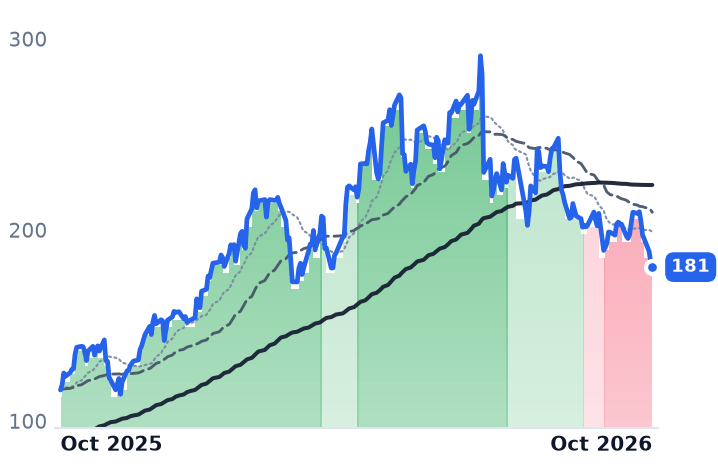
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BELFB | $2.7B | 55.9x | 22.7x | 3.6x | 3.3x | 9.2x | 8.4x | 18.7x | 2.7% |
VICR | $11.1B | 76.9x | 62.3x | 23.5x | 17.5x | 41.4x | 31.0x | 80.3x | 0.5% |
NVTS | $2.4B | n/m | — | 66.9x | 51.2x | — | — | n/m | -2.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BELFA | $3.4B | 69.0x | 24.6x | 4.5x | 4.2x | 11.4x | 10.7x | 23.6x | 2.2% |
ULBI | $90.8M | n/m | 6.3x | 0.5x | 0.4x | 2.0x | 1.7x | n/m | 2.2% |
IPWR | $63.9M | n/m | — | — | 79.8x | — | — | n/m | -14.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MPWR | $68.1B | 84.5x | 50.5x | 20.8x | 16.4x | 37.7x | 29.7x | 64.3x | 0.9% |
POWI | $3.5B | 136.5x | 44.7x | 7.7x | 7.2x | 14.4x | 13.5x | 84.1x | 2.3% |
WOLF | $1.8B | n/m | — | 2.8x | 2.9x | — | — | n/m | -19.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ON | $33.0B | 53.7x | 26.5x | 5.3x | 5.0x | 14.2x | 13.5x | 26.9x | 5.4% |
MCHP | $41.0B | 104.7x | 20.8x | 8.0x | 6.4x | 13.3x | 10.7x | 27.4x | 2.7% |
TXN | $259.1B | 42.9x | 33.3x | 13.3x | 11.8x | 22.8x | 20.3x | 27.9x | 2.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ADI | $197.8B | 48.0x | 31.6x | 14.3x | 13.1x | 21.7x | 19.9x | 29.2x | 2.5% |
NVDA | $5.5T | 34.3x | 25.0x | 21.5x | 13.9x | 29.0x | 18.7x | 28.3x | 2.2% |
VRT | $97.1B | 55.8x | 37.5x | 8.5x | 6.9x | 22.2x | 18.2x | 38.2x | 3.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
BELFB | Revenue | +20.7% | +8.5% | +13.8% |
| EPS | +45.9% | +13.7% | +22.9% | |
VICR | Revenue | +40.0% | +52.9% | +22.8% |
| EPS | +82.0% | +61.4% | +31.5% | |
NVTS | Revenue | +4.7% | +52.5% | +59.8% |
| EPS | −21.9% | −17.9% | −44.8% | |
BELFA | Revenue | +20.3% | +7.6% | +12.6% |
| EPS | +39.7% | +13.2% | +34.5% | |
ULBI | Revenue | +6.2% | — | — |
| EPS | +22.9% | — | — | |
IPWR | Revenue | +1500.0% | +0.0% | +975.0% |
| EPS | −31.5% | −18.8% | −20.3% | |
MPWR | Revenue | +49.3% | +28.9% | +20.5% |
| EPS | +55.0% | +31.2% | +20.6% | |
POWI | Revenue | +7.7% | +14.2% | +20.8% |
| EPS | +14.8% | +34.8% | +43.0% | |
WOLF | Revenue | +0.7% | −15.2% | +23.7% |
| EPS | +275.2% | −39.2% | −22.4% | |
ON | Revenue | +9.2% | +13.1% | +13.9% |
| EPS | +37.1% | +40.9% | +30.2% | |
MCHP | Revenue | +6.2% | +37.1% | +16.4% |
| EPS | +20.7% | +132.2% | +25.6% | |
TXN | Revenue | +24.0% | +13.8% | +10.6% |
| EPS | +55.6% | +20.7% | +17.1% | |
ADI | Revenue | +37.8% | +22.1% | +11.6% |
| EPS | +65.8% | +29.4% | +18.0% | |
NVDA | Revenue | +65.1% | +84.2% | +43.2% |
| EPS | +59.0% | +91.7% | +42.0% | |
VRT | Revenue | +37.1% | +30.2% | +21.3% |
| EPS | +62.9% | +36.7% | +26.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Bel Fuse, which sells power magnetics, circuit protection and interconnect hardware into data infrastructure, defense programs and industrial customers, reported in its June quarter the sixth consecutive period in which it took more orders than it shipped. In October its shares fell with every company that has a semiconductor anywhere in its supply chain, and none of the reasons given had anything to do with Bel Fuse.
The 800-volt direct-current rack architecture that hyperscale operators are moving toward is usually traded through the specialists: the gallium-nitride and silicon-carbide chip designers, and the module makers who convert high voltage down to the processor. The assumption is that the diversified component houses are too broad to participate. Bel Fuse's disclosure says the content is already arriving, and it is the one member of this group whose accelerating business is attached to a forward earnings multiple of 22.7x.
$66.5m of defense and $58m of data solutions
June-quarter revenue reached $210.7m, up 25.2% year on year, with gross margin widening to 39.9% from 38.7% and operating income up 47.4% to $38.4m — profit growing at nearly twice the rate of sales. On the quarter's call, the two reorganized segments both grew: Aerospace, Defense and Rugged Solutions rose 20.6% to $110.5m on defense sales of $66.5m, and Industrial Technology and Data Solutions rose 31.1% to $100.2m, within which data solutions reached roughly $58m against $38m a year earlier.
That is not a one-quarter artifact. Full-year 2025 revenue grew 26.3% to $675.5m with operating income up 67.5%, and the company guided third-quarter sales to $205m-$225m at a 39%-41% gross margin. The run of bookings above sales now covers a year and a half.
Six sessions that hit everything with a chip in it
From 6 to 14 October the shares fell 13.4%, from $260.26 to $225.46. Over the identical span Wolfspeed fell 21.1%, Power Integrations 16.2%, onsemi 15.1%, Monolithic Power 14.9%, Microchip 12.4% and Nvidia 7.1%, against the S&P 500 tracker's 1.2%. The Philadelphia Semiconductor Index fell 3.1% on 14 October alone, a sixth straight down session leaving it off roughly 10%, with the decline attributed to China's ChangXin Memory announcing progress on a higher-density chip design, alongside higher rates and the cost of building AI infrastructure.
Bel Fuse's own uptrend had already ended earlier, in mid-September, and the trend turned decisively downward on 13 October. No lost socket, guidance cut, financing or adverse ruling landed in between.
The cheapest claim on the same rack
Vicor, which builds brick-format power conversion modules at its own fab in Andover, Massachusetts, has risen 366% over twelve months and trades at 62.3x forward earnings and 31.0x forward gross profit. Its incremental dollar increasingly arrives by contract rather than by shipment: royalty revenue hit $30.4m in the June quarter against $10.4m a year earlier, and founder and chief executive Patrizio Vinciarelli described licensing on the first-quarter call as "nearly 100% margin in terms of profitability." Navitas, which sells gallium-nitride and silicon-carbide power chips, is the other extreme — June-quarter revenue of $10.5m, down 27.3%, a gross margin of minus 9.5%, diluted shares up 18.6% year on year, and 51.2x forward sales.
Bel Fuse's 55.9x trailing earnings compresses to 22.7x forward on consensus 2026 earnings of $9.86 a share against $4.64 actually earned in 2025, and 8.4x forward gross profit is roughly a quarter of what Vicor commands. The cash meters agree: 18.7x enterprise value to EBITDA and a 2.71% free-cash-flow yield, against Vicor's 80.3x and 0.46%.
None of the October decline is explained by anything the three companies reported. It is sector contagion, and it fell hardest on the names with the least earnings underneath them — which is why the most expensive member of this group gave back the least and the loss-making one gave back the most. What the selloff did do is widen an already wide gap between a business compounding operating profit at 47% and the price assigned to it. The available disclosure does not separate how much of Bel Fuse's growth is organic from how much arrived with acquisitions, and that question stays open.
Vicor's audit of its twice-raised royalty guidance comes on 20 October and Navitas reports on 3 November. Bel Fuse, the only one of the three whose orders have outrun its shipments for six quarters running, has the least to prove and the smallest multiple to defend.