

A Higher Assumed Gold Price Gave Seabridge 6.8m More Ounces and No Gain Per Share
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Seabridge Gold has never recorded a dollar of revenue, yet its largest reported line last quarter was a $151.7m non-cash gain on a spin-out, producing $1.08 of diluted earnings per share on nothing sold. The income statement cannot say whether the business improved, so three things off it decide the value: a resource re-estimate, a permit reconsideration, and the share count.
The Kerr-Sulphurets-Mitchell resource was re-struck at $2,000 an ounce from $1,300, which added 6.8m measured-and-indicated ounces without a drill turning. Diluted shares rose 7.1% over the same year, so ounces per share moved 0.5%.
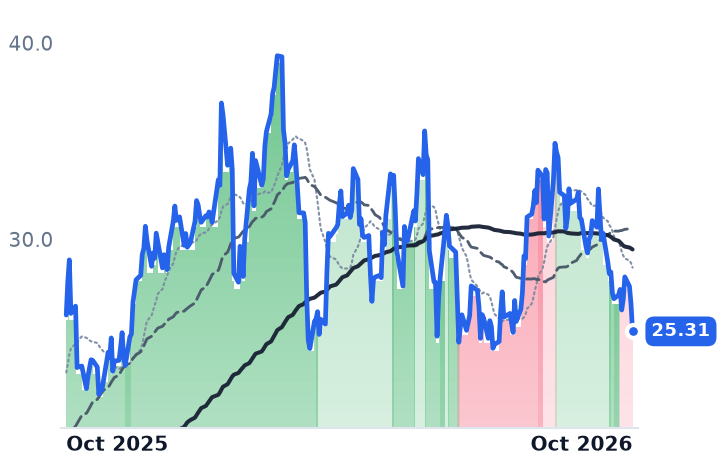
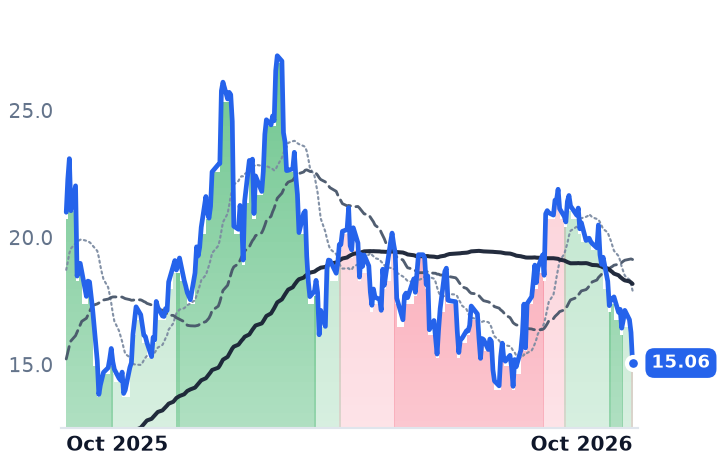
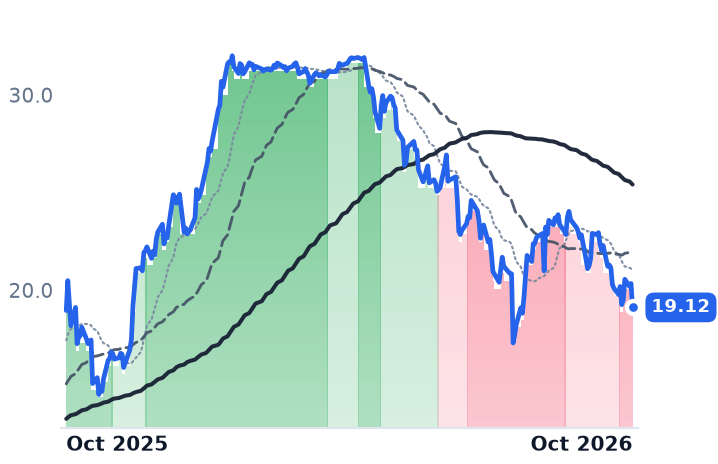
Across the shelf the thirty-day falls split by cause: Coeur Mining fell hardest at 24.3% after a record quarter on 9.5x trailing enterprise value to EBITDA, and Allied Gold's slide dates to a terminated takeover.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
SA | Seabridge Gold | Junior & Development | ⚠️ Emerging Bear | −14.5% | −3.2% |
CDE | Coeur Mining | Junior & Development | ⚠️ Emerging Bear | −24.3% | −28.3% |
AAUC | Allied Gold | Junior & Development | 🔴 Cont. Bear | −11.4% | +0.8% |
| Compared against · context, not the story | |||||
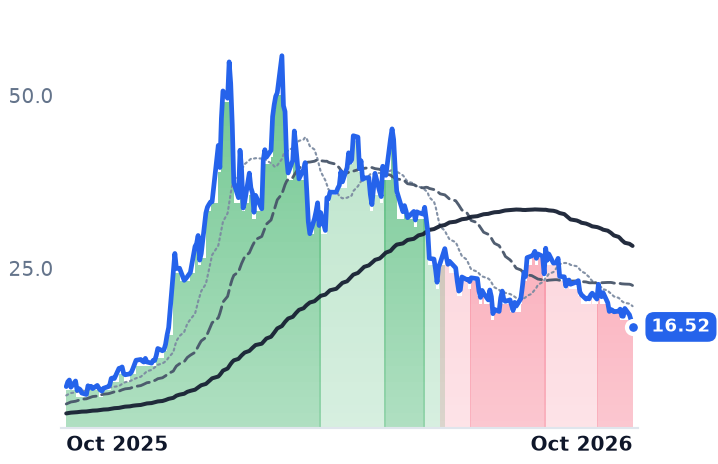
HYMC | Hycroft Mining | Junior & Development | 🔴 Cont. Bear | −19.6% | +109.4% |
GLD | SPDR Gold Shares | Asset Management | 🔴 Cont. Bear | −4.8% | −1.8% |
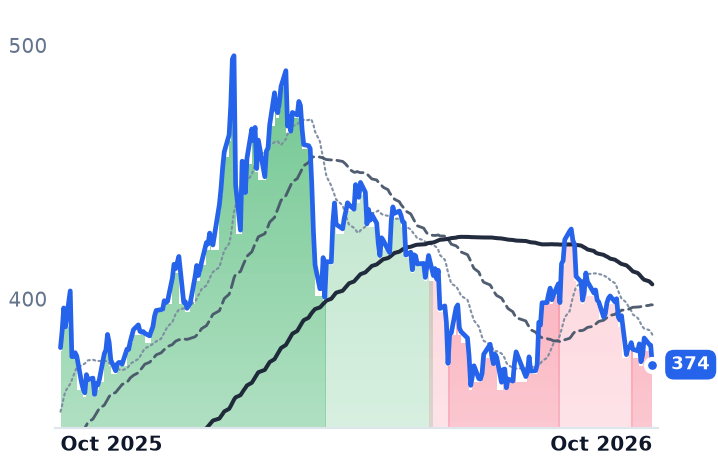
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SA | $2.7B | 125.3x | 72.5x | n/m | — | — | — | n/m | -4.5% |
CDE | $15.5B | 11.9x | 14.0x | 4.9x | 3.2x | 9.7x | 6.4x | 9.5x | 7.5% |
AAUC | $2.4B | n/m | 7.1x | 1.7x | 1.3x | 3.8x | 3.0x | 5.2x | -4.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
HYMC | $1.5B | n/m | — | n/m | 253.8x | — | — | n/m | -7.2% |
GLD | $155.3B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
SA | Revenue | — | — | — |
| EPS | −183.0% | −192.9% | +173.8% | |
CDE | Revenue | +133.8% | +24.2% | −11.7% |
| EPS | +15.0% | +48.9% | +0.9% | |
AAUC | Revenue | +43.4% | +58.0% | +16.6% |
| EPS | +98.0% | +166.1% | +13.2% | |
HYMC | Revenue | +36.5% | +16.7% | +378.6% |
| EPS | +17.5% | −37.9% | −31.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Seabridge Gold reported $1.08 of diluted earnings per share for the June quarter and sold nothing at all. The figure came from a $151.7m non-cash gain on the spin-out of its Courageous Lake project; the loss from operations, the only line its 12 employees actually run, was $9.3m. The Toronto company has recorded zero revenue in each of the last eight quarters and each of the last five financial years.
So the thirty-day fall across the four gold names on this shelf — Seabridge down 14.5%, Coeur Mining 24.3%, Allied Gold 11.4%, Hycroft Mining 19.6%, against 4.8% for the bullion fund — cannot be read the same way for each. A producer is marked against metal it actually sold. Seabridge's entire reported value is an engineering estimate of rock, struck at a gold price nobody is paying, and the three inputs that move it never touch an income statement: the re-estimate, the permit, and the share count.
The 6.8m ounces that arrived with the price deck
Effective 30 March 2026, Seabridge's Kerr-Sulphurets-Mitchell project in British Columbia held measured-and-indicated resources of 95.5m ounces of gold, 21.1bn pounds of copper and 459.9m ounces of silver. The estimate assumes $2,000 an ounce for gold, against $1,300 in the prior disclosure. A higher assumed price lowers the cut-off grade at which rock qualifies as resource, and that change alone added 6.8m measured-and-indicated ounces and 12.9m inferred ounces against the January 2024 count.
No drill turned.
The deck is conservative against the market — gold was $4,083 an ounce on 14 October, 51% above it — and the company's stated reason for the change is alignment with the prices major miners use as it pursues a partner. That is the business: with no cash flow, the route from 95.5m ounces to money runs through a joint venture.
Ounces per share stood still
Diluted shares went from 101.1m in the June 2025 quarter to 108.4m a year later, up 7.1%, and are up 21% from 89.6m two years ago. On the derived meter that matters to a holder, 95.5m ounces over 108.4m shares is 0.881 ounces each, against 0.877 a year earlier: a gain of 0.5% while the headline ounce count rose 7.7%. Measured from the 83.0m shares Seabridge carried in 2023, ounces per share fell 17.5%.
The funding arithmetic is why the count keeps rising. Net working capital halved from $109.8m at 31 December to $53.6m at 30 June while $32.5m went into mineral interests in the June quarter alone, and in July the company arranged a US$100m unsecured facility bearing 7% compounded monthly, maturing 31 December 2026 and repayable in cash or shares, undrawn as of the filing. On applicable anchors the stock trades at 3.51 times book with a trailing free-cash-flow yield of -4.50%; market value per measured-and-indicated ounce fell to about $28.5 from $35.6 in mid-April, against a 16% fall in the bullion fund over the same window, so most of that compression is the metal.
A designation still under reconsideration
KSM's "substantially started" status, which keeps its environmental certificate alive and its capital plan spendable, was granted on 24 July 2024. On 8 June 2026 the British Columbia Supreme Court found the determination reasonable but held consultation with the Tsetsaut Skii km Lax Ha insufficient, ordering submissions and a reconsideration. The 90-day period closed on 28 September; the Environmental Assessment Office opened its reconsideration on 22 September and must still draft a report for review before any recommendation reaches a decision-maker.
The office "recognizes the importance of a timely decision for Seabridge Gold and will strive to complete the process as efficiently as possible, while fulfilling its duty to consult," chair and chief executive Rudi Fronk said on 22 September. The feasibility study is targeted for the second half of 2027.
What Coeur's quarter says that Seabridge's cannot
Coeur Mining, which mines gold and silver at Palmarejo in Chihuahua and Rochester in Nevada, fell hardest of the four and had the best quarter: a record 163,490 ounces of gold, $388m of free cash flow and $1.1bn of cash. It trades at 9.5 times trailing enterprise value to EBITDA with a 7.5% trailing free-cash-flow yield, and its forward price-to-earnings of 14.0x sits above the trailing 11.9x — consensus marking per-share earnings down on a lower metal price while revenue estimates stand. Chief executive Mitchell Krebs described the $750m repurchase on the 12 August call as "a well designed buyback program with a portion of it just automatically chewing away during blackouts."
Allied Gold, a 485,000-575,000-ounce producer in Mali, Côte d'Ivoire and Ethiopia, is the cheapest here at 7.1 times forward earnings with gross margin up 19.9 points year on year; its 39.7% six-month fall dates to 29 July, when Zijin Gold's C$44-a-share cash offer was terminated and replaced by a 9.2% stake taken at C$32.55. Hycroft Mining, 51 employees and no revenue, grew diluted shares 231.7% in a year against an unfunded $2.4bn restart cost, at 5.96 times book.
Four falls, four causes.
Bullion's 4.8% slide and a 10-year Treasury yield above 5% supply a quarter to a half of the group's move and all of the discount-rate pressure on a first cash flow a decade out. Beyond that, Coeur's shares fell because the market repriced the metal its 690,000-ounce guidance will be sold into, not because the mines faltered; Allied's fell on a dead deal; Hycroft's on the share count. Seabridge's asset did not shrink and did not grow per share, which is the honest answer its income statement can never give.
The facility that funds this year's road building and geotechnical work comes due on the last day of December, and it may be repaid in stock. For a company whose only meter is ounces per share, the price of the shares is an input to the thing being measured.