

Nvidia Said Its Racks Need No Chillers and SPX Technologies' Cooling Backlog Grew 59%
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
A design claim made in January was read as deleting a layer of equipment from the AI data center, and the companies paid to carry that heat have said the opposite in every disclosure since.
SPX Technologies, which builds Marley evaporative cooling towers, lifted its expectation for 2026 data-center revenue from $300m to $430m on 30 July and closed its FIS Water acquisition on 15 September, the day its shares touched a 52-week low. Revenue grew 22.9% in the June quarter and the trailing price-to-earnings multiple has compressed to 29.8x from 41.9x in May.
Dover, which sells the quick-disconnect couplings inside the rack, books that demand in a segment that grew 0.4% organically, so its revenue line cannot show it. Parker-Hannifin, the number two in those couplings, did not de-rate at all.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
SPXC | SPX Technologies | HVAC & Refrigeration | ⚠️ Emerging Bear | −8.7% | −9.7% |
DOV | Dover | Specialty Components & Systems | ⚠️ Emerging Bear | +1.8% | +19.1% |
PH | Parker-Hannifin | Motion & Power Transmission | 🟢 Cont. Bull | +2.8% | +30.5% |
| Compared against · context, not the story | |||||
VRT | Vertiv | Data Center Power & Thermal | ⚠️ Emerging Bear | −5.6% | +28.1% |
MOD | Modine Manufacturing | Thermal & Powertrain Components | ⚠️ Emerging Bear | −11.5% | +5.0% |
TT | Trane Technologies | HVAC Systems | ⚠️ Emerging Bear | +10.1% | +10.9% |
JCI | Johnson Controls International | HVAC & Refrigeration | 🟢 Cont. Bull | +10.6% | +41.7% |
ETN | Eaton | Power & Propulsion Systems | 🟢 Cont. Bull | +4.6% | +10.5% |
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | +1.2% | +16.9% |
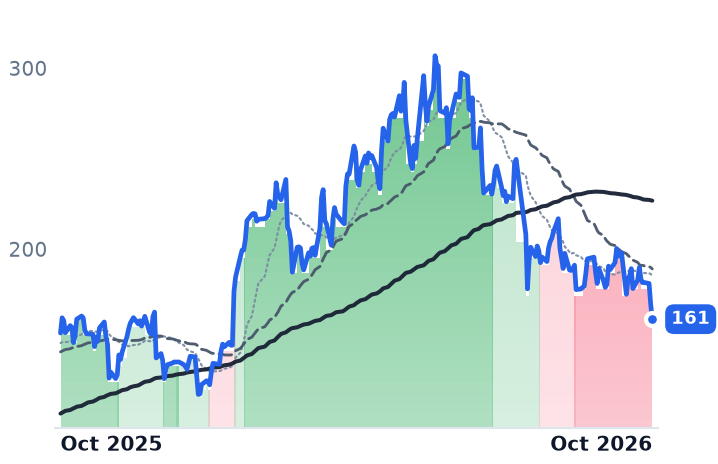
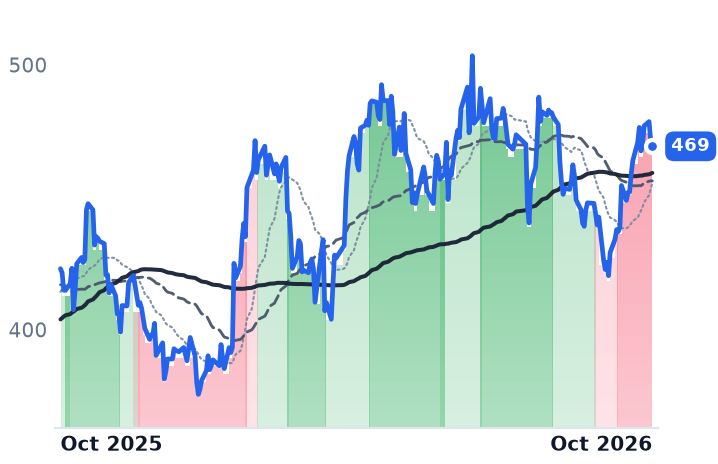
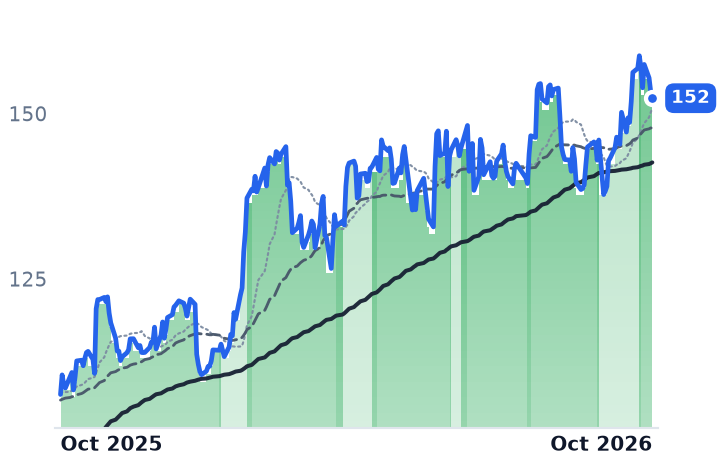
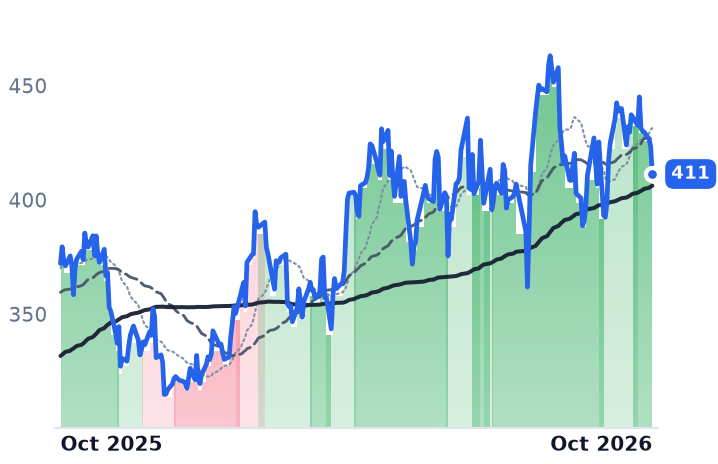
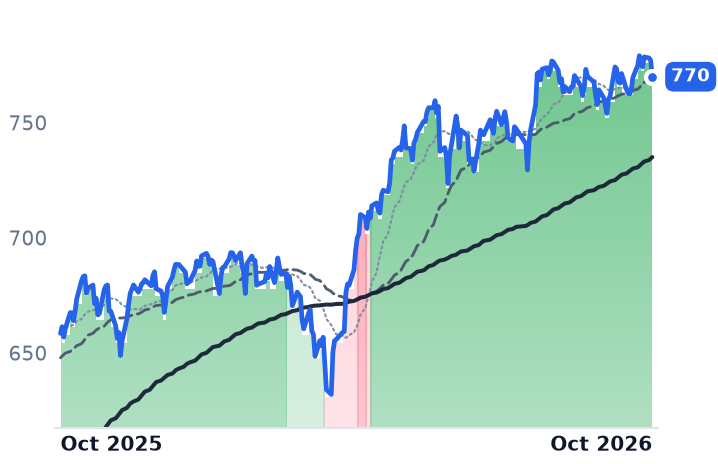
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPXC | $8.4B | 29.8x | 20.1x | 3.4x | 3.0x | 8.4x | 7.6x | 16.5x | 3.6% |
DOV | $25.9B | 23.1x | 18.0x | 3.1x | 3.0x | 7.8x | 7.5x | 14.5x | 4.5% |
PH | $120.4B | 33.0x | 26.9x | 5.6x | 4.8x | 14.9x | 12.8x | 21.8x | 3.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
VRT | $97.1B | 55.8x | 37.5x | 8.5x | 6.9x | 22.2x | 18.2x | 38.2x | 3.0% |
MOD | $9.6B | 68.0x | 24.1x | 2.9x | 2.4x | 12.9x | 10.7x | 33.7x | 1.0% |
TT | $104.9B | 35.9x | 31.2x | 4.7x | 4.4x | 13.4x | 12.5x | 24.9x | 3.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
JCI | $95.6B | 27.4x | 25.8x | 3.8x | 3.5x | 10.4x | 9.4x | 27.7x | 2.1% |
ETN | $168.6B | 44.0x | 32.0x | 5.6x | 5.1x | 15.6x | 14.2x | 29.3x | 2.7% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
SPXC | Revenue | +22.6% | +13.7% | +8.1% |
| EPS | +23.8% | +16.5% | +11.5% | |
DOV | Revenue | +7.5% | +5.1% | +4.1% |
| EPS | +11.4% | +9.8% | +8.1% | |
PH | Revenue | +8.1% | +17.1% | +7.1% |
| EPS | +17.0% | +13.3% | +11.1% | |
VRT | Revenue | +37.1% | +30.2% | +21.3% |
| EPS | +62.9% | +36.7% | +26.4% | |
MOD | Revenue | +22.6% | +29.0% | +14.9% |
| EPS | +33.4% | +50.1% | +38.0% | |
TT | Revenue | +11.7% | +9.7% | +8.8% |
| EPS | +17.4% | +15.5% | +15.4% | |
JCI | Revenue | +9.0% | +8.2% | +7.8% |
| EPS | +36.7% | +20.5% | +17.6% | |
ETN | Revenue | +20.0% | +11.2% | +9.7% |
| EPS | +12.6% | +19.3% | +17.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
A January claim the market read as a deletion
The equipment that dumps an AI data center's heat into the outside air looked, for one session in January, like a line item about to be erased. Nvidia chief executive Jensen Huang said at CES on 6 January that the company's Vera Rubin systems use warm-water direct liquid cooling at a 45°C supply temperature with "no chillers necessary", and shares in cooling-equipment makers fell the same day. Nvidia's argument was about power: chilled-water plant can account for nearly 40% of a data center's electricity use, and 45°C water is warm enough to reject outdoors.
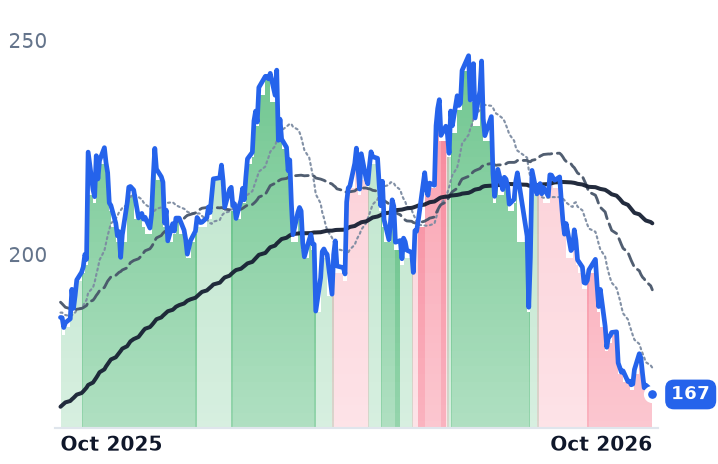
That belief has been priced repeatedly, and it is testable against what the equipment makers have disclosed. SPX Technologies engineers, builds and services evaporative cooling towers and fluid coolers under the Marley and Recold names, sold through independent manufacturing representatives. In the three months to 13 October its shares fell 22.2% to a 52-week low of $167.28, 32.1% below the year's high, while Johnson Controls, which sells building HVAC and controls, rose 6.5% and the S&P 500 tracker gained 3.7%. The selling was aimed at cooling content, not at industrials.
What the company said while the shares fell
On 30 July SPX raised full-year guidance, to revenue of $2.705-2.765bn and an adjusted earnings midpoint $0.45 higher at $8.40. It also lifted its 2026 data-center revenue expectation from $300m to $430m, and raised estimated annual data-center capacity at full production from about $750m to about $1.1bn. Chief executive Gene Lowe walked the ramp back through its own history on that call: roughly $150m of volume two years ago, $200m last year, a $300m plan entering 2026. "The market is shifting towards our solutions," he said, citing plant throughput running ahead of plan.
The June quarter grew revenue 22.9% to $679m with operating margin up 149 basis points to 17.2%. Gross margin fell 120 basis points to 40.2%, so the margin gain came from operating leverage on fixed costs rather than from price. HVAC backlog ended the quarter at $919m, up 59% organically, on a segment book-to-bill near 1.4 times.
The objection the market actually voiced was balance-sheet, not demand: the shares fell 6.6% after the guidance raise on leverage from the acquisition program, which added Neptronic in July and then FIS Water for $410m in cash on 15 September, a water-control supplier expected to contribute about $105m of 2026 revenue. October added a second channel: a financing scare on the buildout's borrowers that widened credit spreads at the companies renting out the racks. That reaches SPX only through its customers' ability to fund projects.
The de-rating is real and large. SPX trades at 29.8x trailing earnings against 41.9x in May, and 20.1x forward — but consensus 2026 revenue sits at the top of management's own guided range, so the forward figure rests on the company hitting its own upper end.
Dover sells the coupling and cannot show you the revenue
One layer in, the same heat passes through quick-disconnect couplings, and Dover's Colder Products Company is the industry reference for the blind-mate, non-spill, hot-swappable version used at hyperscale volumes; each liquid-cooled rack takes dozens of them plus consumables. That business sits inside the roughly $1.6bn Pump Solutions Group, within one of five segments at a $25.9bn conglomerate. In the June quarter Pumps & Process Solutions grew about 0.4% organically on $553m of revenue, with bookings up 11% and margin up 170 basis points on biopharma mix.
"In data centers, the density of thermal requirements of new chips are driving a shift towards liquid cooling, which directly benefits our connectors," chief executive Rich Tobin told investors on 23 July. The only number attached to any of it is a group aggregate: management expects over $1bn of 2026 revenue from applications tied to artificial intelligence and power generation, which is about 12% of the consensus revenue base by our arithmetic, and lumps cooling in with turbines' end markets.
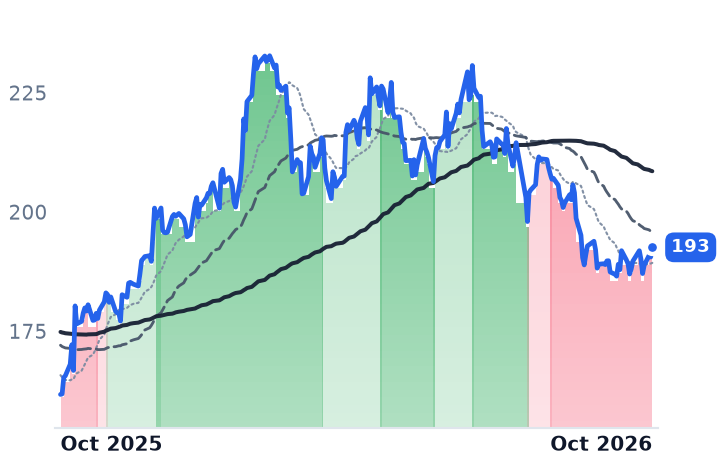
Dover's own cooling exposure elsewhere makes the point harder. Climate & Sustainability Technologies grew 8% organically to $455m and led group bookings with 46% growth, and heat exchangers had their best quarter ever on liquid-cooling demand. The segment still lost 200 basis points of margin to a food-retail refrigeration footprint consolidation, which Tobin estimated cost one to one and a half points of group organic growth. Group bookings rose 16.1% to $2.3bn across all five segments and guidance went up, to $10.55-10.75 adjusted earnings per share. The shares fell 9.7% that day and 11.1% over three months. Dover is now the cheapest of the three at 18.0x forward earnings against 23.1x trailing.
The name that stayed still
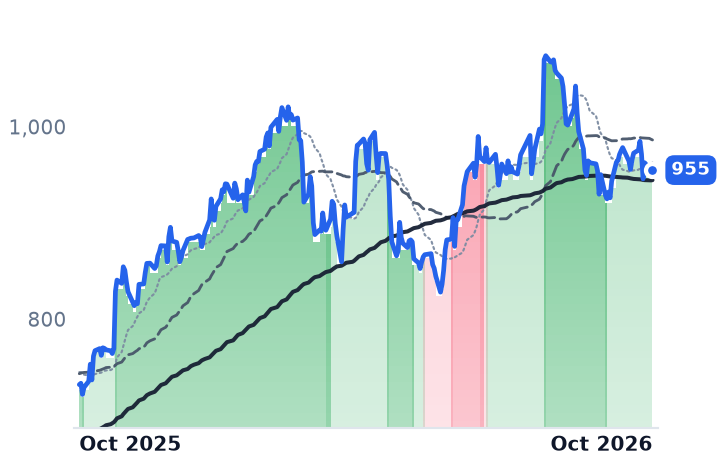
Parker-Hannifin's Quick Coupling Division is the meaningful number two bidding for the same socket, with Stäubli and Walther-Präzision as European challengers. Its June quarter was aerospace: record segment sales of $1.9bn, 13.4% organic growth, orders up 18% and backlog up 15% to $8.5bn. Parker was flat over three months and is the most expensive of the three at 26.9x forward against 33.0x trailing. Its flatness is the cleanest evidence that what sold was cooling content.
So the three-month decline has one documented cause and one undocumented one. Dover's own factory move explains a measurable slice of its quarter, and the company named it. Nothing SPX has published explains a fall of more than a fifth: orders, backlog, guidance and disclosed data-center revenue all moved up, and sell-side analysts argued the January spec change was misread, with TD Cowen noting cooling towers remain essential to heat rejection in liquid-cooled systems. What the price now carries is leverage and customer funding, neither of which shows up in a backlog figure.
The heat still has to go somewhere. SPX's own account of where says $430m of it this year, and the shares have spent three months pricing an answer the company has not given.