

Prepaid Tuition at TAL and New Oriental Is Growing Slower Than the Revenue It Funds
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Chinese tutoring companies collect the fee before the class is taught, which makes the prepaid balance the one line in their accounts that leads the income statement. At TAL Education, New Oriental and Gaotu Techedu that balance is now growing more slowly than reported revenue — TAL's deferred tuition rose 25.9% in the year to 31 May against revenue up 31.9% — and guidance follows the book, with New Oriental pointing to 14–18% revenue growth this fiscal year.
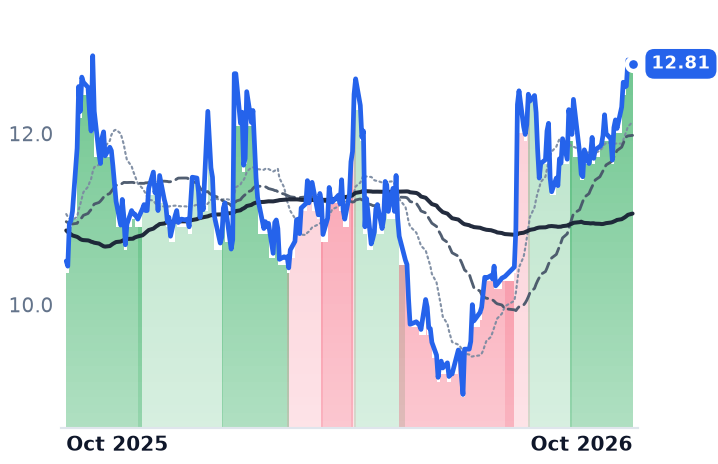
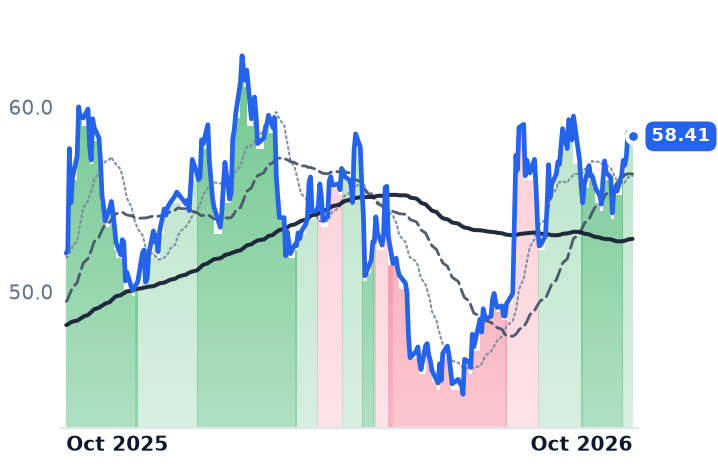
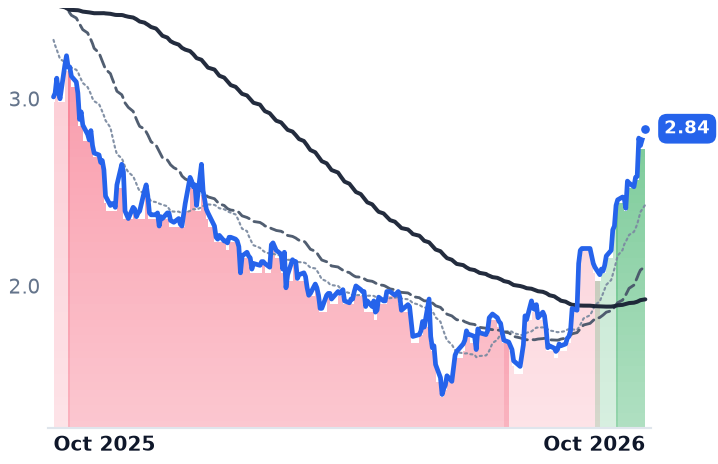
The shares went the other way. All three were in downtrends in July and in uptrends by late September, Gaotu most of all, with no earnings release inside the thirty days to 9 October. TAL's results carry the move best: an 18.1% operating margin on capacity leased a year early. Gaotu's carry it worst, with selling expense alone absorbing 54.7% of revenue.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
TAL | TAL Education | China K-12 Tutoring | 🟢 Cont. Bull | +10.0% | +21.9% |
EDU | New Oriental Education & Technology | China K-12 Tutoring | 🟢 Cont. Bull | +2.8% | +12.2% |
GOTU | Gaotu Techedu | China K-12 Tutoring | 🌱 Emerging Bull | +37.9% | −5.6% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TAL | $7.8B | 2.6x | 9.1x | 2.4x | 2.1x | 4.4x | 3.7x | 8.4x | 8.2% |
EDU | $9.3B | 19.6x | 13.3x | 1.7x | 1.4x | 3.0x | 2.6x | 10.7x | 8.1% |
GOTU | $997.5M | n/m | — | 1.0x | — | 1.5x | — | n/m | 3.7% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
TAL | Revenue | +31.9% | +25.5% | +17.6% |
| EPS | +188.3% | +125.1% | −13.5% | |
EDU | Revenue | +14.8% | +19.0% | +12.3% |
| EPS | +27.1% | +26.3% | +15.9% | |
GOTU | Revenue | +15.9% | +13.4% | +11.0% |
| EPS | −102.1% | +1992.9% | +70.0% |
Forward fiscal years only. Blank means no analyst coverage for that year.
China's tutoring companies are paid before they teach. Parents settle the term at enrollment, the money sits as a liability, and it turns into revenue class hour by class hour as the course is delivered. That makes the prepaid balance the only figure in these accounts that moves ahead of the income statement, and at TAL Education, the Beijing provider of after-school small-group classes under the Xueersi brands, it grew 25.9% in the year to 31 May, to $1.22bn, while the revenue it funds grew 31.9%.
The past quarter has been read as a recovery still gathering force: the three listed operators of this business left July downtrends behind and rose about 31% equal-weighted over three months. Their collections say the fastest point is behind them. New Oriental's deferred revenue rose 14.8% against 23.2% revenue growth; Gaotu's 18.9% against 20.2%. At each one the reported line is draining a book that was filled at a quicker rate, and both companies that gave guidance pointed at the high teens.
The regulator decides how far the money can run ahead
A framework issued by 13 departments including the Ministry of Education bars non-academic tutoring institutions from collecting a lump sum covering more than three months, 60 class hours or RMB5,000, about $716, and requires offline classes to finish by 20:30. So the forward book cannot be a year deep. Derived from the filings, TAL's balance equals 1.61 times the $758.4m it recognized in the May quarter, New Oriental's 1.46 times and Gaotu's 1.56 times: the same cushion of roughly a quarter and a half at three companies of very different size. The cash timing inside the year is violent. TAL took in $478.2m of operating cash in the May quarter, 63% of that quarter's revenue, after using $215.0m in the February quarter.
TAL filled capacity it had already leased
TAL's operating margin reached 18.1% in the May quarter against 2.5% a year earlier, on a gross margin of 57.8%, the best in five quarters. Centers are leased and staffed before seats are sold — more than 600 across 44 cities — so that margin is a utilization reading. "Our first quarter performance in fiscal year 2027 reflects solid execution across our businesses," president and chief financial officer Alex Peng said on 30 July. Two qualifications: revenue rose 32% in dollars but only 25% in renminbi, and the learning-content slab of books, apps and devices reached 35.3% of fiscal 2026 revenue from 31.8%. Yet group gross margin widened to 55.4% from 53.3%, so the hardware mix is not visibly diluting the service margin. The shares trade at 9.1x forward earnings, with price-to-gross-profit compressing to 3.73x forward from 4.37x trailing.
New Oriental's grocery arm is taking the margin
New Oriental's revenue growth accelerated through fiscal 2026 — 6.1%, 14.9%, 19.8%, then 23.2% — and non-GAAP operating margin reached 7.5%, up 470 basis points. Here the mix dilution is real: East Buy, the consolidated livestreaming and private-label goods business, grew 34.4% to $806.9m, 14.3% of sales, while group gross margin slipped to 54.6% from 55.4%. Overseas test preparation, the product the 2021 academic ban left untouched, grew only 6%; adults and university students grew 30%; non-academic tutoring booked 1,072,000 enrollments. "In this fiscal quarter, we executed cautious capacity expansion while carefully balancing revenue growth and operational efficiency," chief executive Chenggang Zhou said on 29 July. At 19.6x trailing earnings against 13.3x forward, the spread is what is being paid for that 14–18% guide, alongside a commitment to return no less than half of prior-year net income.
Gaotu buys its students at a price its classroom cannot cover
Gaotu's selling expenses were CNY913.2m in the June quarter, 54.7% of revenue, against a 66.5% gross margin: acquisition consumes about four-fifths of each gross-profit yuan, which is how that gross margin still ends at minus 9.0% at the operating line. Revenue growth has run 30.7%, 21.4%, 12.5% and 19.9% over four quarters, with the September quarter guided to 16.4–17.7%. The first half of 2026 carries a CNY101.2m net loss against a consensus full-year profit of CNY14.4m. "Footprint growth itself is not the main KPI," chief operating officer Bin Luo said on 27 August, naming profitable sites as the goal. Gaotu moved most of the three, up 49.5% over three months, and is still down 14.3% over twelve.
Thirty days with nothing in them
No filing falls inside the window: TAL last reported on 30 July, New Oriental on 29 July, Gaotu on 27 August. A Central Committee and State Council document on vocational education lifted all three in one session, TAL more than 4% and Gaotu about 1%. The likelier reading of the re-rating is sector and policy rather than anything that happened in a classroom. What the results do support is operating leverage at TAL, where a year-old capacity decision is now being absorbed, and the margin step at New Oriental. What they do not support is growth still accelerating anywhere in the group: New Oriental, the fastest accelerator on paper, had already eased back to a milder uptrend on 5 October.
Beijing has not softened. In January regulators fined an unregistered education firm RMB67m, explicitly to kill rumors of an academic-tutoring comeback. What these three sell is what the rules permit, collected three months at a time, and three months is all the warning their balance sheets are allowed to give.