

Booking Holdings Guided Its Year Assuming Seven Months of Middle East Disruption
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Online travel's September selloff was read as proof that AI booking agents will bypass the intermediaries. What October's evidence names is duller and more cyclical: long-haul air. Wells Fargo's target cut on Booking Holdings blamed prolonged Middle East conflict, and the airline industry's own forecaster has cut 2026 passenger traffic growth to 2.1% from 4.9%, while the US hotel market's revenue forecast was revised up.
Underneath one industry label, three businesses are moving apart. Booking's revenue growth halved to 8.1% year on year as its traffic bill grew faster than its bookings; Expedia's accelerated for a fourth straight quarter, to 14.0%, with operating margin far above last year's; MakeMyTrip grew gross bookings 19.9% in constant currency and reported 6.2% revenue growth, the rupee at a record low taking the difference.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
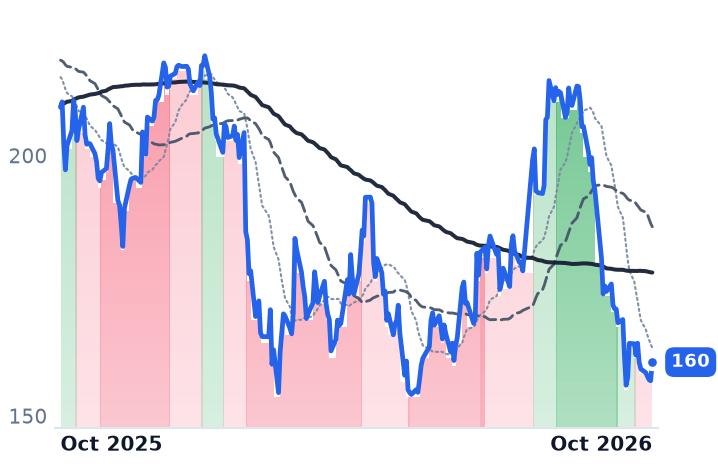
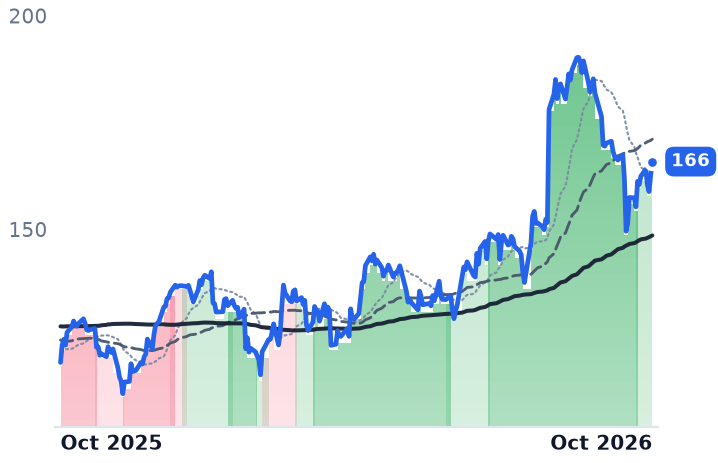
BKNG | Booking | Online Travel Agencies | 🌱 Emerging Bull | −7.8% | −23.4% |
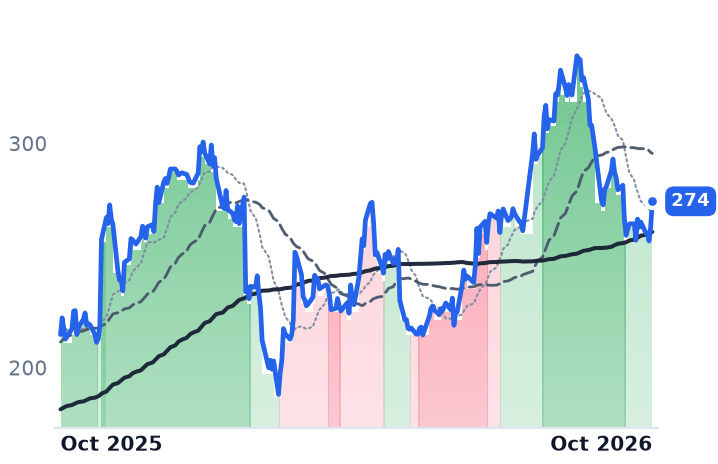
EXPE | Expedia | Online Travel Agencies | 🟢 Cont. Bull | −2.4% | +27.7% |
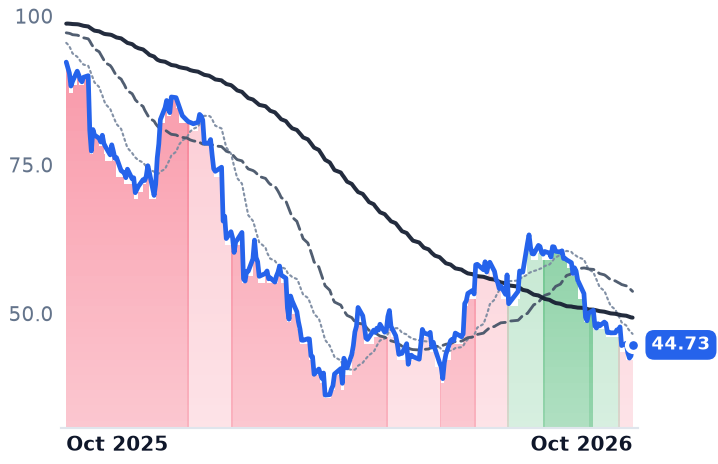
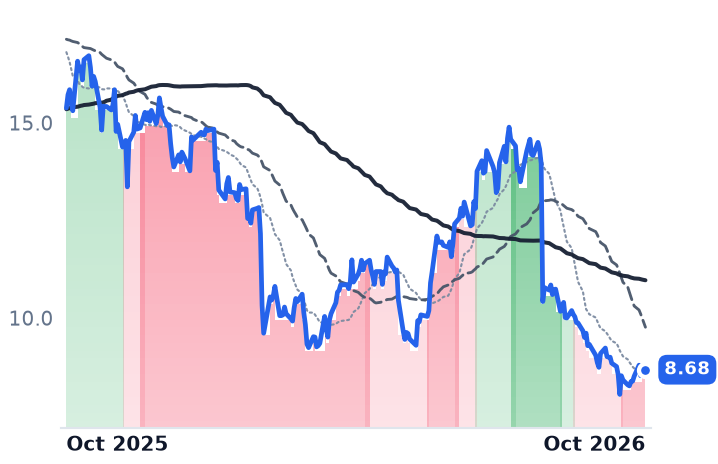
MMYT | MakeMyTrip | Online Travel Agencies | 🔴 Cont. Bear | −10.7% | −51.5% |
| Compared against · context, not the story | |||||
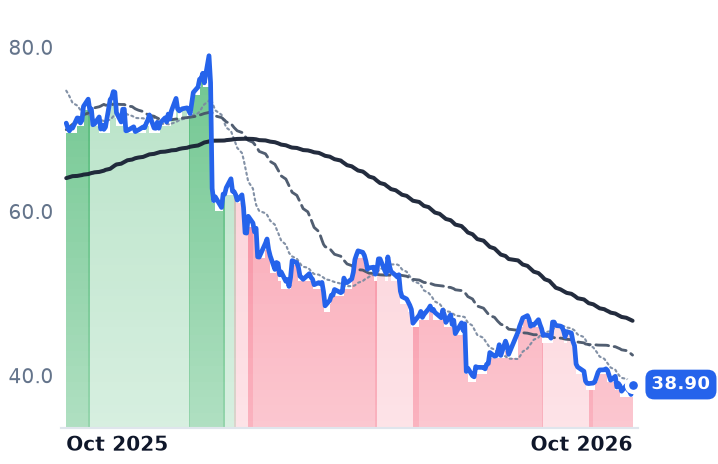
TCOM | Trip.com | Online Travel Agencies | 🔴 Cont. Bear | −0.3% | −45.0% |
ABNB | Airbnb | Alternative Accommodations | 🟢 Cont. Bull | −2.5% | +39.6% |
TRIP | Tripadvisor | Marketplace & Local Services | 🔴 Cont. Bear | −4.6% | −43.6% |
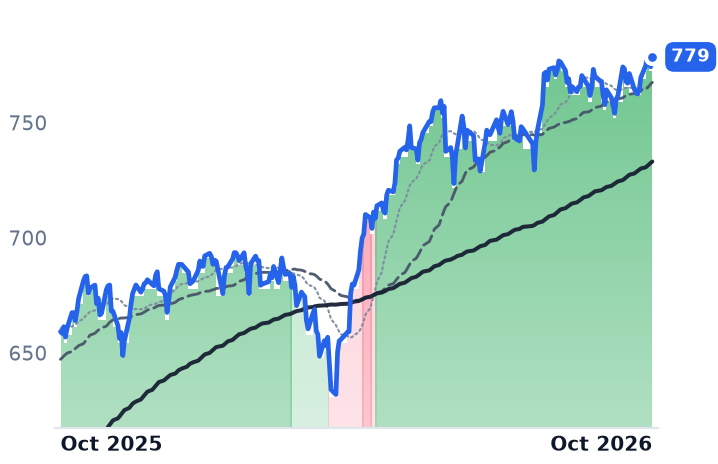
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | +1.9% | +18.1% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
BKNG | $124.2B | 17.7x | 15.3x | 4.4x | 4.2x | 4.4x | 4.2x | 11.8x | 7.7% |
EXPE | $31.4B | 16.4x | 13.1x | 2.0x | 1.9x | 2.2x | 2.1x | 7.7x | 16.1% |
MMYT | $4.2B | 126.7x | 91.4x | 4.0x | 3.5x | 5.7x | 5.1x | 25.9x | 2.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TCOM | $24.7B | 7.0x | — | 2.5x | — | 3.1x | — | 4.8x | 8.3% |
ABNB | $78.8B | 31.6x | 25.9x | 6.2x | 5.7x | 7.5x | 6.8x | 28.9x | 5.8% |
TRIP | $1.0B | 216.9x | 10.7x | 0.6x | 0.6x | 0.7x | 0.8x | 5.5x | 13.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
BKNG | Revenue | +9.6% | +9.4% | +8.2% |
| EPS | +15.0% | +18.1% | +16.6% | |
EXPE | Revenue | +11.0% | +7.1% | +7.2% |
| EPS | +36.3% | +17.3% | +15.1% | |
MMYT | Revenue | +12.6% | +7.3% | +17.1% |
| EPS | −48.0% | +12.0% | +103.6% | |
TCOM | Revenue | +8.0% | +8.7% | +10.5% |
| EPS | −48.5% | +13.5% | +12.2% | |
ABNB | Revenue | +14.6% | +10.5% | +10.6% |
| EPS | +24.2% | +18.1% | +18.2% | |
TRIP | Revenue | −17.0% | +0.6% | +4.8% |
| EPS | −40.4% | +24.3% | +40.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
The October cut named geography, not the checkout page
Wells Fargo cut its price target on Booking Holdings, which collects a commission on hotel rooms, flights and cars it does not own through Booking.com, Agoda, Priceline, KAYAK and OpenTable, to $190 from $220 on 7 October, keeping an Equal Weight rating. The reason the bank gave was not artificial intelligence. It cited prolonged Middle East conflict pressuring long-haul demand, weighing on Booking more than peers given its geographic footprint, and trimmed its third-quarter room-night growth estimate to 5.5%.
The preceding six weeks had been read as the disintermediation trade arriving at last. Meta launched Muse, a personal AI agent able to complete a booking by itself, in the United States on 8 September; Expedia agreed on 22 September to sell hotel rooms inside it while remaining the merchant collecting the payment, and the market read the arrangement as a loss for both names, Expedia closing 5.5% lower that session and Booking 4.2%. Booking's own finance chief had already sized that channel. Referral traffic from large language models is "under 1% of room nights" and "hasn't moved so much recently," Ewout Steenbergen said on the 4 August call.
What Booking's August guidance already contained
The company's framework for the year assumed seven of its twelve months carry Middle East disruption. "We are at a high single-digit level for gross bookings and revenues and at mid-teens level for EPS at the high end," Steenbergen told investors on 4 August. Consensus has since settled where that guidance pointed: revenue up 9.6% for 2026 and earnings per share up 15.0%.
The June quarter is the base. Revenue of $7.352bn grew 8.1% year on year, half the 16.2% of the March quarter, on gross bookings of $51.0bn — a 14.4% commission take. Room nights rose 5% while marketing spend rose 11%, to $2.37bn, which management attributed on the same call to "changes in traffic mix, incremental investments in paid marketing at attractive ROIs, and a shift of merchandising spend to performance marketing." Operating margin still widened, to 34.0% from 33.1%, so the deceleration is a volume and price story rather than a cost one.
The route around it by acquisition is closed. On 9 September the EU General Court upheld the prohibition of Booking's eTraveli deal, the flight-booking purchase that would have put the air ticket next to the room night.
Meanwhile the rooms themselves are firming. CoStar and Tourism Economics raised their 2026 US revenue-per-available-room forecast to 4.4% from 2.8%. It is the flights that thinned: the International Air Transport Association cut 2026 passenger traffic growth to 2.1% from 4.9% and expects Middle East traffic to contract 11.4% in a region that handles more than 40% of global connecting traffic, on jet fuel averaging $152 a barrel against roughly $90 in 2025.
Booking closed at $160.34 on 9 October, down 24.8% from its 25 August close and 26.0% over twelve months. The shares now change hands at 15.3x forward earnings against 17.7x trailing and a ten-year average CNBC puts at 22.3x, with a 7.7% trailing free-cash-flow yield.
Expedia's year went the other way
Expedia Group, which runs Brand Expedia, Hotels.com and Vrbo alongside a wholesale arm selling travel inventory into other companies' checkout pages, has grown revenue faster for four straight quarters, reaching 14.0% in the June quarter, with operating margin at 23.9% against 14.0% a year earlier. Its business-to-business gross bookings rose 21%, to $10.74bn, against 8% in consumer bookings, and the cash it collects before guests travel — deferred merchant bookings — reached $14.4bn at 30 June against $9.3bn at year-end. It trades at 13.1x forward earnings against 16.4x trailing and is up 22.5% over twelve months, the only one of the three still higher. Chief executive Ariane Gorin told the Skift Global Forum on 23 September: "I certainly personally don't believe that a large portion of bookings are going to be an end-to-end conversational experience." A Sherman Act class action filed in Washington federal court on 2 October alleges it imposed restrictive pricing terms on hotels.
The rupee does MakeMyTrip's talking
MakeMyTrip, the Indian platform behind makemytrip.com, goibibo.com and redbus.in, grew June-quarter gross bookings 19.9% in constant currency, to $2,854.7m, with hotels and packages outgrowing air ticketing. Reported revenue grew 6.2%; the rupee touched a record low of 96.775 per dollar on 9 October, down about 9% over twelve months. Net income fell 67.8%, to $8.35m, and the shares still carry 91.4x forward earnings after a 53.0% twelve-month decline.
So the industry label describes an accounting convention, not a shared exposure. Booking's markdown is part earned: growth genuinely halved and the traffic bill is rising faster than the volume it buys, which is a margin claim on every future booking. What the October evidence does not support is the version in which the checkout page was taken away, because the hotel market it distributes was revised up and the measured AI referral share is under a hundredth of room nights. MakeMyTrip's decline is translation plus a collapsed profit line at the group's dearest multiple. Expedia's fall of 18.8% since late August has no deterioration behind it at all.
Booking's last disclosed room-night growth was 5%. Its third-quarter results are due on 3 November and Expedia's on 4 November, and the line that settles the argument is not revenue but the count of nights actually stayed.