

Fair Isaac Lost Rocket Mortgage to a 99-Cent Score and Kept United Wholesale's Fee
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Two large mortgage lenders answered the federal housing regulator's scoring ruling in the same week, and answered it differently. Rocket Mortgage will make the rival VantageScore 4.0 its preferred model for all eligible loans from the fourth quarter. United Wholesale Mortgage will keep buying Fair Isaac's score on every broker credit pull, but will now pull both and automatically use whichever qualifies the borrower.
So Fair Isaac keeps the inquiry fee at United Wholesale and gives up the guarantee that its number prices the loan. The June quarter showed the royalty still working: Scores revenue up 41% to $458.9m, with mortgage score units up only low single digits. None of that speaks to 2027, where the Mortgage Bankers Association now sees $2.101trn of originations against $2.123trn expected this year. The shares sit at 13.4x a fiscal 2027 consensus profit that has not been cut.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
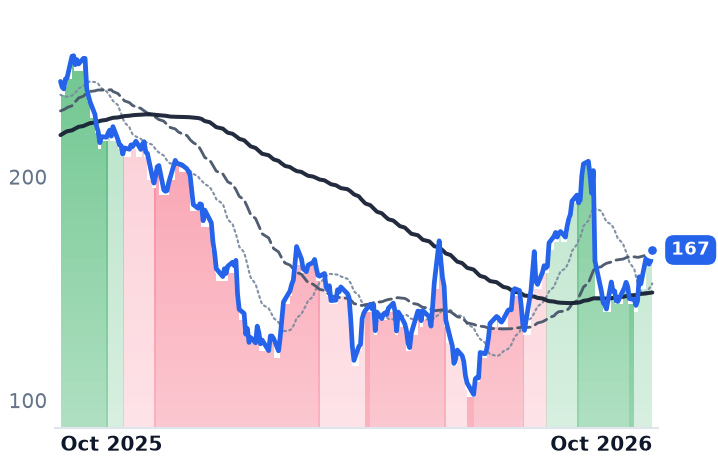
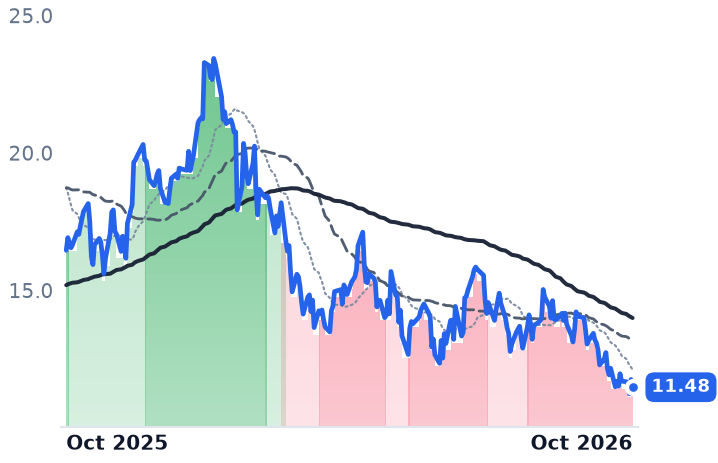
FICO | Fair Isaac | Financial Services Software | 🔴 Cont. Bear | −32.3% | −59.5% |
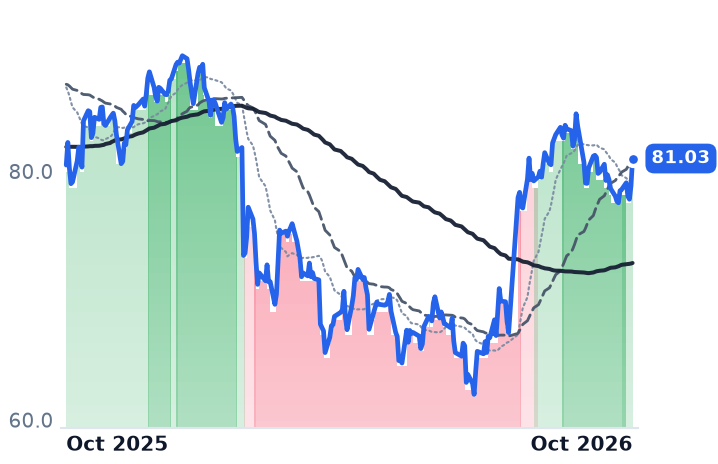
QTWO | Q2 | Financial Services Software | 🌱 Emerging Bull | −3.8% | −4.8% |
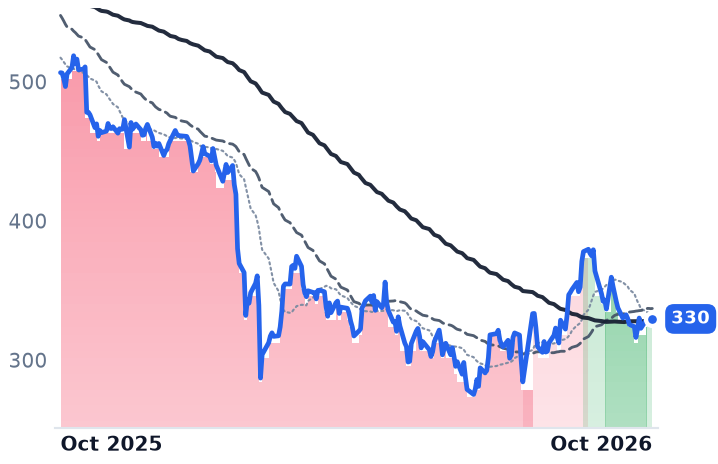
VERX | Vertex | Financial Services Software | 🔴 Cont. Bear | +5.6% | −47.6% |
| Compared against · context, not the story | |||||
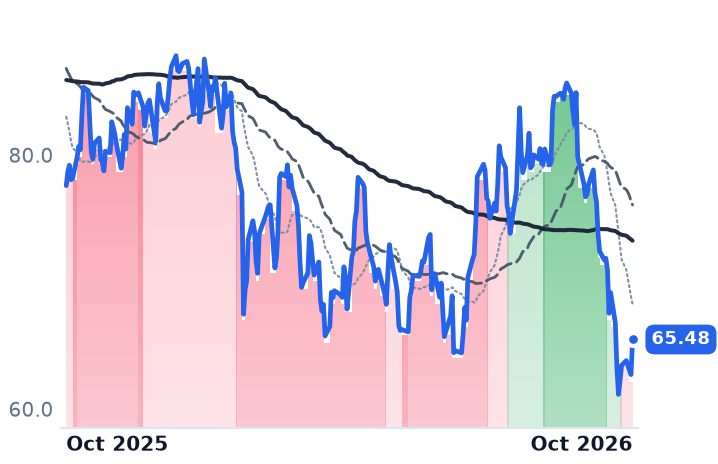
ALKT | Alkami Technology | Financial Services Software | 🌱 Emerging Bull | −30.3% | −38.2% |
GWRE | Guidewire Software | Financial Services Software | 🌱 Emerging Bull | +18.7% | −31.1% |
SSNC | SS&C Technologies | Financial Services Software | 🌱 Emerging Bull | +0.9% | +0.7% |
TYL | Tyler Technologies | Financial Services Software | 🌱 Emerging Bull | −2.1% | −34.9% |
TRU | TransUnion | Credit & Risk Intelligence | 🌱 Emerging Bull | −15.7% | −15.6% |
RKT | Rocket Companies | Residential Mortgage Originators | 🔴 Cont. Bear | −12.9% | −30.3% |
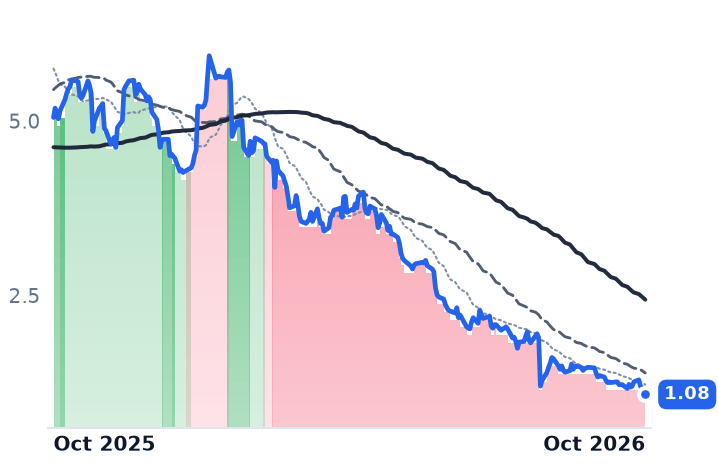
UWMC | UWM | Residential Mortgage Originators | 🔴 Cont. Bear | −20.0% | −78.6% |
12-month price & trend
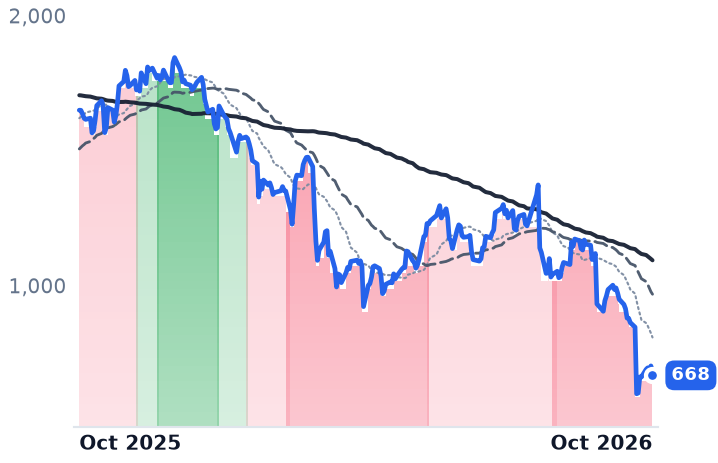
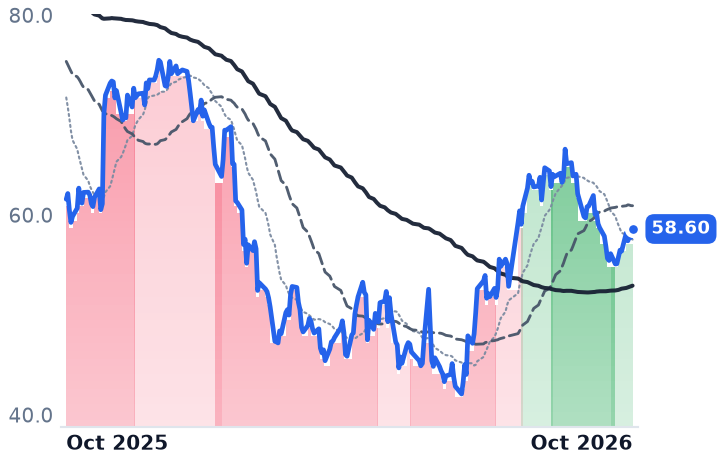
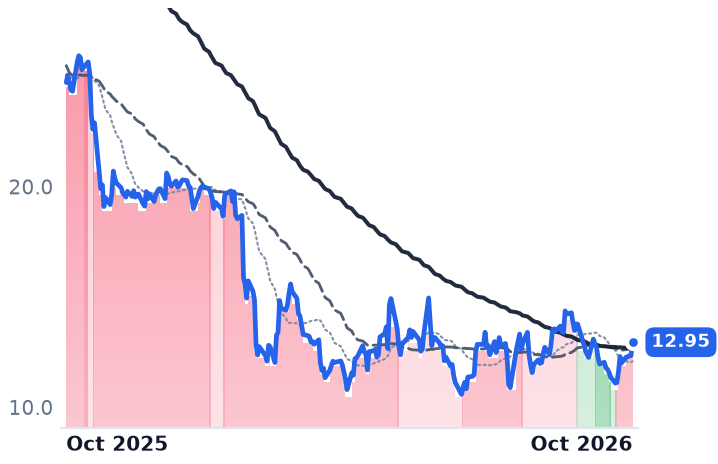
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FICO | $14.4B | 19.2x | 13.4x | 6.0x | 5.1x | 7.1x | 6.0x | 15.6x | 6.9% |
QTWO | $3.7B | 39.6x | 20.2x | 4.3x | 4.1x | 7.6x | 7.2x | 24.2x | 5.5% |
VERX | $2.1B | 423.2x | 15.8x | 2.7x | 2.5x | 4.3x | 4.1x | 42.3x | 2.8% |
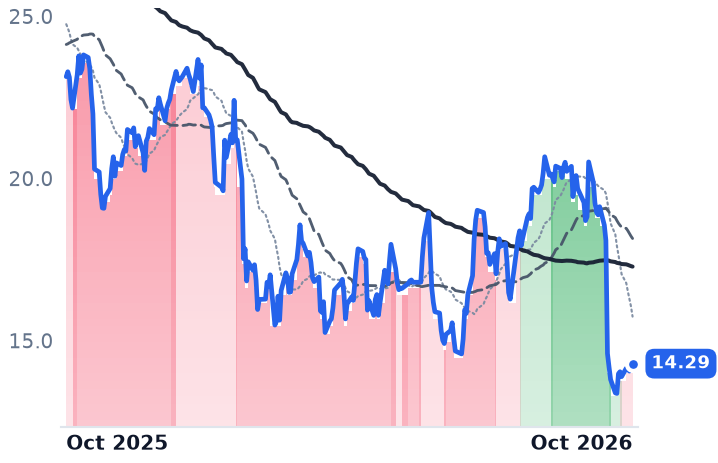
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ALKT | $1.6B | n/m | 18.6x | 3.2x | 2.9x | 5.6x | 5.2x | n/m | 4.2% |
GWRE | $12.7B | 92.7x | 36.5x | 8.6x | 7.4x | 13.4x | 11.5x | 61.1x | 2.3% |
SSNC | $18.7B | 22.3x | 11.2x | 2.8x | 2.8x | 5.9x | 5.7x | 11.7x | 9.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TYL | $13.6B | 43.6x | 25.4x | 5.6x | 5.3x | 12.0x | 11.4x | 29.7x | 5.2% |
TRU | $12.8B | 18.1x | 13.9x | 2.7x | 2.5x | 5.1x | 4.7x | 12.1x | 5.5% |
RKT | $37.7B | 157.8x | 18.1x | 4.4x | 3.2x | 4.9x | 3.6x | 38.6x | -3.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
UWMC | $4.5B | 13.2x | 7.6x | 1.5x | 1.4x | 1.8x | 1.7x | 19.7x | -122.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
FICO | Revenue | +27.5% | +10.4% | +9.1% |
| EPS | +45.3% | +16.6% | +14.4% | |
QTWO | Revenue | +11.8% | +10.1% | +10.6% |
| EPS | +22.1% | +19.5% | +32.6% | |
VERX | Revenue | +10.6% | +10.5% | +11.6% |
| EPS | +28.4% | +24.0% | +21.0% | |
ALKT | Revenue | +19.6% | +16.7% | +14.5% |
| EPS | +51.0% | +38.2% | +25.0% | |
GWRE | Revenue | +23.8% | +17.2% | +15.7% |
| EPS | +41.5% | +20.8% | +27.4% | |
SSNC | Revenue | +8.6% | +5.0% | +4.8% |
| EPS | +17.2% | +9.6% | +7.4% | |
TYL | Revenue | +8.8% | +9.9% | +8.9% |
| EPS | +14.7% | +17.5% | +14.3% | |
TRU | Revenue | +13.0% | +8.2% | +7.7% |
| EPS | +12.0% | +16.7% | +17.5% | |
RKT | Revenue | +84.6% | +11.2% | +9.7% |
| EPS | +204.0% | +48.3% | +16.7% | |
UWMC | Revenue | +26.8% | +11.1% | +7.0% |
| EPS | +142.0% | +29.8% | +28.3% |
Forward fiscal years only. Blank means no analyst coverage for that year.
In the first week of October the two lenders whose decisions matter most to Fair Isaac's mortgage royalty went opposite ways. Rocket Mortgage said it will make VantageScore 4.0 its preferred credit-scoring model on all eligible loans from the fourth quarter, after about four months of testing found more clients qualified and scoring costs fell. Two days later United Wholesale Mortgage, which lends through brokers, reaffirmed that it will keep using FICO Scores on every credit pull.
That reaffirmation is narrower than it reads. United Wholesale will now pull both scores and automatically use the strongest qualifying result at loan level. Fair Isaac, which licenses the FICO credit score and sells decisioning software to lenders, still collects its fee on the inquiry; what it no longer has is the certainty that its number is the one the loan is priced off. That distinction is the argument left after the 29% single-session fall on 29 September, which followed the housing regulator's move to a single pricing grid treating loans made with either score equally at Fannie Mae and Freddie Mac.
The quarter nobody is arguing with
There is no damage in the reported numbers. June-quarter Scores revenue was $458.9m against $324.3m a year earlier, the business-to-business half up 49% "primarily attributable to a higher mortgage origination scores unit price." Mortgage-origination score volumes rose low single digits while revenue from them climbed 97%. Group revenue grew 25.7% and operating margin reached 53.8% from 48.9%.
That is the arithmetic of a published price list: $0.60 rising to $4.95 over five years, then more than doubling to $10 a score for 2026, passed through by the credit bureaus and resellers who face the lender. Mortgage originations were 71% of business-to-business Scores revenue. The price is set by Fair Isaac; the units are set by borrowers.
Both legs of the toll now point down
TransUnion has extended standalone mortgage pricing on the rival score at 99 cents through December 2028 and bundles it free with a FICO purchase; more than 1,100 mortgage lenders used it between January and September. Fair Isaac's answer has been to restructure the toll rather than hold the headline price: its direct-licence program for resellers offers a $4.95 royalty per score plus a $33 fee per borrower when a FICO-scored loan funds, or the $10 per-score rate unchanged.
The base the royalty multiplies is shrinking too. The Mortgage Bankers Association now puts 2027 originations at $2.101trn, below the $2.123trn expected for 2026, with the 30-year fixed rate at 7.49%.
Chief executive Will Lansing was blunt about the regime on the 29 July call: "The rules of the road, the environment that we're operating in is a gaming environment. The FHFA has put it in place. The GSEs have accepted it. And so that's the world we have."
What $1.96bn of buyback cannot settle
Management spent $1.96bn repurchasing stock into the decline, and diluted shares fell from 23.958m to 22.703m in two quarters, a reduction of roughly 5% by that arithmetic and a real slice of per-share growth. The shares have recovered 11.4% from their $599.51 low and remain 63.8% below the 52-week high. Brokers including Wells Fargo and Goldman Sachs cut price targets after 29 September without cutting their ratings.
So the results account for none of the fall and the regulator accounts for most of it. At 19.2x trailing earnings against roughly 62x in January the compression is real, but the 13.4x forward figure rests on a fiscal 2027 consensus of $49.95 a share assembled before the pricing grid existed. Cheapness measured against an anchor Washington has invalidated is not cheapness.
Fair Isaac's fiscal year closed on 30 September. The next report is the first that can publish a 2027 price list and show how many scoring units stayed after Rocket's switch, and until it does, a franchise that has always been priced on what lenders had to buy is being valued on what they now choose to.