

SpaceX's Spectrum Buy Repriced the Tower Landlords for a Tenant With No Lease Signed
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
A single October session added more than a tenth to the value of all three listed US tower landlords and took roughly a tenth off each of the three carriers that pay most of their rent. The cause was dated and named: SpaceX agreed to buy Grain Management's nationwide 800 MHz licences, a band that penetrates walls and therefore has to be radiated from the ground.
What the buyers are paying for is a lease nobody has signed. SpaceX has described hanging small radios beside existing Starlink dishes on a limited number of host rooftops. Meanwhile the rent the towers already hold is in court: Crown Castle's second-quarter organic billings grew 3.9% only before a $49m hit from DISH terminations, and the three towercos are pressing about $7.6bn of disputed claims in DISH Wireless's bankruptcy. After the pop Crown Castle carries the highest trailing EV/EBITDA of the three at 21.0x.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
CCI | Crown Castle | Wireless & Fiber Infrastructure | 🔴 Cont. Bear | +5.3% | −15.1% |
AMT | American Tower | Wireless & Fiber Infrastructure | 🔴 Cont. Bear | +2.5% | +1.4% |
SBAC | SBA Communications | Wireless & Fiber Infrastructure | 🔴 Cont. Bear | −1.6% | −1.8% |
| Compared against · context, not the story | |||||
EQIX | Equinix | Data Center & Colocation | 🟢 Cont. Bull | −1.1% | +28.7% |
DLR | Digital Realty Trust | Data Center & Colocation | 🟢 Cont. Bull | −5.2% | +5.7% |
TMUS | T-Mobile US | Wireless Carriers | 🔴 Cont. Bear | −18.5% | −33.3% |
T | AT&T | Wireless Carriers | 🌱 Emerging Bull | −14.9% | −11.4% |
VZ | Verizon Communications | Wireless Carriers | ⚠️ Emerging Bear | −17.7% | +8.2% |
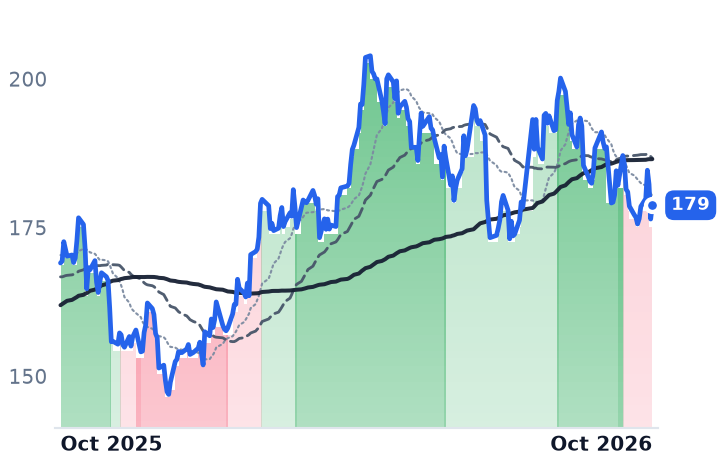
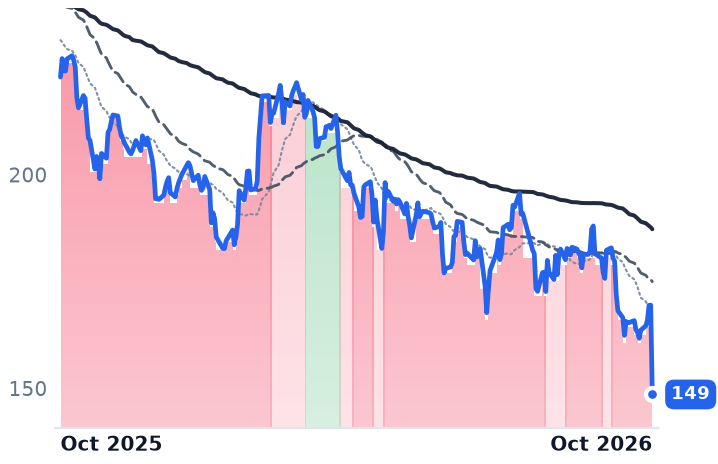
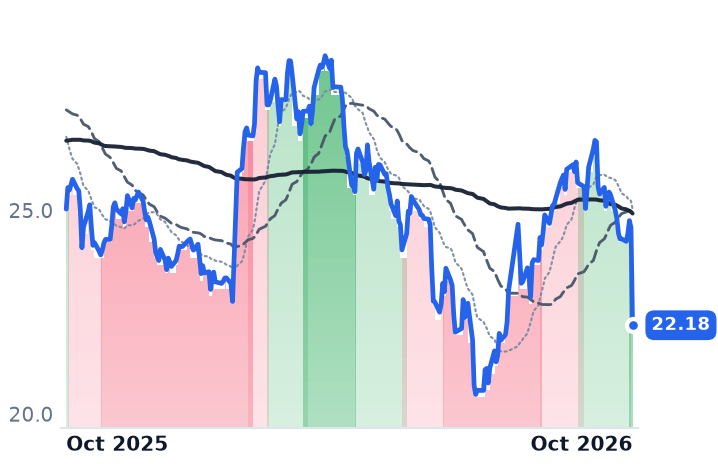
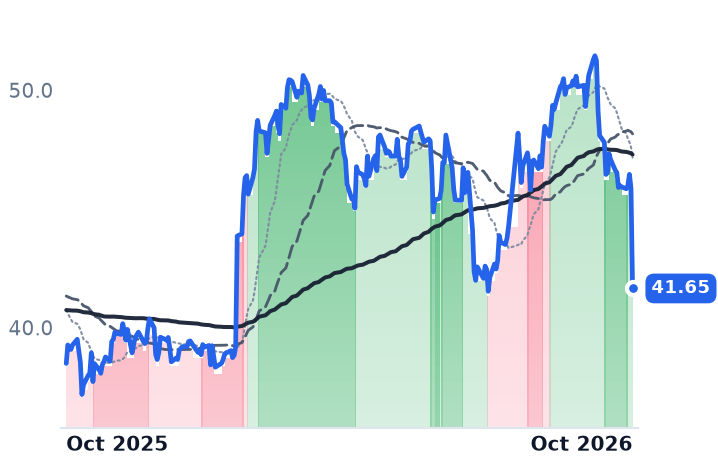
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CCI | $34.8B | 32.2x | 41.4x | 8.4x | 8.6x | 13.2x | 13.6x | 21.0x | 6.9% |
AMT | $84.9B | 25.0x | 26.1x | 7.8x | 7.7x | 10.6x | 10.5x | 18.3x | 4.7% |
SBAC | $19.4B | 19.6x | 23.7x | 6.7x | 6.8x | 10.6x | 10.6x | 17.0x | 5.4% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EQIX | $101.2B | 65.8x | 59.6x | 10.3x | 9.9x | 20.0x | 19.1x | 27.5x | 1.4% |
DLR | $66.1B | 82.4x | 65.1x | 9.7x | 9.3x | 70.2x | 67.5x | 24.2x | 2.1% |
TMUS | $195.9B | 19.1x | 16.7x | 2.1x | 2.1x | 3.9x | 3.8x | 10.9x | 7.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
T | $170.5B | 8.2x | 10.6x | 1.3x | 1.3x | 2.2x | 2.2x | 5.9x | 10.4% |
VZ | $202.4B | 12.6x | 9.7x | 1.5x | 1.4x | 2.5x | 2.4x | 8.1x | 10.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
CCI | Revenue | −5.1% | +1.3% | +2.4% |
| EPS | +106.9% | +46.8% | +4.8% | |
AMT | Revenue | +4.1% | +3.3% | +6.1% |
| EPS | +36.1% | +1.1% | +11.6% | |
SBAC | Revenue | +1.5% | +2.5% | +3.6% |
| EPS | −21.8% | +8.2% | +10.1% | |
EQIX | Revenue | +11.1% | +10.8% | +11.6% |
| EPS | +16.6% | +10.4% | +10.1% | |
DLR | Revenue | +17.5% | +11.0% | +14.4% |
| EPS | −25.0% | −6.2% | +24.6% | |
TMUS | Revenue | +7.1% | +4.4% | +4.0% |
| EPS | +10.2% | +27.4% | +20.0% | |
T | Revenue | +3.4% | +2.1% | +2.1% |
| EPS | +13.6% | +9.4% | +13.7% | |
VZ | Revenue | +2.3% | +1.7% | +1.1% |
| EPS | +6.8% | +4.7% | +7.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
SpaceX agreed on 9 October to buy a nationwide portfolio of 800 MHz licences from the investment firm Grain Management, and the market promptly paid three landlords for a customer that has signed nothing. Crown Castle, which leases vertical space on more than 40,000 US cellular towers to wireless carriers, closed the session up 16.8% on 14.17m shares against roughly 3m on typical early-October days. American Tower rose 10.4% and SBA Communications 9.1%.
The same session took T-Mobile US down 12.3%, AT&T down 9.7% and Verizon down 9.2%. The physics explains the split. The 800 MHz band is low-band coverage that works through walls and ceilings, which satellites cannot do, so it is hard to use from orbit and easy to use from a tower. One headline therefore read as a prospective fourth tenant for the steel and a fourth national competitor for the carriers. The belief being bought is that a new network means new leases on existing towers.
The buildout SpaceX has actually described
The deal was valued at about $8bn by the Wall Street Journal, covers up to 14 MHz of paired licences, and needs approval from the Federal Communications Commission; the parties did not disclose terms. Grain bought the portfolio from T-Mobile in August 2026, so the spectrum arming a possible fourth carrier was sold by the carrier that fell hardest on the news.
SpaceX's own stated architecture is the problem with the rally's logic. The company has described housing small cellular radios alongside its existing Starlink broadband dishes on a limited number of host rooftops rather than building new macro towers. President Gwynne Shotwell has told investors the EchoStar spectrum "does have terrestrial components, so we definitely intend to build out the terrestrial component." Intent to transmit from the ground is not intent to rent a lattice. As Wireless Estimator put it the same day, "investors are betting on a new tower tenant that hasn't signed a lease yet."
The rent already signed is the rent in bankruptcy court
A tower dollar is earned under long-dated master lease agreements whose escalators run near 3% a year whatever traffic does, and it is lost through contractual churn. Crown Castle's second-quarter organic contribution to site rental billings was $38m, growth of 3.9%, but only "excluding an unfavorable $49 million and $5 million impact from DISH Terminations and Sprint Cancellations, respectively". The escalator delivered its 3-4%; one defaulted tenant took back more than it gave. American Tower shows the same gap: 1.9% reported organic tenant billings growth, about 4% before DISH.
That loss is a forward event, not a post-mortem. DISH declared its leases excused after the FCC forced parent EchoStar to sell spectrum to AT&T and SpaceX, and the three towercos are pressing roughly $7.6bn of disputed claims, Crown Castle alone about $3.5bn, in a case whose plan confirmation now slips to no earlier than 2 December. The Brattle Group put DISH at 5.1% to 7.0% of annual rental revenues across all three. The regulator that armed the hypothetical tenant is the defence for cancelling the real one's rent.
Three landlords, three different books
Crown Castle's reported revenue fell 4.9% year on year in the second quarter to $1.008bn, mostly the fiber and small-cell businesses sold in May. Its AFFO of $1.13 a share rose 10%, but the company said the increase came "primarily as a result of a decrease in interest expense and an increase in interest income" from the proceeds of that sale. It raised full-year AFFO guidance by $5m to $4.59 a share at the midpoint, inside a $4.53-$4.65 range, and ended the quarter at 6.3x net leverage. The cost side is a ground lease under every site: about 57% of its ground is leased, and the buyout programme plus efficiencies is expected to cut $15m of annual cost.
American Tower grew revenue 4.7% to $2.749bn and has a second meter inside the ticker. CoreSite, its US data-centre arm, had its full-year revenue growth guidance lifted to roughly 15% from 13%, against roughly 4% for the global tower book; European escalators are uncapped and indexed to inflation rather than fixed. SBA Communications is the shrinking domestic control: site-leasing revenue there fell 3.7% to $452.5m on Sprint and EchoStar consolidation, international rose 30.5%, and AFFO per share fell 3.8% to $3.03. Barclays downgraded American Tower and Crown Castle to Equal Weight on collection risk and kept SBA at Overweight for having less of it.
What the single session actually repriced
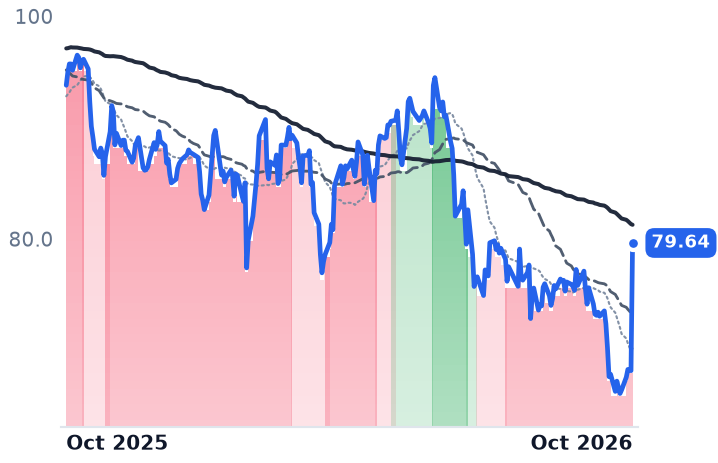
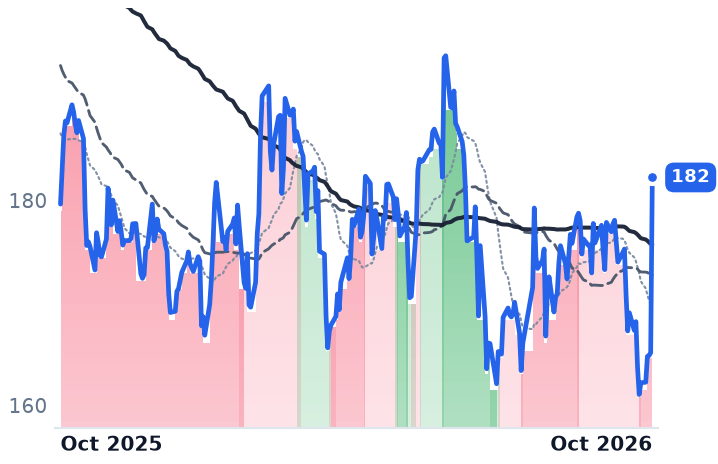
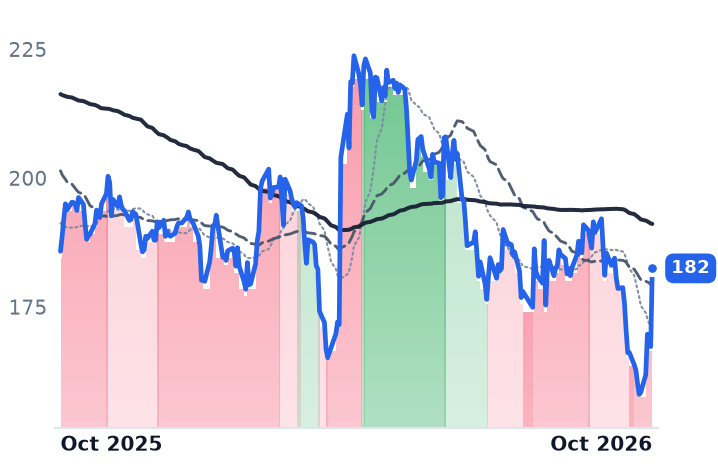
The business record does not account for Crown Castle's move. Its shares closed 9 October at $79.64 against $79.66 ninety days earlier and $96.62 a year before, and have traded below their moving-average trend every day since 17 August, including the day of the jump. After the pop it carries the highest trailing EV/EBITDA of the three at 21.0x, against American Tower's 18.3x and SBA's 17.0x, on the weakest organic growth and the most leverage. American Tower's +8.1% over three months has a decelerating-but-growing book and an accelerating data-centre segment behind it; its 26.1x forward earnings sits below the 28.7x on the Desk's May record. SBA is the cheapest of the three and the only one whose domestic revenue is outright contracting. A 5.24% ten-year Treasury yield is the discount rate under all of them, but it cannot lift one name 16.8% while its customers fall by a tenth.
At the Goldman Sachs Communacopia conference on 9 September, chief executive Chris Hillabrant said "the larger opportunity depends on how quickly carriers move on new spectrum." On 9 October the market decided a company that owns no towers and runs no network had answered him.