

Element Solutions' Holders Refused Its $14.5bn Sale, and the Shares Never Recovered
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
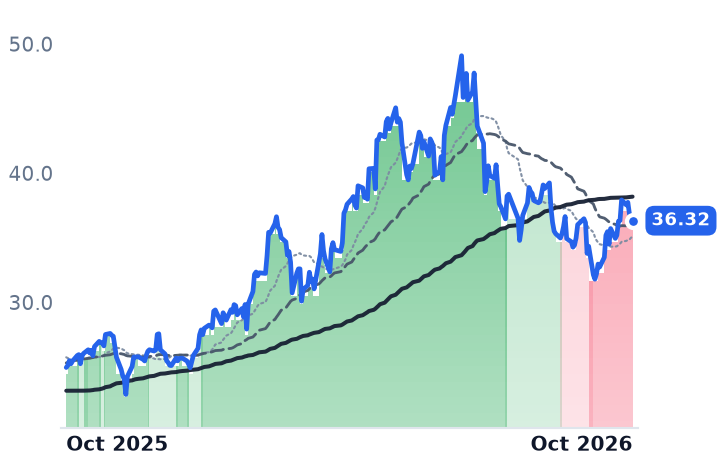
Element Solutions agreed in July to be bought by Solstice Advanced Materials for $10 in cash plus half a Solstice share, about $50.10 apiece. Its own shareholders rejected the stock-heavy consideration, the boards walked away on 27 August with no break fee, and the shares closed 9 October a quarter below their June high.
The business underneath moved the other way. Reported June-quarter revenue rose 56% but only 15% organically, because $107m of metal bought for customers and resold at almost no mark-up inflates the revenue line and pulled gross margin to 34.2% from 42.6%. Strip the metal and Semiconductor Solutions grew 31% on thermal interface materials for artificial-intelligence processors.
The fall dates to a deal, not to results — which is not true of the industrial-gas and equipment names sitting beside it.
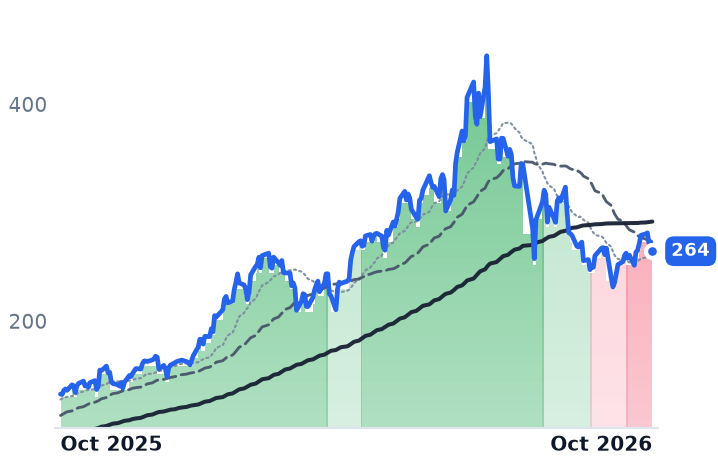
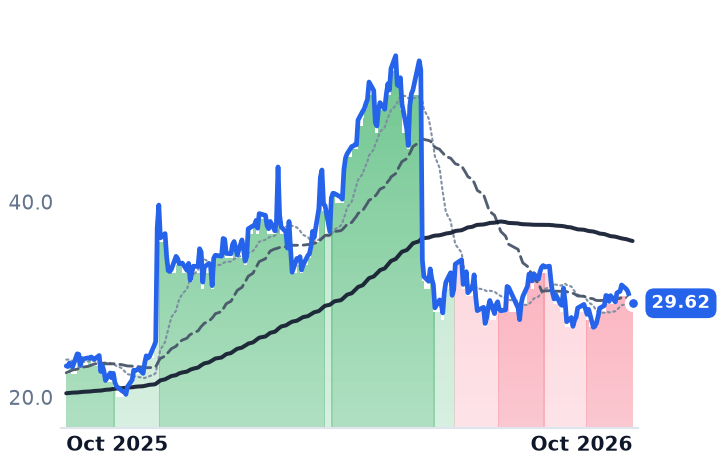
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
ESI | Element Solutions | Specialty Polymers & Materials | ⚠️ Emerging Bear | +5.8% | +45.5% |
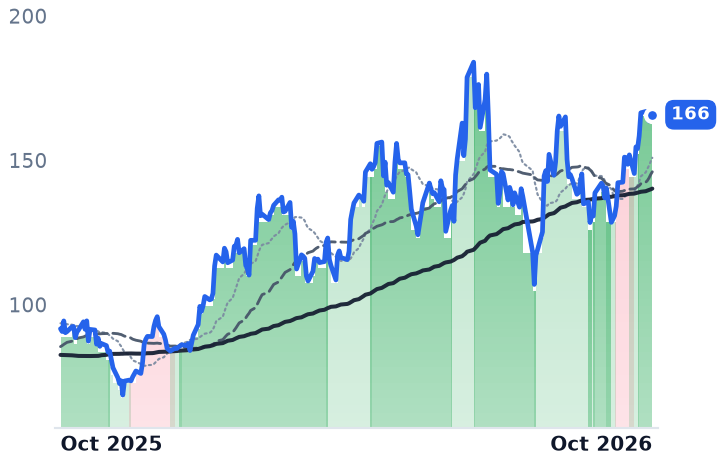
ENTG | Entegris | Semiconductor Subsystems | 🟢 Cont. Bull | +18.1% | +80.9% |
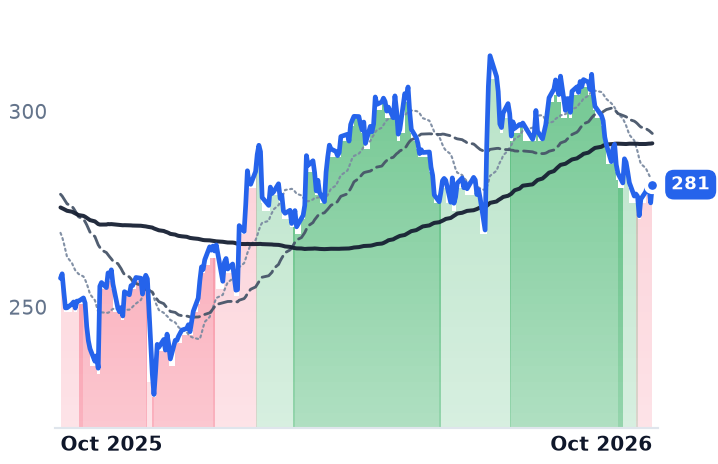
APD | Air Products and Chemicals | Industrial Gases | 🟢 Cont. Bull | −3.5% | +9.3% |
| Compared against · context, not the story | |||||
LIN | Linde | Industrial Gases | ⚠️ Emerging Bear | +3.8% | +6.7% |
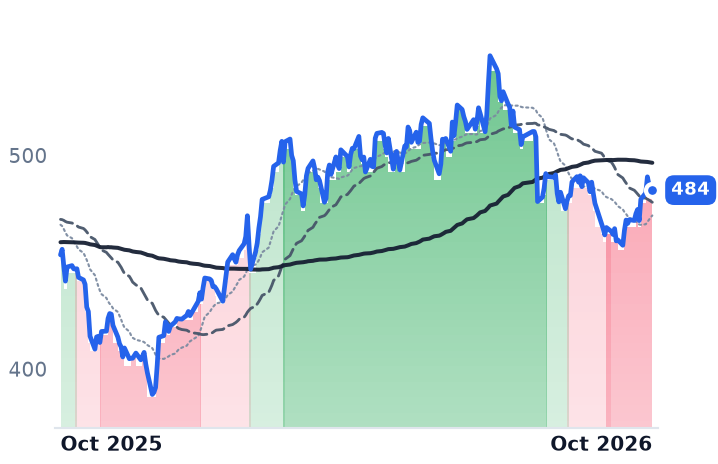
MKSI | MKS | Instrumentation & Test Equipment | ⚠️ Emerging Bear | −1.1% | +99.3% |
PLAB | Photronics | Discrete & Power | 🔴 Cont. Bear | +2.2% | +27.7% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ESI | $8.9B | 49.4x | 20.0x | 2.8x | 2.4x | 7.3x | 6.2x | 28.4x | 1.5% |
ENTG | $25.3B | 82.9x | 42.2x | 7.6x | 7.1x | 16.7x | 15.5x | 32.4x | 2.3% |
APD | $62.6B | n/m | 19.5x | 5.0x | 4.7x | 15.5x | 14.5x | 18.2x | 3.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LIN | $222.8B | 31.0x | 26.9x | 6.3x | 6.1x | 16.7x | 16.3x | 18.3x | 2.2% |
MKSI | $17.9B | 40.4x | 20.1x | 4.1x | 3.5x | 9.3x | 8.0x | 21.0x | 2.5% |
PLAB | $1.9B | 12.0x | 17.6x | 2.2x | 2.2x | 6.6x | 6.6x | 4.4x | 5.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ESI | Revenue | +49.2% | +8.7% | +5.5% |
| EPS | +22.6% | +16.4% | +15.8% | |
ENTG | Revenue | +12.4% | +13.1% | +11.0% |
| EPS | +44.3% | +29.3% | +24.4% | |
APD | Revenue | +6.0% | +5.5% | +6.2% |
| EPS | +12.2% | +7.4% | +8.2% | |
LIN | Revenue | +7.3% | +4.9% | +5.8% |
| EPS | +8.8% | +9.5% | +10.2% | |
MKSI | Revenue | +29.6% | +20.3% | +9.9% |
| EPS | +67.1% | +33.5% | +14.3% | |
PLAB | Revenue | +2.5% | +4.5% | +7.1% |
| EPS | −1.1% | +8.6% | +8.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Element Solutions agreed in July to sell itself to Solstice Advanced Materials, and its own shareholders talked the board out of the deal. The two sides mutually terminated the merger agreement on 27 August, neither owing the other a payment. The shares closed at $36.32 on 9 October, 26% below the $49.09 they reached on 22 June, before any of it began.
A specialty chemicals maker whose gross margin has fallen in each of the last five quarters, and which fell out of its uptrend in September, looks like a business losing its pricing. Its own quarterly filing describes something else. Of the 56% revenue growth Element reported for the June quarter, 15 points were organic; $107m was pass-through metal and $129m came from acquisitions. Metal bought on a customer's behalf and resold at close to no mark-up lands in revenue and in cost of sales at the same size, so it mechanically shrinks the margin percentage without touching a dollar of profit.
The premium its holders read as a markdown
Solstice Advanced Materials agreed on 6 July to pay $10.00 in cash plus 0.500 of its own shares for each Element share, implied consideration of roughly $50.10 and a premium of about 15% to the prior close, valuing the business at about $14.5bn including net debt. Element holders would have owned some 44% of the combined company.
They did not want it. The shares went from $43.64 on 2 July to $42.32 on 6 July, on 18.5m shares against roughly a sixth of that the session before, and to $38.57 on 7 July: down 11.6% in three sessions on a bid struck at a premium. Seven weeks later the agreement was gone. "At Element Solutions, we work for our shareholders and other stakeholders and have heard their feedback clearly," chief executive Benjamin Gliklich said on 27 August. "The termination of the proposed transaction is a direct response to that feedback." The next session took another 4.7% off the stock on 20.7m shares, against a normal two to four million.
The revenue line that quotes the metals market
Element sells solder and assembly chemistries, circuit-board process chemicals, die attach and wafer bumping into electronics manufacturing, and palladium and its fellow precious metals are inputs it buys and bills on. Palladium futures rose 81.5% in 2025 and traded above $1,900 an ounce in late January. That is why consensus has revenue up 49% this year while earnings per share rise about 22%, and why management warns of greater quarterly earnings variance from metal price swings alongside full-year adjusted EBITDA guidance of $690m to $710m.
Measured where the metal cannot reach, the business accelerated. Electronics organic sales grew 20% with every vertical up double digits, led by Semiconductor Solutions at 31% on thermal interface materials for artificial-intelligence graphics and central processors and on advanced packaging at Asian assembly houses; adjusted EBITDA margin excluding pass-through metals rose 120 basis points to 27.8%. The shares now change hands at 6.16x forward gross profit, against 9.43x in May.
Weakness in the shelf next door is a different thing
Element sits on a list of fab-materials suppliers whose bearish complexion is real but not shared. Entegris, which supplies filters, chemistries and wafer carriers consumed per wafer start, rose 18% in thirty days; its two segments each grew and both are guided above 10% for the September quarter, and at 16.7x trailing gross profit it has more than erased a de-rating that had it at 14.5x in August. Linde, the largest industrial-gas group, and MKS, which sells vacuum and power subsystems to chipmakers, have both rolled into downtrends — MKS down 28% in three months after a 118% twelve-month gain. Those are capital-equipment and base-volume stories.
Element's is neither. The operating numbers reported since the shares peaked are better than the ones before, and nothing in the filings marks the June quarter as the turn. What changed in July was ownership, not demand: a buyer offered equity, the holders said no, and the price has stayed where the refusal left it. The open question is the one the metals create — a quarter in which palladium falls will shrink reported revenue and lift the margin percentage, and neither will mean anything about the chemistry.
No money changed hands when the agreement ended in August. What ended with it was the outside price a buyer had put on these assets, struck before the quarter in which Element's semiconductor chemistry grew fastest, and withdrawn by the shareholders who owned it.