

Dominion Pays 100% of Its Offshore-Wind Costs Above $11.3bn, and the Estimate Is $11.7bn
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
The listed utility most often described as a claim on Northern Virginia's data centers had its reported earnings moved this year by a wind farm's cost ceiling and a regulator's order, while its share price stopped being its own in May.
Virginia's State Corporation Commission found Dominion earned 7.77% on equity across 2023-24 against a 9.70% authorized return. Its Coastal Virginia Offshore Wind estimate has since reached $11.7bn, past the $11.3bn line above which customers contribute nothing and shareholders carry every dollar. Of 53 GW of data-center capacity in various stages of contracting, roughly 12 GW sits under signed service agreements.
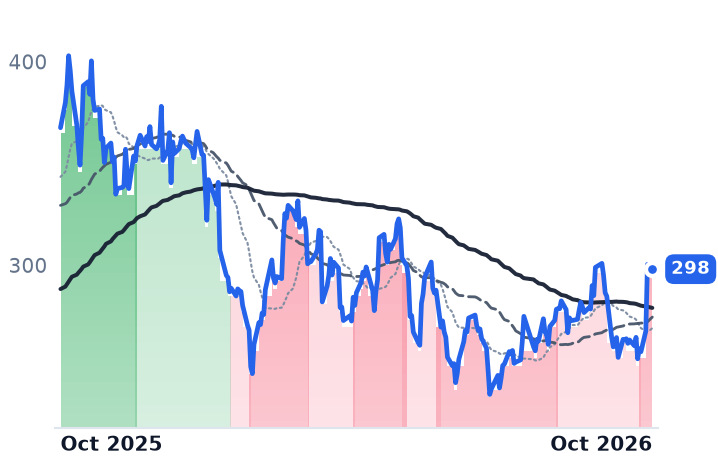
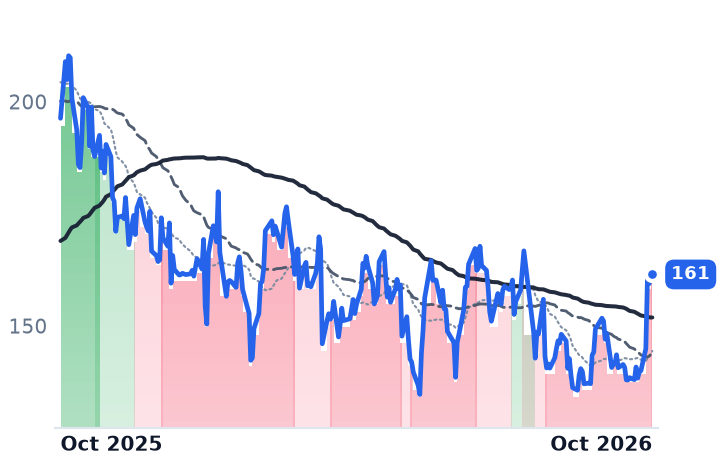
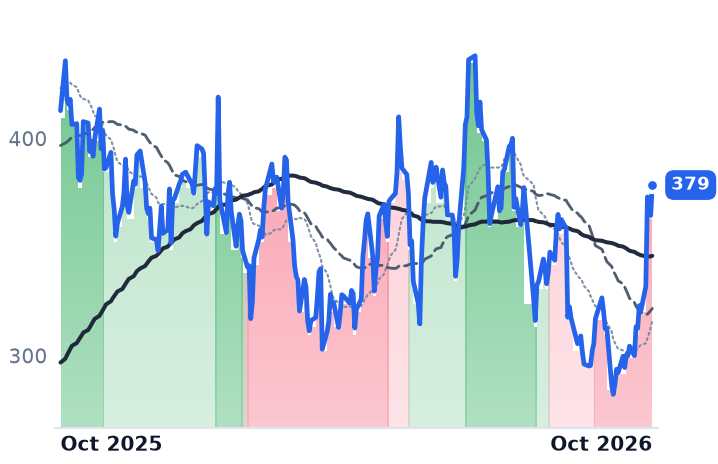
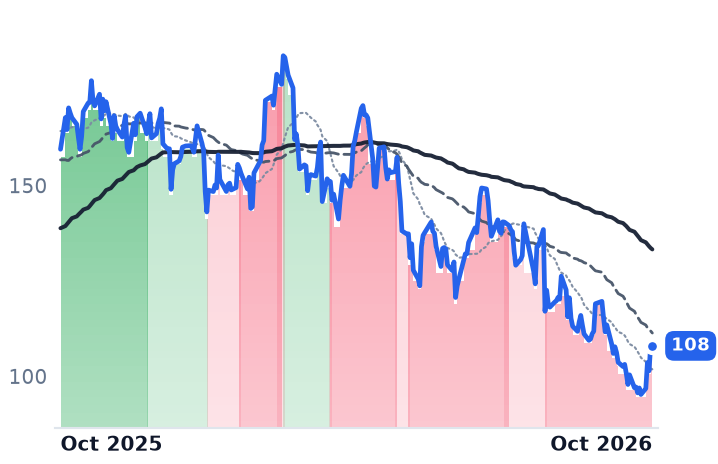
The business did not deteriorate at any of the three. Dominion's decline is the acquirer's; Entergy's growth is going into its share count; PG&E, below the book value of its own equity, is the one whose allowed return is genuinely in doubt.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
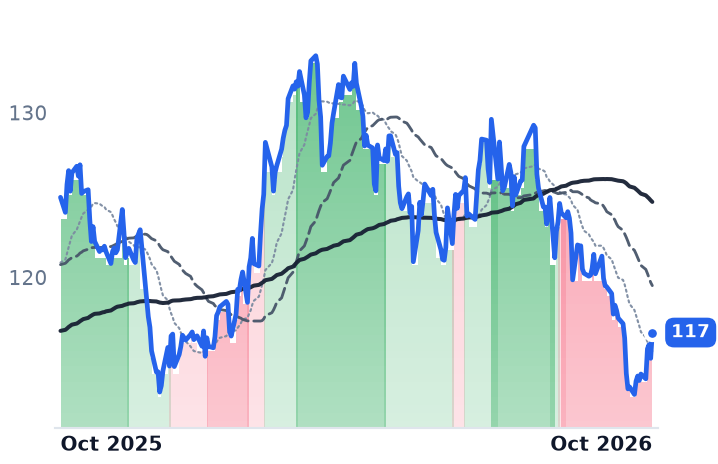
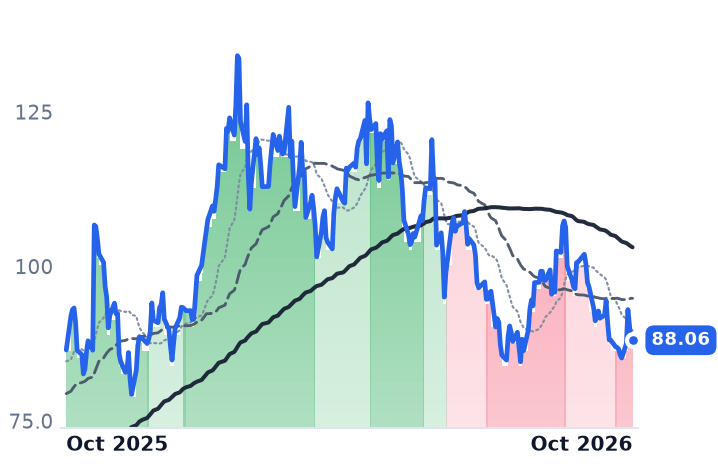
D | Dominion Energy | Vertically Integrated Utilities | 🟢 Cont. Bull | −5.1% | +3.3% |
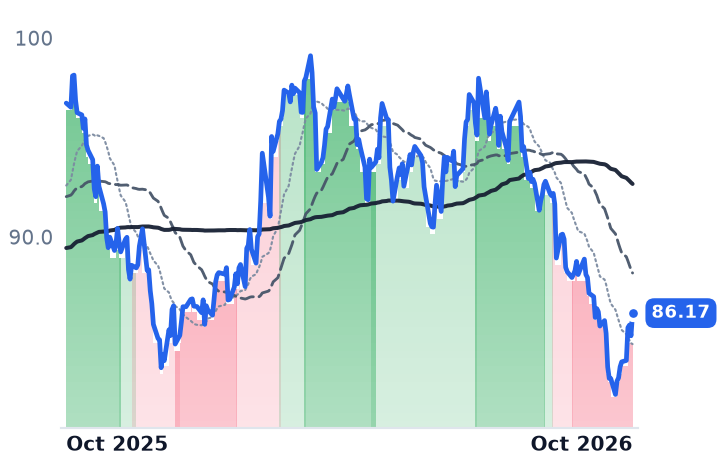
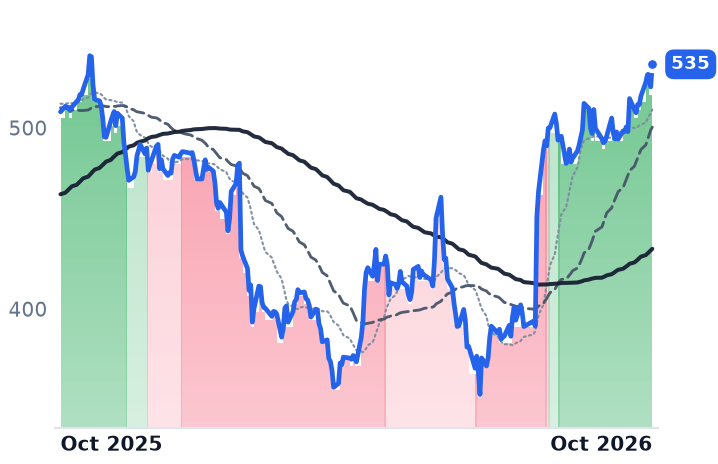
ETR | Entergy | Vertically Integrated Utilities | ⚠️ Emerging Bear | −3.3% | +9.3% |
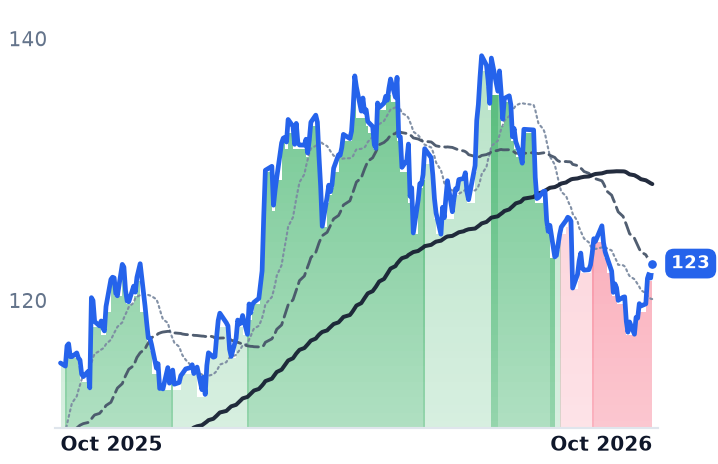
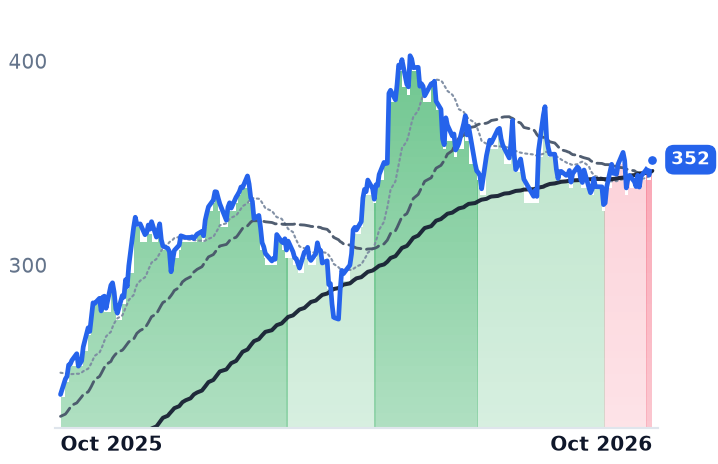
PCG | PG&E | Vertically Integrated Utilities | ⚠️ Emerging Bear | −8.1% | −16.7% |
| Compared against · context, not the story | |||||
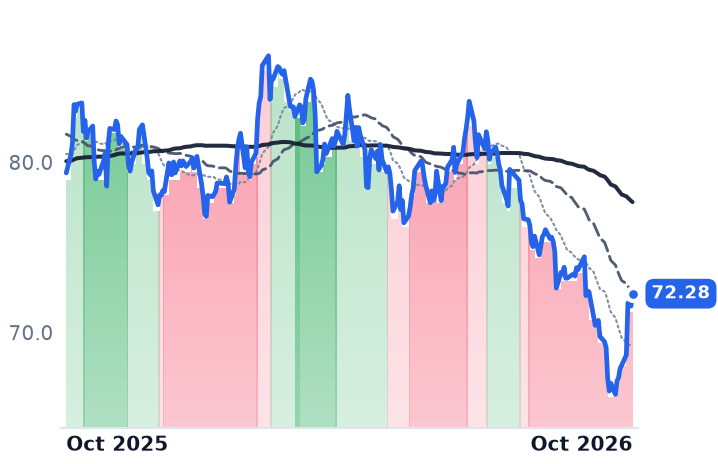
NEE | NextEra Energy | Vertically Integrated Utilities | 🔴 Cont. Bear | −6.0% | −5.9% |
CEG | Constellation Energy | Diversified Renewable Generators | 🔴 Cont. Bear | +4.0% | −18.9% |
VST | Vistra | Integrated Retail & Generation | 🔴 Cont. Bear | +9.8% | −17.7% |
TLN | Talen Energy | Wholesale Power Producers | ⚠️ Emerging Bear | +21.2% | −8.3% |
NRG | NRG Energy | Integrated Retail & Generation | 🔴 Cont. Bear | −3.3% | −32.3% |
DUK | Duke Energy | Vertically Integrated Utilities | ⚠️ Emerging Bear | −2.4% | −6.6% |
SO | The Southern | Vertically Integrated Utilities | ⚠️ Emerging Bear | −2.0% | −10.9% |
AEP | American Electric Power | Vertically Integrated Utilities | ⚠️ Emerging Bear | −0.7% | +6.6% |
PEG | Public Service Enterprise Group Incorporated | Vertically Integrated Utilities | 🔴 Cont. Bear | −0.2% | −8.9% |
CCJ | Cameco | Uranium | 🔴 Cont. Bear | −9.6% | +1.8% |
MSFT | Microsoft | Cloud Infrastructure & Platforms | 🌱 Emerging Bull | +8.6% | +5.2% |
GOOGL | Alphabet | Search & Advertising | ⚠️ Emerging Bear | +6.4% | +48.6% |
AMZN | Amazon.com | Online Marketplaces | 🟢 Cont. Bull | +4.1% | +21.3% |
META | Meta Platforms | Social Media & Messaging | 🔴 Cont. Bear | +11.5% | +2.1% |
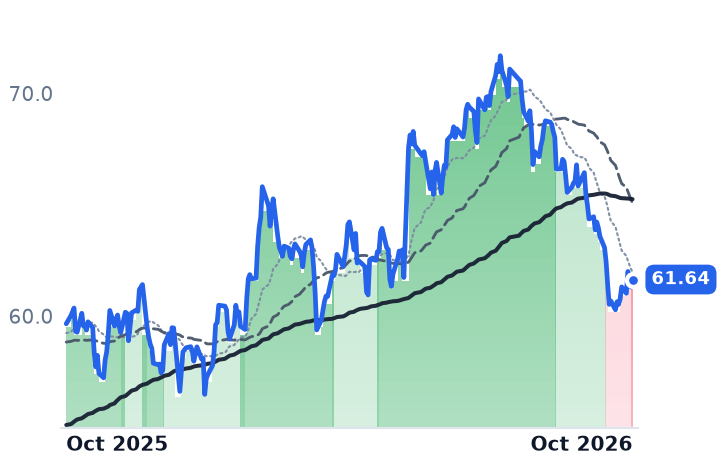
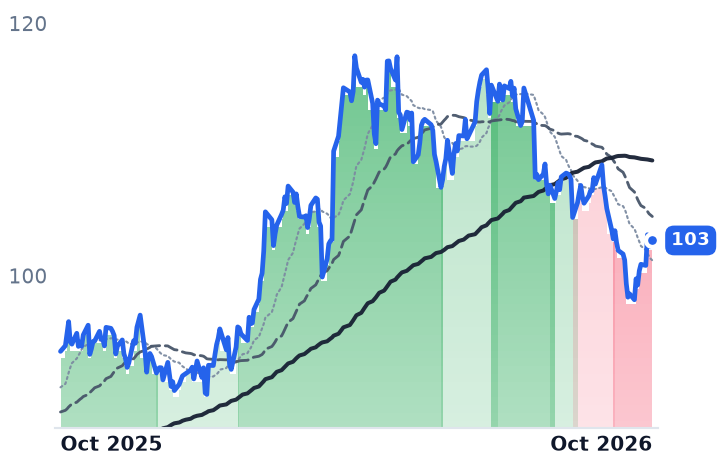
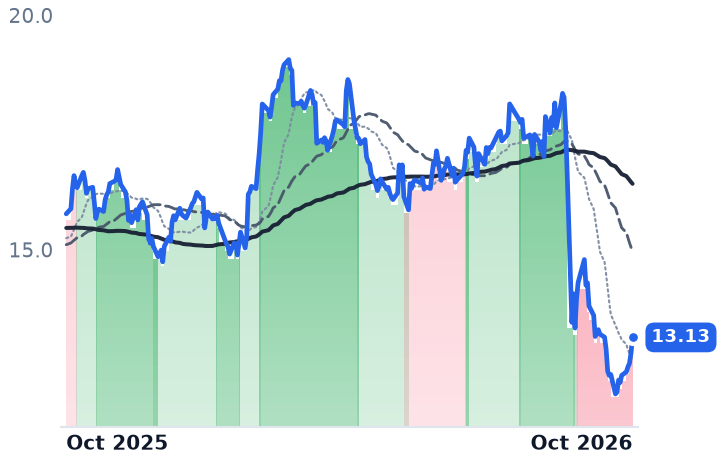
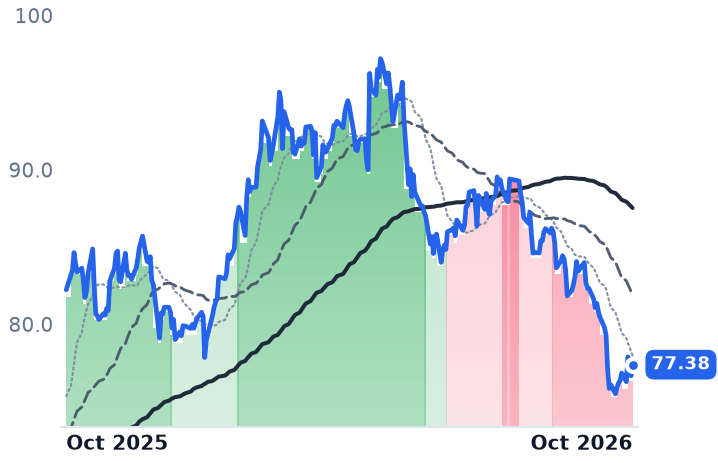
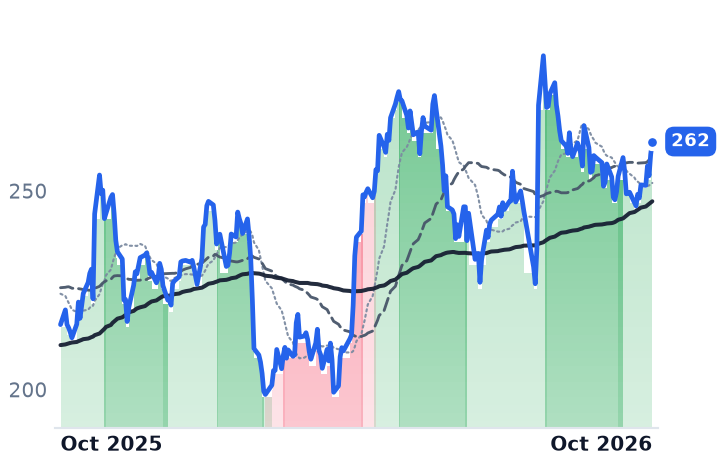
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
D | $54.2B | 21.3x | 17.2x | 3.0x | 2.9x | 6.0x | 6.0x | 14.0x | -12.6% |
ETR | $48.0B | 26.0x | 23.4x | 3.6x | 3.4x | 9.1x | 8.8x | 13.8x | -6.6% |
PCG | $35.2B | 9.5x | 7.9x | 1.4x | 1.3x | 2.4x | 2.4x | 9.0x | -12.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
NEE | $160.3B | 17.2x | 19.3x | 5.5x | 5.2x | 7.7x | 7.2x | 15.1x | -6.3% |
CEG | $94.5B | — | 21.8x | — | 2.8x | — | — | 13.9x | 0.3% |
VST | $46.7B | — | 16.4x | — | 2.1x | — | — | 10.2x | 2.9% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TLN | $13.8B | n/m | 14.8x | 3.9x | 3.1x | 8.8x | 7.0x | 29.2x | 3.7% |
NRG | $21.2B | — | 11.3x | — | 0.6x | — | — | 10.5x | 1.6% |
DUK | $93.7B | 18.1x | 17.9x | 2.8x | 2.8x | 4.1x | 4.1x | 11.4x | 1.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SO | $106.6B | 22.2x | 20.2x | 3.5x | 3.5x | 8.1x | 8.0x | 12.7x | 2.4% |
AEP | $65.1B | 20.5x | 18.7x | 2.9x | 2.8x | 5.9x | 5.7x | 13.7x | 13.8% |
PEG | $37.7B | 18.7x | 17.3x | 3.0x | 3.0x | 3.5x | 3.5x | 14.2x | 5.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CCJ | $37.1B | 148.5x | 57.8x | 15.2x | 10.7x | 55.2x | 38.7x | 61.2x | 1.0% |
MSFT | $3.8T | 28.6x | 26.1x | 11.5x | 9.8x | 17.0x | 14.4x | 19.0x | 1.7% |
GOOGL | $4.2T | 17.3x | 17.0x | 9.5x | 8.5x | 15.6x | 13.9x | 13.1x | 1.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
AMZN | $2.9T | 21.2x | 21.1x | 3.7x | 3.5x | 7.3x | 6.8x | 11.9x | -0.4% |
META | $1.5T | 21.5x | 18.2x | 6.5x | 5.8x | 7.9x | 7.1x | 14.7x | 2.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
D | Revenue | +14.4% | +6.4% | +6.1% |
| EPS | +5.1% | +6.3% | +6.9% | |
ETR | Revenue | +8.6% | +9.8% | +9.8% |
| EPS | +12.3% | +16.1% | +13.6% | |
PCG | Revenue | +2.5% | +3.9% | +3.7% |
| EPS | +10.1% | +8.7% | +8.7% | |
NEE | Revenue | +8.9% | +9.7% | +9.0% |
| EPS | +7.5% | +9.0% | +8.6% | |
CEG | Revenue | +37.2% | +2.5% | +5.3% |
| EPS | +28.9% | +10.4% | +26.4% | |
VST | Revenue | +16.6% | +10.0% | +5.1% |
| EPS | +77.0% | +19.7% | +18.7% | |
TLN | Revenue | +84.0% | +16.0% | +4.9% |
| EPS | +247.2% | +49.2% | +17.7% | |
NRG | Revenue | +17.7% | +0.8% | +3.7% |
| EPS | +14.0% | +24.5% | +15.8% | |
DUK | Revenue | +5.8% | +4.6% | +4.2% |
| EPS | +6.3% | +6.9% | +7.0% | |
SO | Revenue | +7.7% | +5.5% | +6.1% |
| EPS | +6.8% | +7.5% | +9.2% | |
AEP | Revenue | +9.4% | +5.9% | +7.6% |
| EPS | +8.0% | +7.5% | +10.6% | |
PEG | Revenue | +6.5% | +3.5% | +4.9% |
| EPS | +8.1% | +7.0% | +7.7% | |
CCJ | Revenue | +1.4% | +12.3% | +8.3% |
| EPS | +2.6% | +71.9% | +24.2% | |
MSFT | Revenue | +18.0% | +18.6% | +19.5% |
| EPS | +26.7% | +16.0% | +19.0% | |
GOOGL | Revenue | +24.3% | +22.9% | +19.1% |
| EPS | +93.4% | −26.6% | +18.2% | |
AMZN | Revenue | +15.9% | +14.6% | +16.0% |
| EPS | +76.8% | −16.1% | +30.8% | |
META | Revenue | +27.3% | +20.1% | +17.8% |
| EPS | +38.3% | +6.9% | +15.4% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Dominion Energy, the regulated utility that supplies Northern Virginia's data-center corridor along with electric and gas customers in the Carolinas, booked a $95m charge in the second quarter for offshore-wind construction costs it does not expect customers to pay. A charge like that moves reported earnings. Megawatts in a contracting pipeline do not.
That is the whole mechanism of a regulated utility dollar, and it runs against how these shares are held. A state commission sets a percentage return on the capital it has permitted the company to put in service; fuel and purchased power are passed through at cost. Load growth reaches the shareholder only once it becomes approved capital spending, and only after a rate case. Virginia has just priced that return, and the money went to a project that sits outside the usual recovery rules.
The commission sets the size of the earned dollar
The SCC found that Dominion Energy Virginia earned 7.77% on equity over the 2023-24 biennial period against a 9.70% authorization, leaving more than $350m of costs unrecovered. In its final order of 25 November 2025 the commission lifted the authorized return to 9.8%, against the 10.4% requested, and approved a base-rate increase of $565.7m for 2026 where the company had sought $822m. That is regulatory lag in arithmetic: a 193-basis-point shortfall between what the regulator allows and what the utility collected.
The company's $64.7bn 2026-2030 capital plan supports a projected Virginia rate-base growth rate of 11.9% a year, funded roughly 60% from internal cash with about a tenth each from hybrids and equity. Dominion's diluted share count rose 3.5% year on year to 882.1m in the quarter: the per-share price of that plan.
The band where customers stop paying
Under the cost-sharing settlement the Virginia commission approved in December 2022, disclosed in Dominion's annual report, the first $10.3bn of the 2.6 GW wind project is largely customer-funded, the next $1bn is split evenly, and everything from $11.3bn to $13.7bn is 100% shareholder-funded with no customer recovery at all. In July the company put the estimate at about $11.7bn, up $288m from April on network-upgrade costs, tariffs and turbine-installation revisions. Roughly $400m therefore sits in the zero-recovery band. The project is 81% complete with final turbine installation pushed to the end of 2027.
Second-quarter revenue rose 19.6% to $4.558bn while net income fell 55.3% to $340m, the gap being the charge rather than the operating business. Operating earnings came in at $0.79 a share and full-year guidance of $3.45-$3.69 was reaffirmed.
Pipeline, contract, collateral
Dominion reported 53 GW of data-center capacity in various stages of contracting, of which about 12 GW sits under signed electric service agreements, with more than 5 GW added since year-end. What converts the rest into an obligation is a tariff, not a queue: Virginia's new GS-5 class, effective 1 January 2027, applies to loads of 25 MW and up and requires a fixed 14-year contract, minimum demand charges covering 85% of contracted transmission and distribution capacity, and collateral of $1.5m per MW from customers failing credit tests.
One Dominion reactor escapes this machinery. Millstone sits outside the Virginia rate base and must be recontracted; the company bid three offers into Connecticut's solicitation for terms beginning October 2029, naming a well-capitalized counterparty such as a data-center operator as the way to underwrite relicensing. There, a power contract would land in revenue.
Why the shares fell, name by name
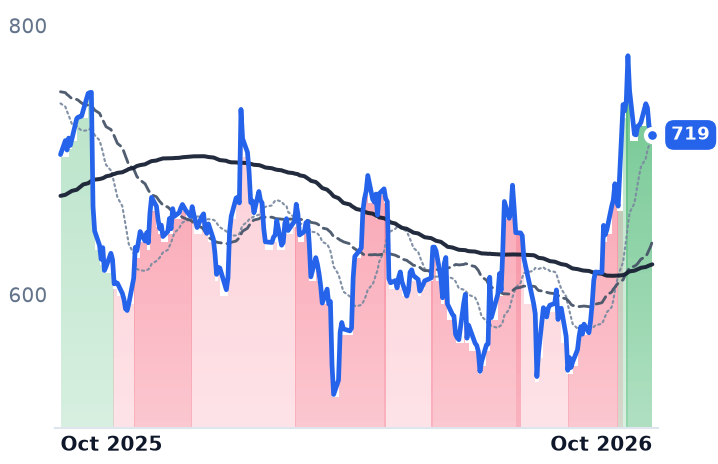
Dominion's price has not been its own since 18 May, when NextEra agreed to acquire it in an all-stock deal valued near $67bn at a fixed 0.8138 shares, unadjusted for market moves. At the 9 October close Dominion sat 2.1% under deal value, the same discount it carried a month and three months earlier, and its three-month decline of 12.1% matches NextEra's 12.0%. Virginia's commission has set public hearings and an evidentiary hearing from 17 November, with a decision expected in January, and Governor Abigail Spanberger has called herself deeply skeptical. All eight regulated names on this shelf fell over three months, a mean of 11.9%, as the utility sector sold off into a 10-year Treasury paying above 5.20% against a sector yield near 3.05%.
Entergy, which serves 3 million customers across Arkansas, Louisiana, Mississippi and Texas, shows the funding cost directly. Revenue rose 5.9% and net income 3.4%, yet diluted earnings slipped to $1.03 from $1.05 because the share count grew 4.6%; management widened the 2026 dilution drag to $0.20-$0.25 a share while raising outer-year guidance and targeting better than 8% earnings growth through 2030. Its Louisiana formula rate plan holds the allowed return at 9.7% within a 40-basis-point band, per its quarterly filing, and chief executive Drew Marsh told analysts on 29 July: "Yeah, I think that we have a long history of extending Formula Rate Plans within Louisiana. Our expectation is that we would probably be able to extend." The $12.9bn of generation for Meta's Hyperion campus went to an evidentiary hearing in early October with a December decision targeted; none of it earns until approved. At 23.4x forward against 26.0x trailing, Entergy is the dearest of these three on earnings, down from roughly 26x forward in May.
PG&E is the stress case. Operating income rose 15.2% and quarterly earnings reached $0.33 a share against $0.24, yet the stock trades at 0.85x book against Dominion's 1.87x, because California's amended wildfire bill left the liability protections out and the shares lost roughly a fifth in one session. The company cut 2027 capital spending to $11.4bn from $13.4bn and stopped giving plans beyond that year. "We have concluded that PG&E cannot simply wait for the policy framework to change," chief executive Patti Poppe told investors on 2 September. "We must take action now to sustainably serve our customers." Its reactor earns nothing extra for being a reactor: the CPUC approved about $382m of Diablo Canyon operating costs as a pass-through.
What the results account for, and what they do not
None of the three reported a worse business. Guidance was reaffirmed at Dominion, raised at Entergy, and PG&E's margins improved. The decline is a cost-of-capital event with three separate local causes: Dominion's is imported from its acquirer by contract; Entergy's growth is being absorbed by the equity that funds it; PG&E's is a question about whether it will be permitted to earn its authorized return at all. Only the first is arithmetic a reader can reproduce.
The contrast that makes the structure visible is the merchant fleet. When Constellation signed a 20-year, 890 MW agreement with Google on 6 October, the price went into its revenue line. The same demand reaching a regulated utility arrives as capital to be approved, depreciated and recovered, at a percentage a commission chooses, after a case.
Which is why the number to watch in Virginia is not a gigawatt figure. Every further dollar spent on those turbines, all the way to $13.7bn, belongs to the shareholders.