

Washington's Record Biofuel Mandate Widened the Soybean Spread That Pays ADM and Bunge
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Two crop processors have raised their 2026 earnings forecasts twice this year while their shares went the other way, and the money is arriving from a federal fuel rule. Archer-Daniels-Midland now guides to $5.15-$5.60 of adjusted earnings per share, up from $3.60-$4.25 in January; Bunge has lifted its range to $9.25-$9.75.
Neither is paid a crop price. Both earn a hedged spread between what a soybean costs and what the meal and oil fetch, and that spread widened after the Environmental Protection Agency set the highest renewable fuel volumes in the program's history.
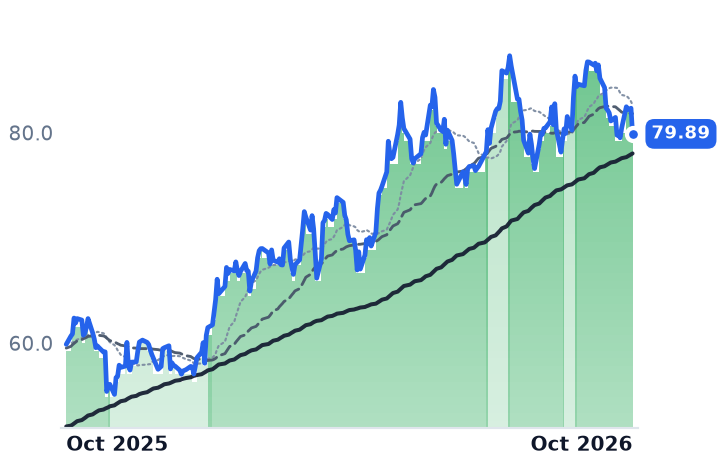
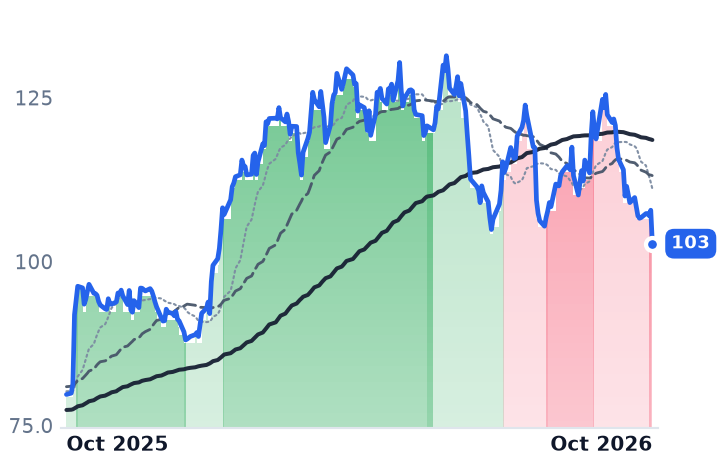
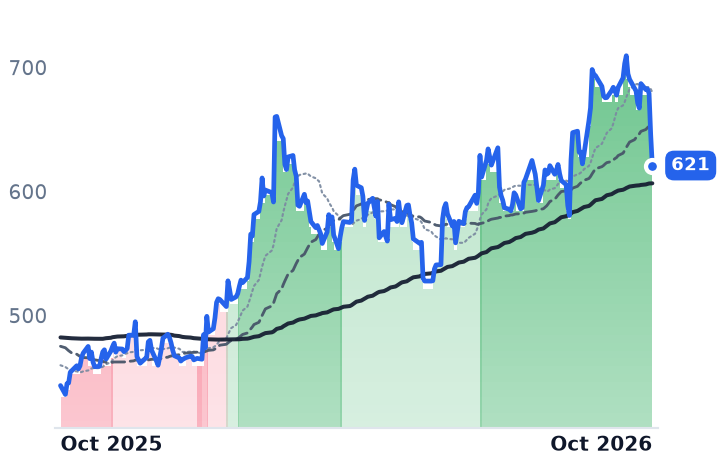
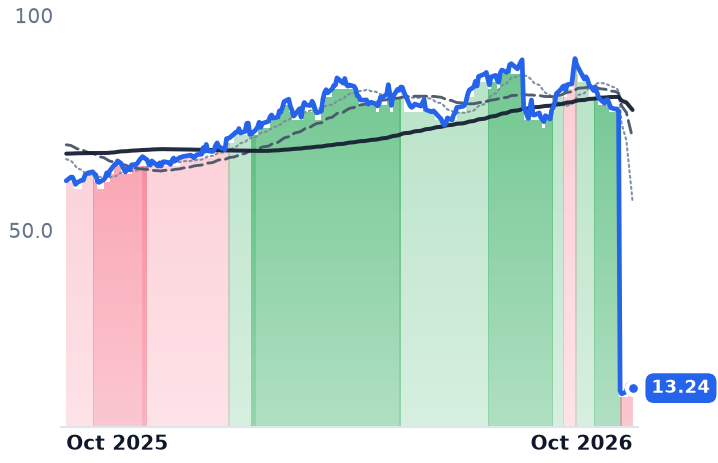
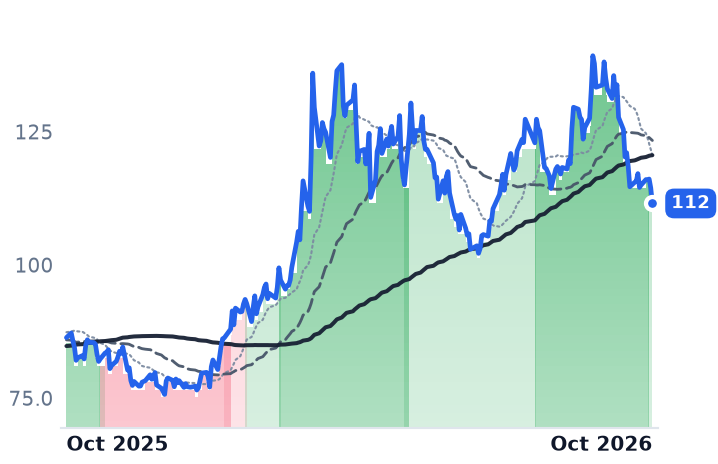
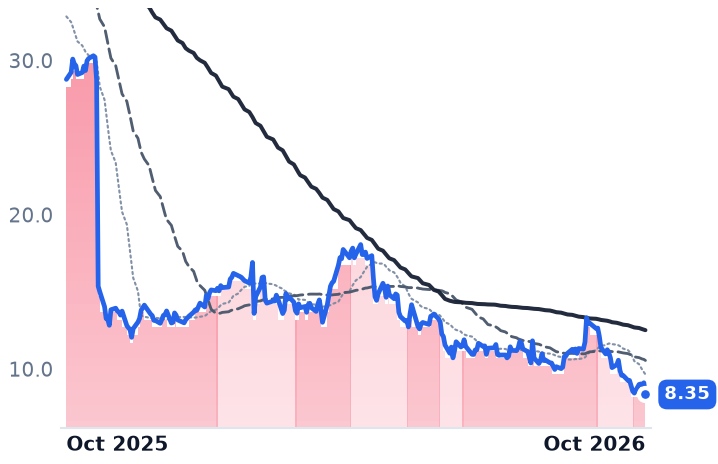
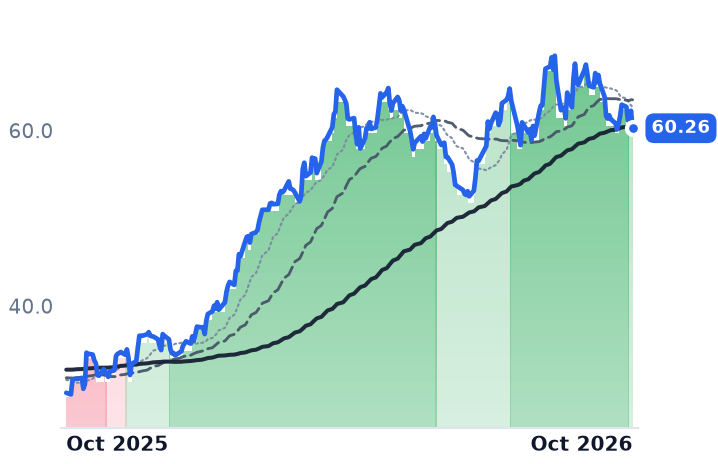
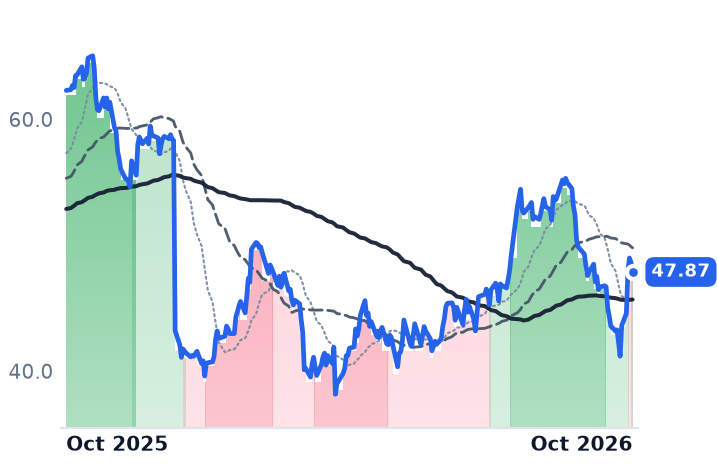
Bunge is the more exposed of the two: processing delivered 88% of its second-quarter segment earnings, and it trades at 10.9x forward earnings. ADM has held its uptrend. What a rule gives, an October rulemaking on refinery exemptions can take back.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
ADM | Archer-Daniels-Midland | Commodity Trading & Processing | 🟢 Cont. Bull | −7.9% | +33.4% |
BG | Bunge Global | Commodity Trading & Processing | 🔴 Cont. Bear | −18.1% | +28.9% |
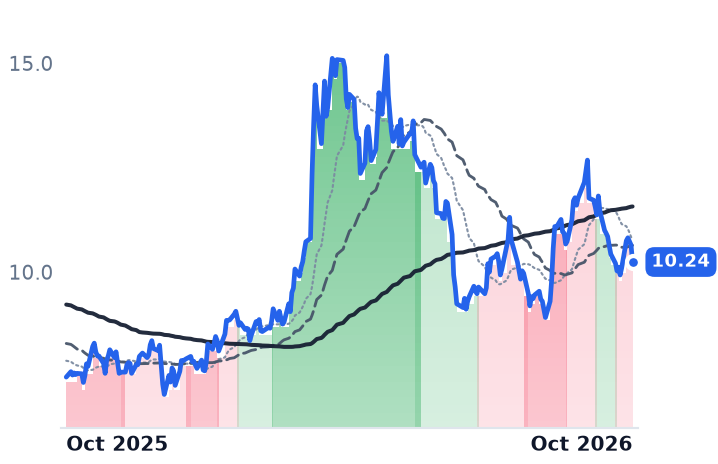
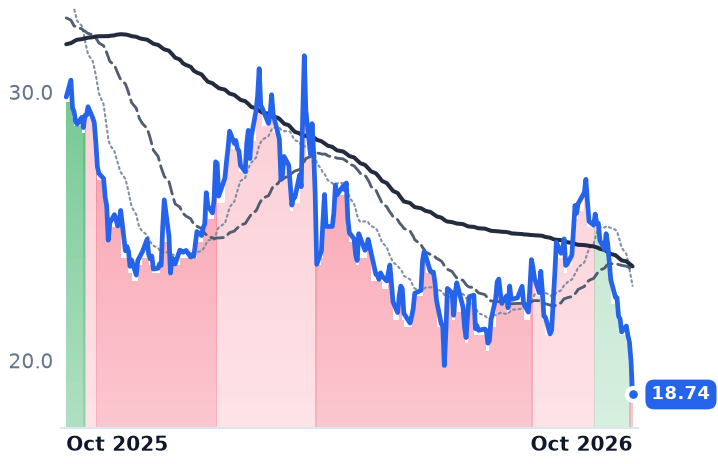
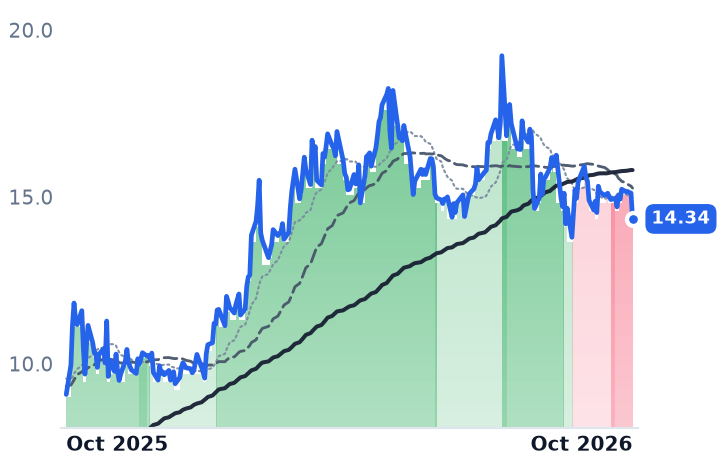
AGRO | Adecoagro | Commodity Trading & Processing | 🔴 Cont. Bear | −19.2% | +36.8% |
| Compared against · context, not the story | |||||
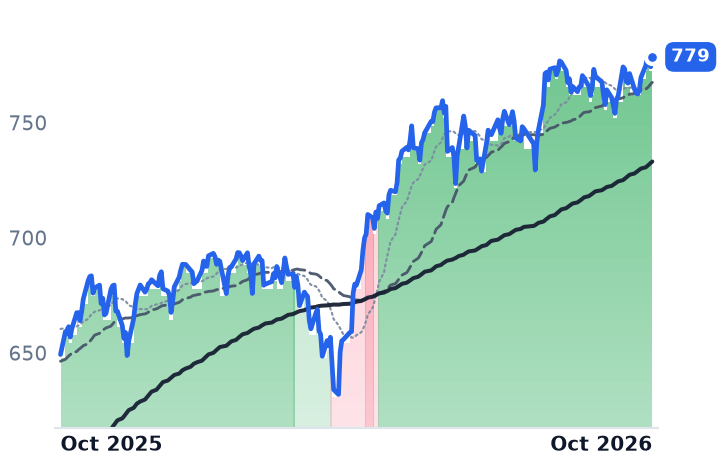
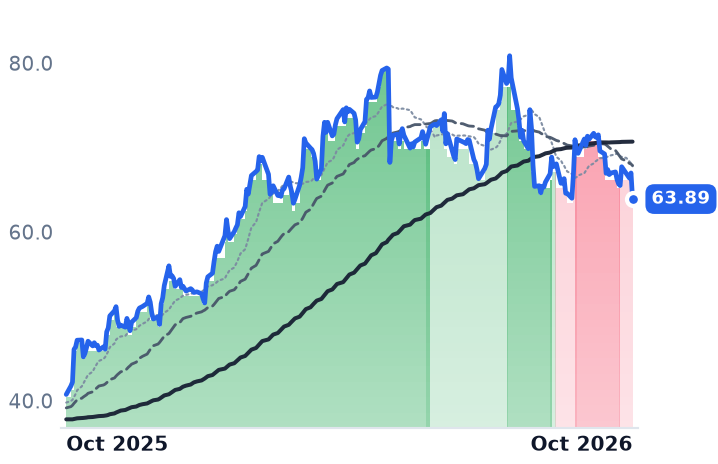
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | +2.7% | +19.9% |
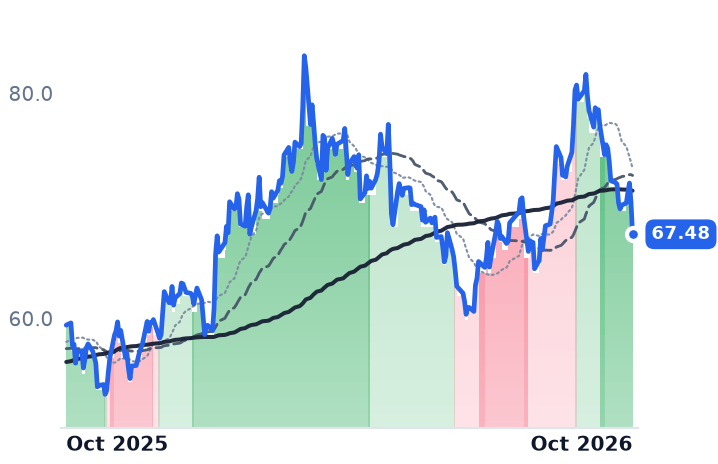
DE | Deere | Agricultural Tractors & Equipment | 🟢 Cont. Bull | −8.1% | +40.0% |
CTVA | Corteva | Integrated Seeds & Crop Protection | 🟢 Cont. Bull | −84.5% | −78.5% |
MOS | The Mosaic | Phosphate & Potash | 🔴 Cont. Bear | −27.7% | −37.2% |
NTR | Nutrien | Fertilizer Distribution & Retail | 🟢 Cont. Bull | −15.4% | +13.6% |
CF | CF Industries | Nitrogen Fertilizers | 🟢 Cont. Bull | −17.4% | +29.2% |
FMC | FMC | Crop Protection Chemicals | 🔴 Cont. Bear | −31.2% | −71.0% |
GPRE | Green Plains | Biofuels & Renewables | ⚠️ Emerging Bear | −7.4% | +57.9% |
ANDE | The Andersons | Agricultural Commodities | ⚠️ Emerging Bear | −10.4% | +56.8% |
DAR | Darling Ingredients | Specialty Ingredients & Co-Products | 🟢 Cont. Bull | −9.2% | +100.2% |
LW | Lamb Weston | Frozen & Prepared Foods | 🟢 Cont. Bull | +0.6% | −23.2% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
ADM | $38.5B | 21.9x | 14.6x | 0.5x | 0.4x | 6.8x | 6.4x | 10.0x | 4.4% |
BG | $19.7B | 19.9x | 10.9x | 0.2x | 0.2x | 4.3x | 4.3x | 12.0x | -3.6% |
AGRO | $5.8B | 157.5x | 6.8x | 3.5x | 2.6x | 11.7x | 8.7x | 12.8x | 0.8% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
SPY | $773.0B | — | — | — | — | — | — | — | — |
DE | $151.8B | 31.5x | 31.4x | 3.3x | 3.7x | 9.3x | 10.3x | 18.0x | 2.4% |
CTVA | $55.0B | 47.6x | 22.0x | 3.1x | 3.0x | 6.6x | 6.4x | 16.5x | 3.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MOS | $6.9B | 9.5x | 18.4x | 0.6x | 0.5x | 4.1x | 3.9x | 4.0x | -7.1% |
NTR | $37.0B | 15.6x | 15.6x | 1.3x | 1.3x | 4.2x | 4.3x | 7.7x | 5.7% |
CF | $19.6B | 9.4x | 8.5x | 2.5x | 2.4x | 6.0x | 5.7x | 5.3x | 9.7% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
FMC | $1.3B | n/m | 7.7x | 0.4x | 0.4x | 1.1x | 1.0x | n/m | 12.8% |
GPRE | $1.2B | n/m | 13.9x | 0.6x | 0.5x | 10.6x | 8.9x | 10.3x | 7.5% |
ANDE | $2.4B | 18.9x | 13.5x | 0.2x | 0.2x | 3.1x | 2.9x | 9.7x | -4.3% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DAR | $10.7B | 17.9x | 10.6x | 1.6x | 1.6x | 6.5x | 6.3x | 9.9x | 8.2% |
LW | $6.5B | 22.5x | 15.6x | 1.0x | 1.0x | 4.8x | 4.9x | 10.6x | 9.8% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
ADM | Revenue | +5.2% | +5.7% | +5.3% |
| EPS | +61.7% | +7.7% | −0.9% | |
BG | Revenue | +35.6% | +2.8% | −0.3% |
| EPS | +28.3% | +17.4% | +8.9% | |
AGRO | Revenue | +62.6% | +3.1% | +0.5% |
| EPS | +467.1% | −21.4% | −1.4% | |
DE | Revenue | +7.8% | +9.5% | +9.7% |
| EPS | −3.0% | +28.7% | +22.8% | |
CTVA | Revenue | +3.3% | +3.4% | +2.7% |
| EPS | +11.9% | +10.2% | +11.5% | |
MOS | Revenue | +7.5% | −0.7% | −1.2% |
| EPS | −53.0% | +65.0% | +1.6% | |
NTR | Revenue | +5.2% | −1.3% | −1.1% |
| EPS | +6.8% | −0.3% | −8.0% | |
CF | Revenue | +16.5% | −10.6% | −5.0% |
| EPS | +68.3% | −27.7% | −20.0% | |
FMC | Revenue | −8.7% | +4.3% | +4.2% |
| EPS | −55.0% | +24.4% | +22.1% | |
GPRE | Revenue | +3.4% | +5.4% | +47.9% |
| EPS | −162.6% | −4.9% | +146.0% | |
ANDE | Revenue | −0.1% | +3.3% | — |
| EPS | +122.4% | +12.4% | — | |
DAR | Revenue | +3.6% | +14.5% | +4.1% |
| EPS | −68.8% | +1308.0% | −7.4% | |
LW | Revenue | +2.7% | −0.4% | +1.6% |
| EPS | −10.9% | +9.0% | +11.5% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Archer-Daniels-Midland, which buys oilseeds, corn and wheat and sells the oil, meal, sweeteners, starches and ethanol made from them, has raised its 2026 profit forecast twice this year, and the cause is a federal fuel rule rather than anything a food customer ordered. The company entered the year guiding $3.60 to $4.25 of adjusted earnings per share, lifted the range in May after the Environmental Protection Agency finalized renewable fuel volumes, and in August took it to $5.15 to $5.60, a 24% increase at the midpoint in one quarter.
The agricultural complex is nonetheless traded as though crop prices were these companies' revenue. On 9 October a Department of Agriculture report raising corn yield and production forecasts plunged corn futures and sold the sector: Corteva fell 6.6%, Mosaic 6.2%, Bunge 4.7% and ADM 3.0%, on a day an S&P 500 tracking fund rose 0.55%. What a processor actually collects is the spread between the bean and the products made from it, hedged on the futures board weeks before the plant runs.
The quarter's profit was set before the plants ran
ADM's crushing business lost $79m at the operating line in the first quarter of 2026 against a $47m profit a year earlier. The quarter carried roughly $275m of net negative mark-to-market and timing charges, about 70% of it in crushing, booked because the commodity environment strengthened on clarity about US biofuels policy. One quarter later the same subsegment earned $363m, helped by about $100m of net positive timing — a $442m swing while revenue moved roughly 11% sequentially. Second-quarter group revenue of $22.68bn was up 7.0% year on year; operating income rose 796% to $896m.
Hedging is why the two quarters look unrelated. On the 4 August call Chief Executive Juan Luciano said North American crushing was about 90% covered for the third quarter and 30% for the fourth, with global coverage near 70% for the third.
Most of a quarter's margin is bought before the quarter exists.
Washington buys the oil
The EPA's Set 2 rule put 2026 and 2027 volumes at the highest levels in the program's history, with the agency estimating that biodiesel and renewable diesel output must rise more than 60% from 2025. Soybean oil is more than a third of the feedstock those US plants consume, and domestic renewable diesel capacity has gone from 791 million gallons a year in 2021 to about 4,580 million now. ADM's oilseeds segment profit rose 129% in the second quarter, which the company credited to demand created by the obligation and higher global energy prices, with crush volumes up nearly 5%.
The corn slab answers to different arithmetic. Carbohydrate Solutions, ADM's sweetener, starch and ethanol business, earned $411m, up 22%, with ethanol profit up 158% to $85m — and ADM credited lower US corn prices for giving ethanol an edge over competing blendstocks. The report that sold the shares on 9 October cheapens that input.
Bunge is the more processing-levered of the two
Bunge, which absorbed Viterra's grain handling and export network in July 2025, is commonly read as the diversified one. Its second quarter says otherwise: soybean and softseed processing delivered $700m of $796m of adjusted segment earnings before interest and tax, or 88%, against $67m from grain merchandising and milling. The Viterra cost-synergy target went to about $350m from $250m, adjusted leverage stood at 1.9x, and full-year guidance moved to $9.25 to $9.75. "Our team delivered another strong quarter, navigating a complex global environment with agility, focus and disciplined execution," Chief Executive Greg Heckman said on 29 July.
The shares have fallen 18.1% from their 10 September close, which is also the day UBS cut its target to $115 from $145 on valuation while keeping a buy rating. Bunge now trades at 10.9x forward earnings against 19.9x trailing, a wider gap than ADM's, and trailing free cash flow is negative 3.6% of market value on the working capital Viterra brought with it. ADM has held its uptrend through the period, is 31.3% higher over twelve months, and sits at 14.6x forward earnings against 21.9x trailing.
What an October rulemaking decides
The results do not explain the fall; the fragility of their cause does. On 1 September the EPA granted 29 small refinery exemptions covering 1.76 billion renewable credits, some 770 million more than it had projected, and pledged to propose reallocating all of it into the 2026 and 2027 obligations before the end of October. The notice itself omitted the reallocation, and no rule had appeared by 9 October. On the American Soybean Association's arithmetic, roughly 500 million gallons of biomass-based diesel demand hangs on it.
A spread this wide also calls out supply. 114 million bushels of new US crush capacity is slated for 2026 after 75 million in 2025, and ADM's own four-plant brownfield program adds about 700,000 tonnes of annual capacity between mid-2028 and early 2029.
Luciano called that program a "phased approach to allow for offramps." It is an odd way to describe building into the best margins the industry has seen, and an honest one: the demand was legislated, and what a rule gives it can withdraw at the next comment period.