

Service and Financing, Not New Cars, Are Where a Franchised Dealer's Gross Profit Lives
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
A car retailer's profit has moved off the vehicle and onto the loans, fees and repair bays attached to it — and in three September weeks the Federal Trade Commission, the Federal Reserve and Morgan Stanley all took aim at that back end. The six listed franchise groups fell an equal-weighted 19% in a month.
The trigger was AutoNation's own guidance that gross profit on each new vehicle would fall about 10% in the third quarter on model-year changeover. The business record splits. AutoNation's revenue has declined year over year for three straight quarters and its operating margin has halved since 2022, to 4.74%. Lithia's June quarter was a record, with new-vehicle gross profit per unit flat for a third quarter at $2,718 and its captive lender's income more than doubling. Penske, the shelf's only twelve-month gainer, carries the highest forward multiple of the three at 14.7x.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
LAD | Lithia Motors | Traditional Dealership Groups | 🟢 Cont. Bull | −20.0% | −2.1% |
AN | AutoNation | Traditional Dealership Groups | 🔴 Cont. Bear | −24.0% | −26.1% |
PAG | Penske Automotive | Traditional Dealership Groups | 🟢 Cont. Bull | −9.5% | +20.5% |
| Compared against · context, not the story | |||||
GPI | Group 1 Automotive | Traditional Dealership Groups | 🔴 Cont. Bear | −17.4% | −44.3% |
ABG | Asbury Automotive | Traditional Dealership Groups | 🔴 Cont. Bear | −19.9% | −28.7% |
SAH | Sonic Automotive | Traditional Dealership Groups | 🌱 Emerging Bull | −19.4% | −13.3% |
CVNA | Carvana | E-Commerce Platforms | ⚠️ Emerging Bear | −9.7% | −3.2% |
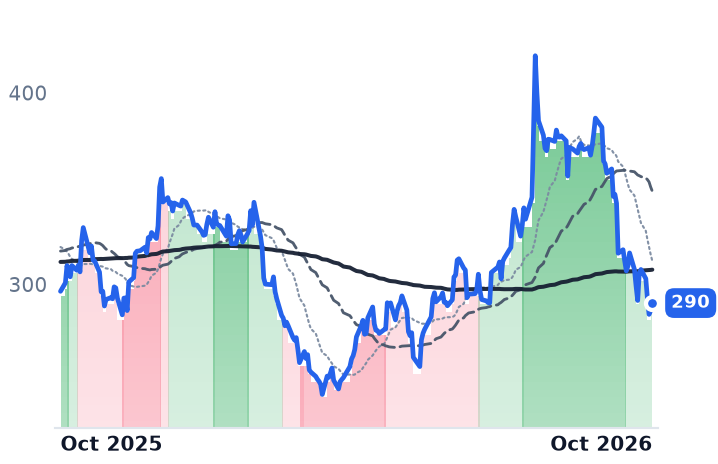
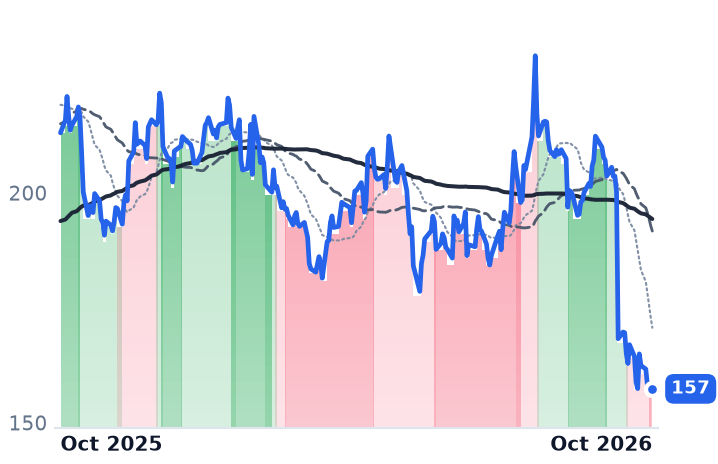
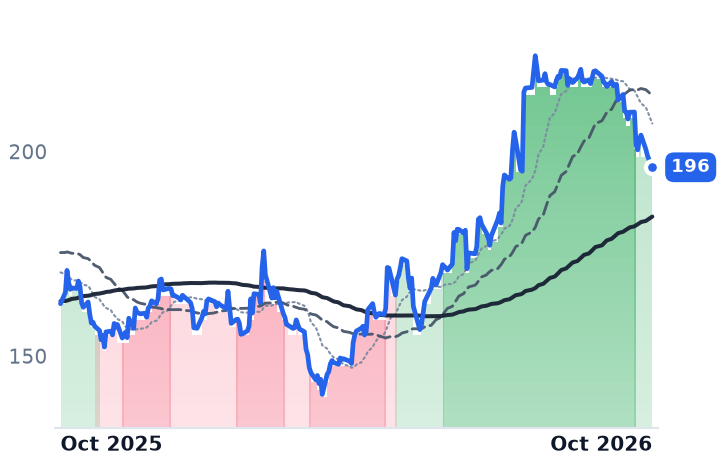
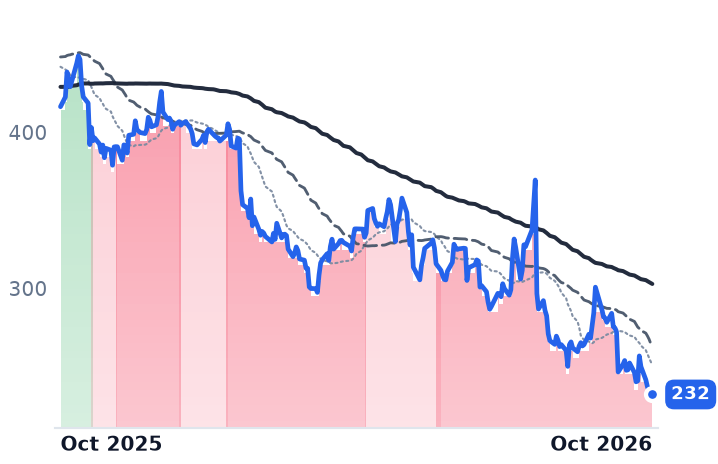
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
LAD | $6.4B | 9.6x | 8.0x | 0.2x | 0.2x | 1.5x | 1.5x | 15.6x | -7.9% |
AN | $5.3B | 7.1x | 7.4x | 0.2x | 0.2x | 1.1x | 1.1x | 10.1x | 0.2% |
PAG | $12.9B | 14.4x | 14.7x | 0.4x | 0.4x | 2.4x | 2.4x | 12.8x | 4.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
GPI | $3.6B | 12.5x | 7.7x | 0.2x | 0.2x | 1.0x | 1.0x | 11.4x | 3.9% |
ABG | $4.0B | 8.1x | 8.2x | 0.2x | 0.2x | 1.3x | 1.3x | 8.9x | 12.3% |
SAH | $2.7B | 12.7x | 11.7x | 0.2x | 0.2x | 1.1x | 1.1x | 11.0x | -2.0% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CVNA | $72.8B | 30.0x | 44.4x | 3.2x | 2.6x | 16.2x | 13.1x | n/m | 1.0% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
LAD | Revenue | +1.6% | +3.5% | +5.4% |
| EPS | +2.4% | +16.0% | +13.7% | |
AN | Revenue | −0.8% | +3.1% | +2.0% |
| EPS | +6.7% | +13.2% | +11.8% | |
PAG | Revenue | +6.9% | +2.5% | +2.1% |
| EPS | −0.9% | +5.2% | +6.9% | |
GPI | Revenue | −1.4% | +5.4% | +3.6% |
| EPS | −5.3% | +12.2% | +13.9% | |
ABG | Revenue | −2.2% | +4.2% | +7.0% |
| EPS | −5.9% | +14.9% | +9.5% | |
SAH | Revenue | +3.5% | +4.5% | +5.4% |
| EPS | +5.2% | +10.5% | +8.8% | |
CVNA | Revenue | +38.8% | +25.6% | +20.9% |
| EPS | +50.1% | +37.0% | +33.9% |
Forward fiscal years only. Blank means no analyst coverage for that year.
AutoNation's finance chief spent part of 17 September explaining model-year changeover to investors at Morgan Stanley's Laguna conference. Gross profit on each new vehicle would land about 10% below the second quarter's, he said, with parts-and-service growth moderating as customers defer elective work and finance income softer; the company was "having to meet the customer where they are and give a little bit more on price." The next morning every listed franchised car dealer in America opened lower, and AutoNation closed below its prior 52-week low.
The warning was read as a verdict on car demand. What it described was the condition of three profit lines that have quietly become the business: the finance-and-insurance desk, the service drive, and the loan book the dealer now funds itself.
The new car is the small line
Lithia Motors, which runs 467 stores selling new and used vehicles plus financing, warranties, repair and parts under the Lithia and Driveway brands, shows the arithmetic plainly. In its June quarter, new-vehicle sales produced $4,829.2m of revenue and $284.0m of gross profit, a margin of 5.9%. The finance desk booked $366.4m of revenue, and because commissions on loans, warranties and insurance contracts carry essentially no cost of goods, all $366.4m of it was gross profit. Parts and service produced $633.0m, 2.2 times the new-vehicle line.
That shape holds across the industry, and it is moving the wrong way at the front. New-vehicle gross profit per unit at the public groups fell 15.8% year over year to $2,764 in the second quarter, while used slipped only 2.0%. Finance and insurance has been the defended dollar, at $2,569 per vehicle retailed, more than 40% above 2019's $1,798. Service is no longer outrunning inflation: same-store fixed-operations gross profit grew 2.3% against June consumer prices up 3.5%.
Inventory is not the culprit. Cox Automotive put new-vehicle days' supply at 76 in late September, down 1% from a year earlier, with incentives at 6.5% of average transaction price and the full-year sales forecast raised to 16.1 million units.
Three weeks aimed at the back end
Two days before AutoNation spoke, the Federal Trade Commission published price-transparency FAQs for auto dealers: the advertised price must be what any consumer can walk in and pay, excluding only charges government requires, so a $40,000 vehicle carrying a dealer document fee of $85 must be advertised at $40,085. The agency had already sent warning letters to 97 dealership groups in March.
On 16 September the Federal Open Market Committee raised its target range a quarter point to 3.75%-4.00%, the first increase since 2023. Floor-plan borrowing, the credit line that carries unsold inventory, reprices with it: Lithia's floor-plan interest expense rose $14.7m in the June quarter, while Penske's same-store equivalent fell 9.8%.
Then on 5 October Morgan Stanley's Daniela Haigian cut AutoNation to Equal-weight with a $175 target, from $250, and Group 1 Automotive to Underweight, trimming implied multiples across the franchise dealers by 1.2 turns. Her argument was the back end again: fee disclosure plus AI shopping agents that make cross-retailer price comparison frictionless, with Carvana scored as the best-positioned name in auto retail after a record quarter of roughly 197,000 retail units.
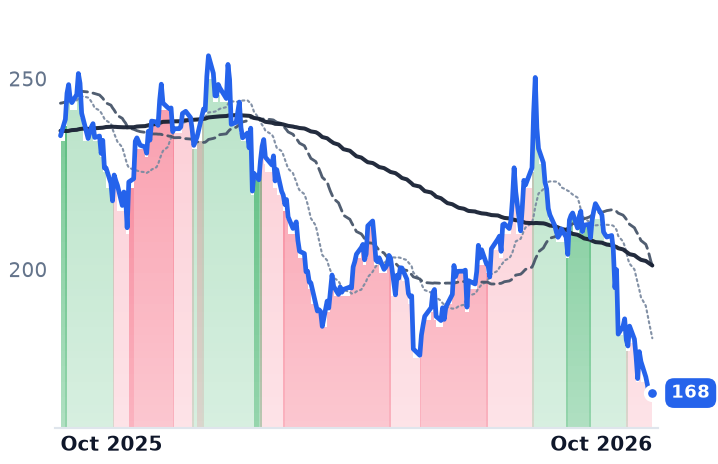
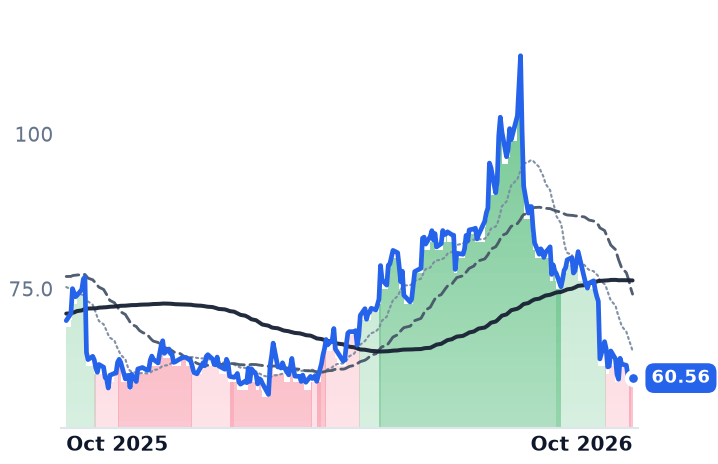
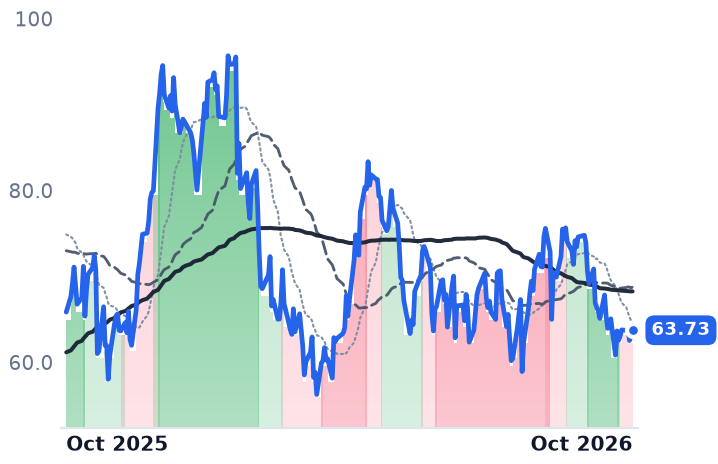
From 9 September to 9 October the six franchise groups fell an equal-weighted 19%, AutoNation worst at 24% and Penske least at 10%. Four of the six now sit in established downtrends; only Lithia and Penske still hold mild uptrends.
One guide-down, one record quarter
AutoNation fell on its own numbers. Revenue has declined year over year for three straight quarters, operating margin has gone from 7.50% in 2022 to 4.74% in 2025, and 2025 net income fell 6.2% while earnings per share rose, because diluted shares have dropped from 75.0m in 2021 to 33.8m. Its captive lender, at a $2.7bn portfolio, earned $20.1m in the first half against a $39.6m provision for credit losses. At 7.4x forward earnings against 7.1x trailing, the multiple prices a flat-to-down year.
Lithia's quarter went the other way. Revenue rose 2.2% to $9.8bn, new-vehicle gross per unit held at $2,718 for a third consecutive quarter, used retail gross per unit gained $339 sequentially, and Driveway Finance originated a record $884m. "Financing Operations delivered 80% income growth, with expanding margins and increasing penetration," chief executive Bryan DeBoer told investors on 29 July. The cost of that engine sits two filings down: in the March quarter, $21.0m of the credit provision was net charge-offs against $5.4m from portfolio growth, and funding the loan book leaves trailing free cash flow at minus 7.9% of market value even on a 9.6x trailing multiple. Forward, Lithia trades at 8.1x.
Penske held up because a quarter of it is not a car dealership. Premium brands were 71% of retail automotive franchised revenue in the first half, and equity earnings of $57.4m from Penske Transportation Solutions exceeded the entire commercial-truck segment's $47.2m of pretax income and equalled 22% of group net income. At 14.7x forward against 14.4x trailing, Penske carries the highest multiple of the three and the flattest consensus earnings path.
What the quarters have to settle
The selloff is a repricing of the fee, finance and service dollar, and only one of the three protagonists has reported deterioration in it. AutoNation guided its own front end down and has the contracting revenue line to match. Lithia's per-unit economics stopped falling two quarters ago, which leaves its 20% monthly decline resting on what a regulator's guidance and a downgrade say about lines that are still earning. Penske's defense is brand mix and a freight stake, neither of which a car buyer explains.
Lithia reports on 21 October, AutoNation on 22 October and Penske on 28 October. Three figures in those releases do the work the revenue line cannot: gross profit per unit by line, the captive lenders' charge-offs, and what the service bays grew in a quarter when customers are being told to defer.
A dealer can live with a thin margin on the metal. What it has never had to price is a customer who sees the whole number before walking through the door.