

Gathering Maintenance Will Push DT Midstream's Third-Quarter Profit Below the Second's
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
A gas-infrastructure company whose contracts are supposed to make quarters boring just told investors the next one steps down, and four banks trimmed their targets without touching a rating. The cause sits in the one segment nobody buys the shelf for.
Roughly 70% of DT Midstream's revenue comes from the Pipeline segment on long-term take-or-pay terms with minimum volume commitments. Gathering is paid for molecules actually handled, and planned maintenance plus Northeast producer timing is where revenue growth halved, from +27.3% in the December 2025 quarter to +11.0% in June. Consensus now carries 2026 operating profit of $788.1m, about 0.2% above 2025.
Kinder Morgan and Williams both accelerated last quarter and fell anyway. DT Midstream is the one of the three whose de-rating shows up in its own income statement.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
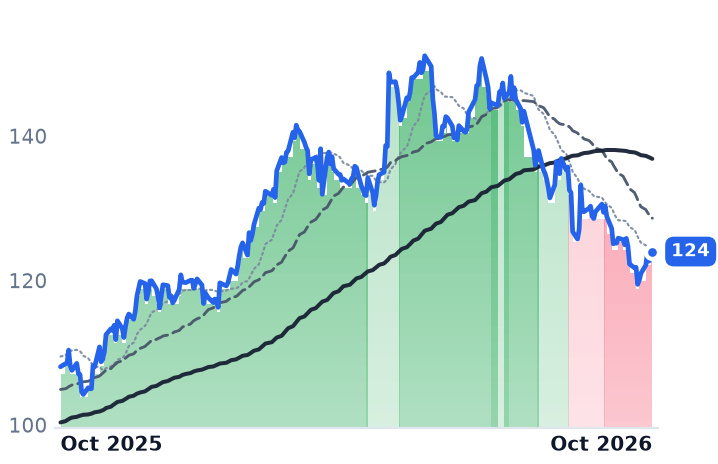
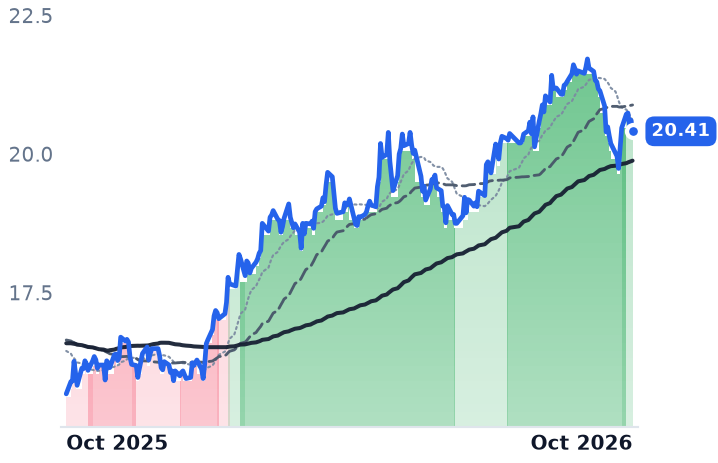
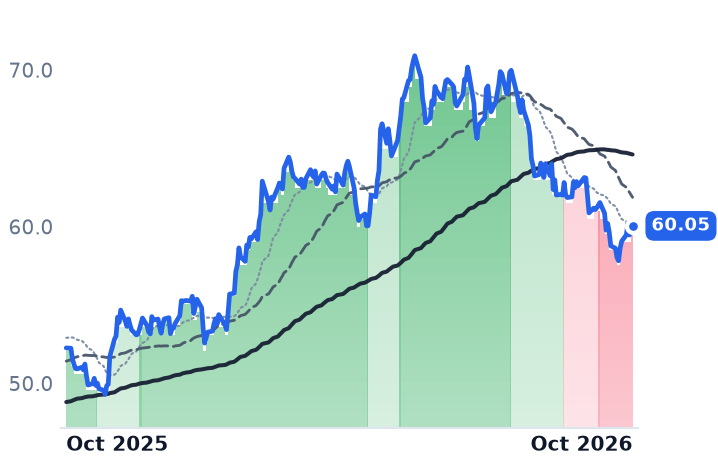
DTM | DT Midstream | Natural Gas Pipelines & Transmission | ⚠️ Emerging Bear | −4.8% | +14.8% |
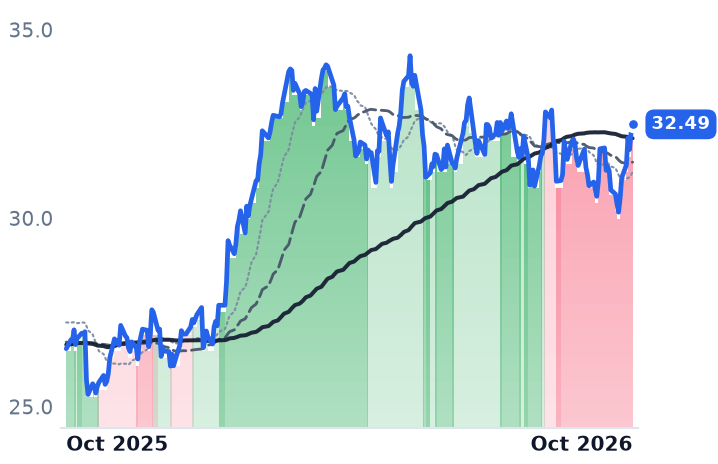
KMI | Kinder Morgan | Natural Gas Pipelines & Transmission | ⚠️ Emerging Bear | +4.3% | +22.4% |
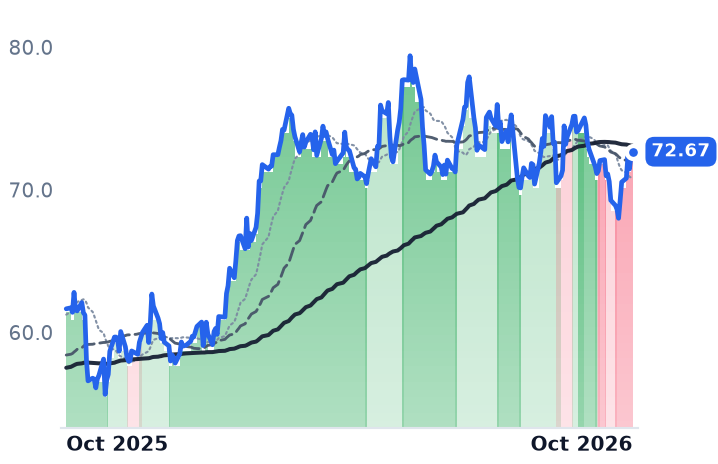
WMB | The Williams Companies | Natural Gas Pipelines & Transmission | 🟢 Cont. Bull | −0.9% | +17.9% |
| Compared against · context, not the story | |||||
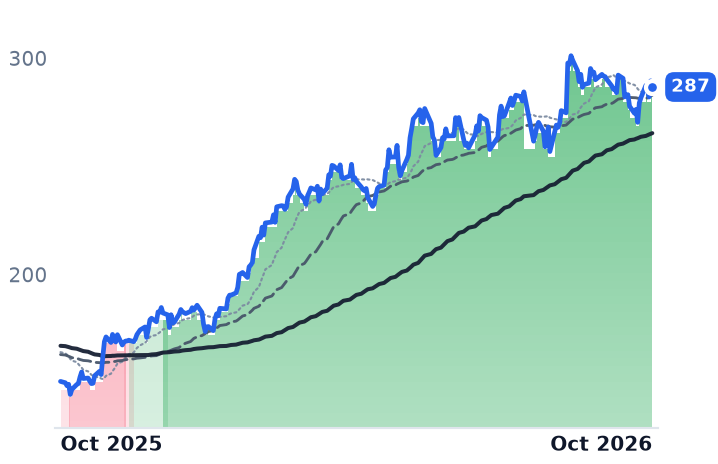
TRGP | Targa Resources | Natural Gas Gathering & Processing | 🟢 Cont. Bull | −1.6% | +90.3% |
ET | Energy Transfer | Natural Gas Pipelines & Transmission | 🟢 Cont. Bull | −6.0% | +30.2% |
TRP | TC Energy | Natural Gas Pipelines & Transmission | ⚠️ Emerging Bear | −3.2% | +14.9% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
DTM | $12.7B | 27.0x | 26.5x | 9.7x | 9.4x | 15.3x | 14.8x | 14.5x | 3.8% |
KMI | $72.3B | 20.8x | 21.1x | 4.0x | 4.0x | 7.3x | 7.2x | 13.0x | 4.4% |
WMB | $88.9B | 28.8x | 29.6x | 7.3x | 7.2x | 9.9x | 9.8x | 15.5x | -0.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
TRGP | $59.6B | 26.4x | 24.7x | 3.6x | 3.1x | 9.7x | 8.6x | 16.6x | 1.2% |
ET | $72.1B | 13.0x | 13.4x | 0.7x | 0.7x | 2.9x | 2.7x | 9.7x | 7.2% |
TRP | $66.2B | 26.6x | 16.9x | 5.8x | 4.1x | 11.2x | 8.0x | 13.8x | 4.4% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
DTM | Revenue | +8.0% | +4.6% | +9.7% |
| EPS | +6.7% | +6.0% | +10.4% | |
KMI | Revenue | +8.6% | +1.6% | +5.1% |
| EPS | +19.7% | −0.1% | +8.9% | |
WMB | Revenue | +8.4% | +14.4% | +15.5% |
| EPS | +15.8% | +6.3% | +16.8% | |
TRGP | Revenue | +11.6% | +25.6% | +13.5% |
| EPS | +32.1% | +9.4% | +21.4% | |
ET | Revenue | +35.3% | +1.9% | +4.9% |
| EPS | +16.7% | +3.6% | +7.4% | |
TRP | Revenue | +6.7% | +4.4% | +5.3% |
| EPS | +7.3% | +5.4% | +6.2% |
Forward fiscal years only. Blank means no analyst coverage for that year.
DT Midstream guided its September quarter below the June one, citing planned maintenance across its gathering network and lower Northeast volumes tied to producer timing, with Haynesville volumes flat at the record 2.2 billion cubic feet a day set in the second quarter. Between late September and 6 October four banks cut their price targets on the Detroit company without changing a rating: JPMorgan to $144 from $154, Jefferies to $145, Mizuho to $147 and Barclays to $142. Nothing in the contracted pipeline book changed.
That split is the whole point of owning this kind of asset, and it is why the de-rating landed here rather than on the shelf generally. A pipeline company sells capacity: the shipper pays a reservation charge for the right to move gas whether it moves any or not. Roughly 70% of DT Midstream's revenue is the Pipeline segment, on long-dated take-or-pay agreements with significant minimum volume commitments. Gathering — wellhead compression, dehydration, treatment — is paid per unit handled, and that is the segment a producer's deferred completions and a maintenance window can reach.
Where the growth halved
Revenue growth of 26.6% and 27.3% in the second half of 2025 became 10.9% and 11.0% in the two 2026 quarters. Net income growth fell further, from 52.1% in the December quarter to 4.7% in June. Consensus has absorbed it: average 2026 operating profit of $788.1m is 0.24% above the 2025 estimate, and earnings per share of $4.678 is 6.7% higher against 15.9% growth the year before. UBS models September-quarter EBITDA of $292m against $305m in the June quarter, ahead of the 29 October report.
The re-contracting that is supposed to fix this is also the exposure. NEXUS, about 1.4 billion cubic feet a day, is "effectively fully contracted today, with some shorter-term contracts that roll every couple of years," chief executive David Slater told investors on 30 July, leaving it "in an enviable position as one of the only pipelines with available capacity out of the Appalachia Basin that's available to be contracted for longer term." The company has commercialized 60% of a $3.4bn organic backlog, more than 80% of it pipeline work, with committed capital near $425m this year. Its newest interstate lines — Guardian, Midwestern and Viking, bought from ONEOK for $1.2bn, earn maximum recourse rates set on cost of service plus an allowed return, a federal proceeding rather than a negotiation.
The shares carry 26.96x trailing earnings, down from 32.5x in early May, and 26.51x forward: under half a turn of expansion priced in. On enterprise value to EBITDA, the lens that survives these companies' depreciation and debt, DT Midstream is at 14.49x, between Kinder Morgan's 12.96x and Williams' 15.55x.
The two that accelerated and fell anyway
Kinder Morgan, which runs some 83,000 miles of pipe and 143 terminals, grew June-quarter revenue 10.8% on a steady 30.1% operating margin, with 65% of 2026 budgeted cash flow under take-or-pay reservation terms. Its backlog slipped to $9.6bn from $10.1bn as more than $650m of projects entered service, at a first-full-year project EBITDA multiple held at about 5.6x — unchanged quarter on quarter — with a weighted average in-service date of the first quarter of 2028. It trades at 20.83x trailing, roughly where it sat in May. Williams posted the best quarter of the three, operating margin widening to 38.7% from 32.0%, and holds the worst valuation and a trailing free-cash-flow yield of minus 0.24% while funding the $5.5bn Momentum purchase and 556 megawatts of behind-the-meter generation under a ten-year, primarily fixed-price power contract: 28.84x trailing, against 34.1x in May.
All three bottomed on 28 September and then rose — Kinder Morgan 6.0%, Williams 5.5%, DT Midstream 1.8% — through the week the 30-year Treasury touched 5.73%, its highest since 2002, while Henry Hub gas rose about 13% on the month to $3.20 per million British thermal units. Over three months the separation is cleaner: DT Midstream down 14.6%, Williams down 3.1%, Kinder Morgan up 1.2%.
So the shelf is carrying two different problems under one label. At Kinder Morgan and Williams the operating results got better and the shares did not, and what the market is marking down is the discount applied to cash flows whose in-service dates fall in 2028 and later; at both, consensus 2026 earnings per share now sits at or slightly below the trailing twelve months. At DT Midstream the markdown is already in the reported numbers, and it is concentrated in the segment whose revenue depends on how many wells a Haynesville or Appalachian producer finished this quarter.
Which leaves one honest question for 29 October: whether the maintenance window was the quarter's problem or merely its most legible part.