

Hecla's Silver Cost Fell to $6 an Ounce on Zinc and Lead Credits as Silver Broke $60
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
Four silver miners just reported the strongest half-year any of them has posted and then gave up between an eighth and nearly a quarter of their market value in thirty sessions. The mines are not the reason.
Hecla's reported cost of producing an ounce of silver actually fell last quarter, because the credits it books for the zinc and lead in the same concentrate grew by $6m. Gross margin reached 64.9%. What broke was the metal price and the 5.24% Treasury yield that competes with holding it.
The pricing splits on jurisdiction and balance sheet: Pan American Silver at 13.98x trailing earnings, Hecla still the group's premium at 34.1x with net cash and US ground. First Majestic raised silver guidance; Endeavour is the one still spending.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
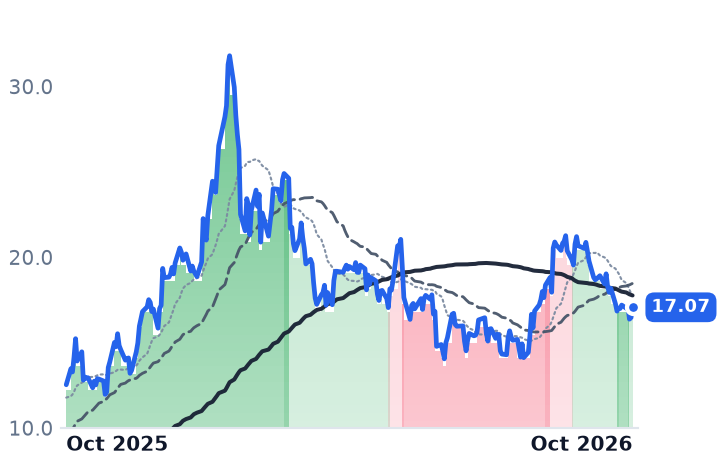
HL | Hecla Mining | Other Precious Metals | ⚠️ Emerging Bear | −16.1% | +36.2% |
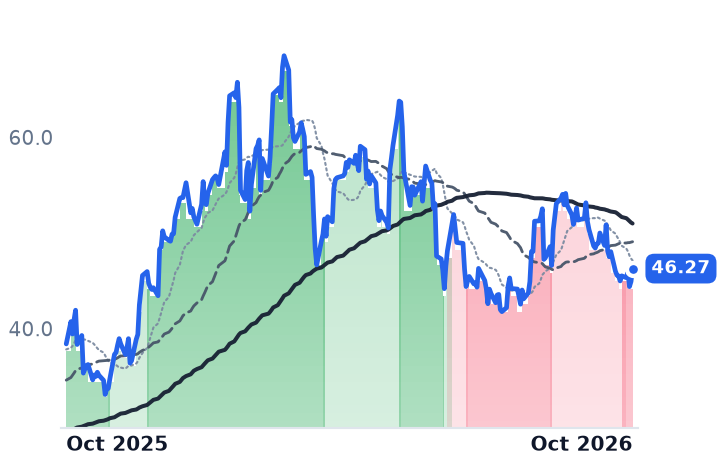
PAAS | Pan American Silver | Gold | 🔴 Cont. Bear | −9.6% | +20.5% |
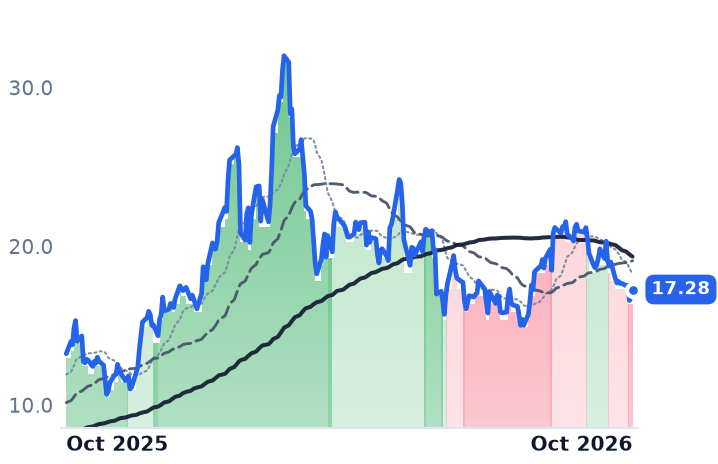
AG | First Majestic Silver | Silver | ⚠️ Emerging Bear | −15.6% | +30.5% |
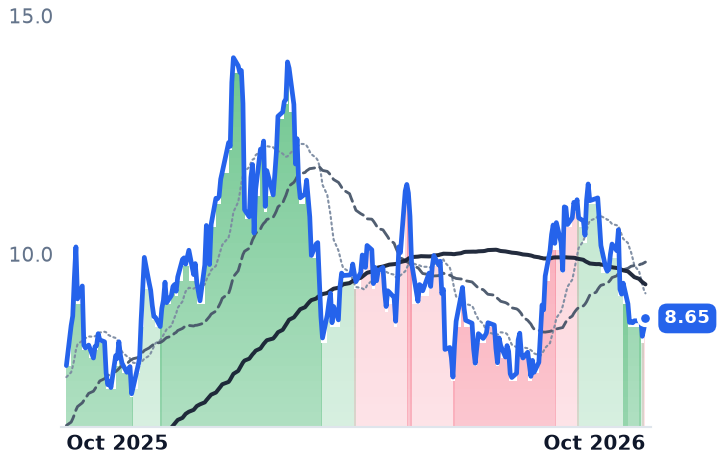
EXK | Endeavour Silver | Silver | ⚠️ Emerging Bear | −19.2% | +12.9% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
HL | $11.4B | 34.1x | 23.5x | 7.1x | 8.1x | 12.7x | 14.4x | 12.2x | 4.5% |
PAAS | $19.5B | 14.0x | 12.8x | 4.5x | 4.2x | 10.2x | 9.5x | 7.8x | 7.9% |
AG | $8.5B | 24.5x | 20.0x | 5.2x | 5.1x | 9.9x | 9.8x | 7.6x | 8.2% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EXK | $2.6B | 37.9x | 11.3x | 3.5x | 3.0x | 12.3x | 10.6x | 12.1x | -1.6% |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
HL | Revenue | +6.5% | +4.5% | +1.7% |
| EPS | +75.0% | +41.3% | −12.5% | |
PAAS | Revenue | +29.6% | +10.9% | −4.5% |
| EPS | +61.0% | +29.2% | −2.4% | |
AG | Revenue | +43.4% | +8.3% | +12.4% |
| EPS | +148.8% | +12.9% | +6.1% | |
EXK | Revenue | +80.2% | +27.7% | −12.2% |
| EPS | −366.8% | +35.8% | −2.1% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Hecla Mining produced its silver last quarter for about $6 an ounce after credits for the zinc and lead that come out of the same rock, and the figure fell from the prior quarter because those credits got bigger — $6m bigger. The Coeur d'Alene, Idaho company's shares are down 18% over thirty sessions.
The drawdown runs across all four US-listed silver primaries, and it has been read as the hard-asset trade cracking at the cost line, where high-grade underground mines are supposed to be most exposed. First-half 2026 was the best half any of the four has reported: margins expanding at Hecla and First Majestic, raised guidance at First Majestic, record cash returns at Pan American Silver. What broke was the price of the metal and the cost of holding it. Silver slipped below $60 an ounce on 7 October, a first for 2026, and the 10-year Treasury yielded 5.24% after the Federal Reserve raised rates a quarter point on 16 September in a unanimous vote.
The zinc market sets the silver cost
Hecla does not sell silver. Greens Creek in Alaska and Lucky Friday in Idaho ship polymetallic concentrates to custom smelters, metal traders and third-party processors, and the company reports cash cost and all-in sustaining cost per silver ounce net of by-product credits. The price of zinc is therefore an input to the disclosed price of an ounce of silver. Zinc was $3,805 a tonne on 9 October, recovering from a six-week low as Western smelter capacity shrinks.
The wedge the smelter takes has inverted. Treatment charges on imported zinc concentrate have slumped to minus $50 a tonne, a record low in Fastmarkets data going back a decade, meaning smelters pay miners to secure feed; the 2026 benchmark Korea Zinc agreed with Teck was $85 a tonne, so the benchmark now understates how favorable concentrate terms have become. The $6.07 also excludes Keno Hill in the Yukon, which has not been determined to be in commercial production yet produced roughly 600,000 ounces and nearly $15m of free cash flow in the quarter, its fifth consecutive positive one.
Hecla's revenue fell on price while ounces rose
The metal lines show where the damage came from. Hecla's silver revenue dropped from $295.6m in the first quarter to $213.7m in the second, while zinc and lead together rose to $61.8m. Output went the other way, up 8% to 4.2 million ounces, with Lucky Friday setting a quarterly record on 31% higher milled grades. Gross margin reached 64.9% against 39.3% a year earlier, and the company ended the quarter with $483m of cash and about $472m net of debt, having closed the sale of the Casa Berardi gold mine to Orezone in March. "Hecla enters the third quarter of 2026 from a position of real strength," chief executive Robert Krcmarov said in the August results release.
Pan American is half a gold miner
Pan American, which mines in Canada, Mexico, Peru, Argentina and Bolivia, delivered attributable silver of 6.47 million ounces at the top of guidance and attributable gold of 165.9 thousand ounces below it, on shortfalls at Jacobina, Shahuindo, Timmins and El Peñón. Its silver segment reported $17.80 an ounce of all-in sustaining cost, its gold segment $1,984. Gross margin compressed from 52.7% to 39.3%. "Pan American delivered another quarter of strong financial results, generating $344 million in Attributable free cash flow," chief executive Michael Steinmann said on 11 August. The company repurchased about 4.4 million shares at an average $51.46, some 11% above the 9 October close.
It also guides 2026 taxes paid of $585m to $635m on an assumed $60 silver price, before Mexico's 7.5% duty on mining EBITDA and a 2.0% silver royalty to Royal Gold.
First Majestic, with four Mexican underground mines and Jerritt Canyon in Nevada, is the purest silver exposure: record revenue of $415.5m, up 57%, 60% of it silver, costs below guidance at $25.68 per payable silver-equivalent ounce, and full-year silver guidance raised to 14.6 million ounces, about a tenth above January. Endeavour Silver is the one still spending, with $56.7m of Terronera sustaining capital inside a $91m budget and trailing free cash flow still negative; its revenue is the only one rising sequentially, to $214.0m, as Terronera and the acquired Kolpa mine in Peru add volume faster than price falls.
What the half-year cannot explain
None of it accounts for the fall.
Three of the four were in uptrends in the first days of October and all four crossed into downtrends within seven sessions, Pan American on the 2nd and Hecla on the 9th, then all four rose between 2.6% and 3.7% on 9 October as the metal rebounded. They sit 33% to 46% below January and February peaks, above their July lows, and higher over twelve months.
Two things the results leave open. Forward consensus sits close to annualized first-half run-rate — Hecla at $1.42bn of 2026 revenue, Pan American at 38% earnings growth — but rests on a silver price that has just been breached on the downside. And the scarcity that drove the rally has been called finished: Deutsche Bank's October note projects an 18.5 million ounce surplus in 2027, with London vault stocks up about 70% in a year. "Peak silver scarcity is clearly in the rear-view mirror," the bank's head of metals research, Daniel Ghali, said. On that reading the market's split pricing is a judgment about jurisdiction and balance sheet: Pan American at 13.98x trailing earnings against roughly 26x at its February peak, Hecla still the premium at 34.1x with net cash and US ground.
The credits that make a $6 ounce possible are, in the end, a position in zinc smelting overcapacity. If treatment charges climb back toward the benchmark while the metal stays where it is, the cheapest ounce in the group gets dearer with nothing changing underground.