

Mid-America's Apartment Rent Recovery Is Real but Too Small to Outrun a 5.2% Treasury
Hypothesis Opus 5 · Research Opus 5 · Writing Opus 5 · Prompt v1.7
An apartment landlord whose lease pricing has improved for three straight quarters has just lost a full turn of its cash-flow valuation in three weeks, and not one word of its guidance changed in between. That gap is the finding.
Mid-America Apartment Communities' blended lease-over-lease spreads went from -1.7% in the fourth quarter of 2025 to +0.7% in the second quarter of 2026, insurance renewed more than 12% cheaper, and expense guidance came down. Meanwhile the 10-year Treasury touched its highest level since April 2002, leaving MAA's $6.12 annualized dividend at a 5.26% yield against 5.23% risk-free.
The operating recovery is genuine at MAA and at Independence Realty, which cut concessions from 54% of new leases in April to about 28% in July. It is also far slower than the discount rate that re-priced both.
| Ticker | Company | Segment | Trend · 13mo | 30D | 1Y |
|---|---|---|---|---|---|
| The subject · what this brief is about | |||||
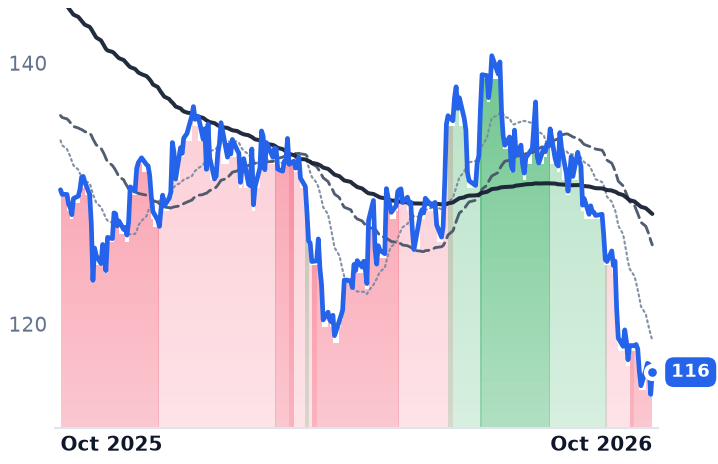
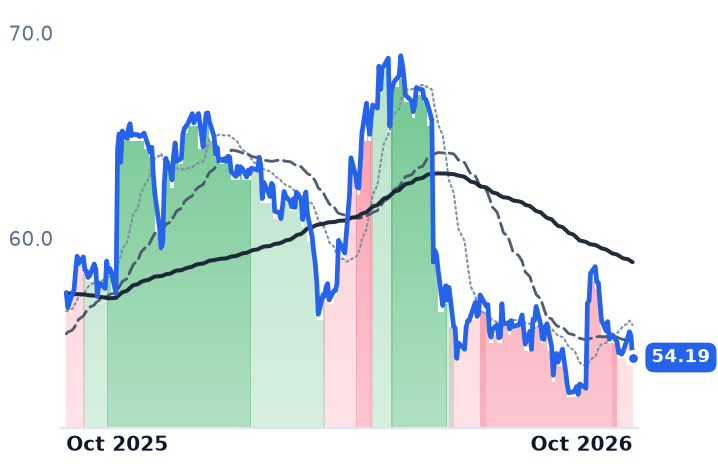
MAA | Mid-America Apartment Communities | Multifamily Apartments | 🔴 Cont. Bear | −8.3% | −10.7% |
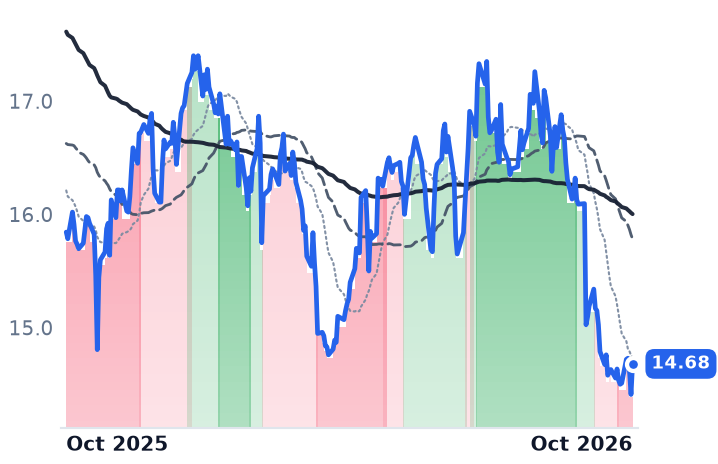
IRT | Independence Realty Trust | Multifamily Apartments | 🌱 Emerging Bull | −2.3% | −7.3% |
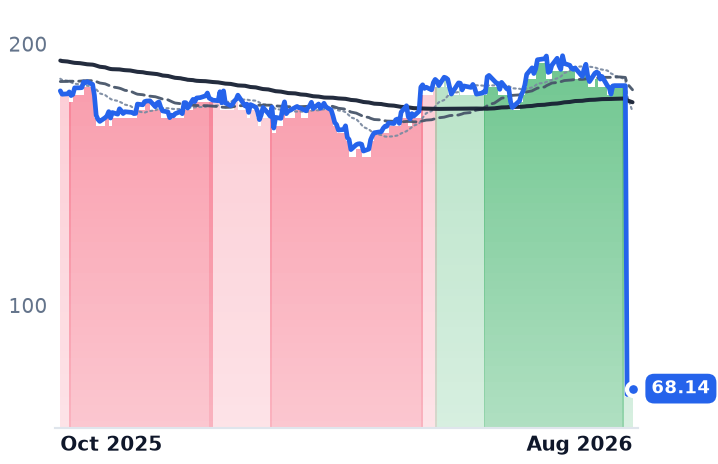
AVB | AvalonBay Communities | Multifamily Apartments | 🟢 Cont. Bull | — | −62.6% |
| Compared against · context, not the story | |||||
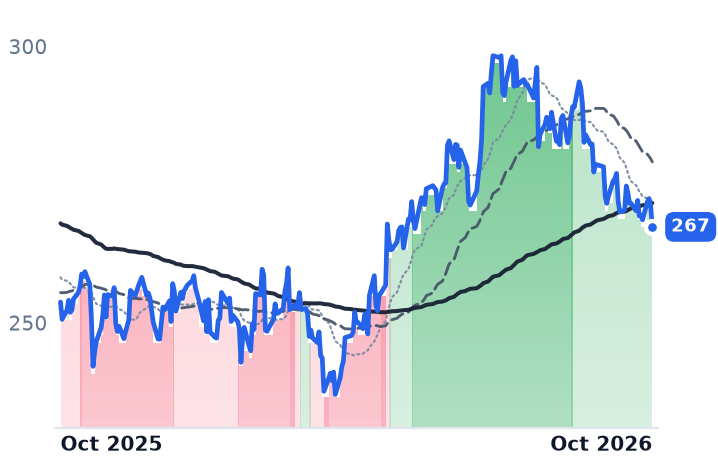
ESS | Essex Property Trust | Multifamily Apartments | 🟢 Cont. Bull | −2.0% | +5.4% |
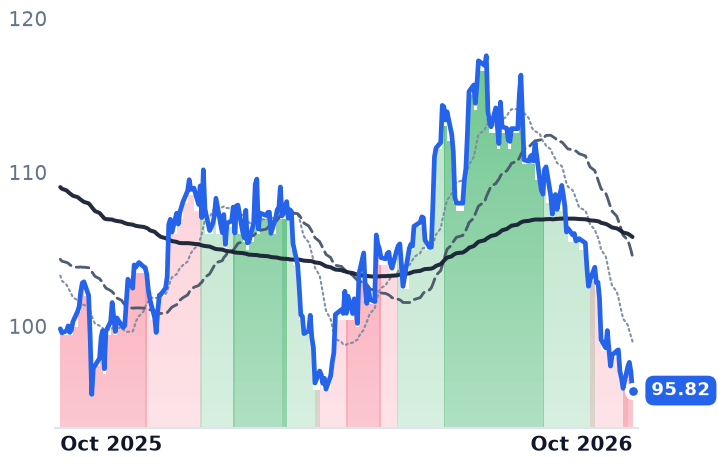
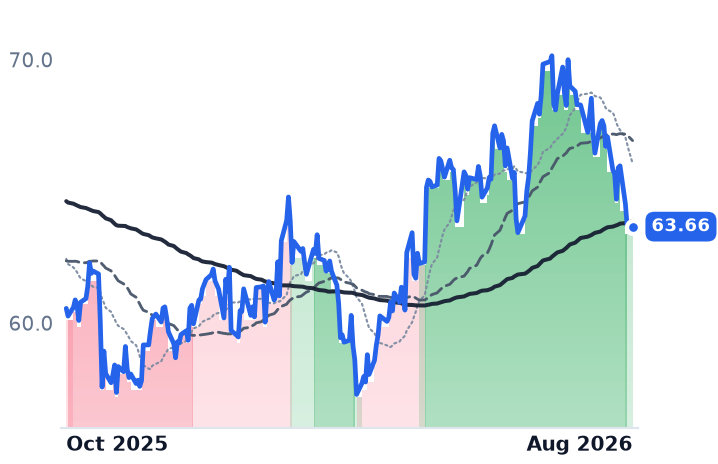
CPT | Camden Property Trust | Multifamily Apartments | 🌱 Emerging Bull | −7.7% | −4.0% |
CSR | Centerspace | Multifamily Apartments | 🔴 Cont. Bear | −4.7% | −5.5% |
EQR | Equity Residential | Multifamily Apartments | 🟢 Cont. Bull | — | +5.1% |
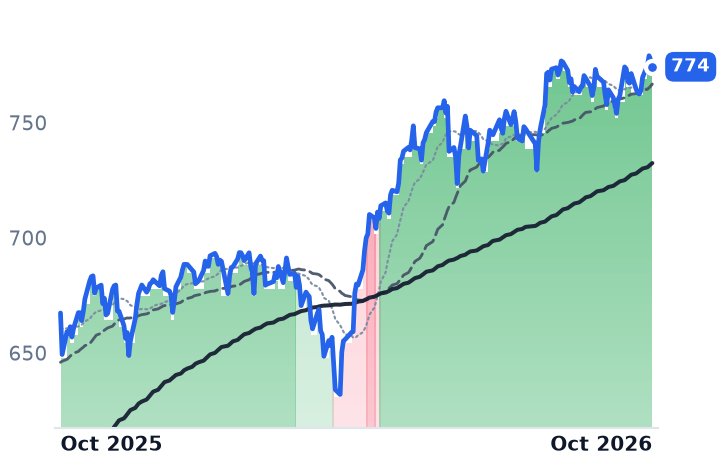
SPY | State Street SPDR S&P 500 ETF Trust | Asset Management | 🟢 Cont. Bull | +1.6% | +16.0% |
12-month price & trend
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
MAA | $13.5B | 34.0x | 31.7x | 6.1x | 6.1x | 12.9x | 12.8x | 15.2x | 4.2% |
IRT | $3.5B | 80.0x | 106.3x | 5.2x | 5.1x | 517.8x | 510.4x | 15.4x | 4.1% |
ESS | $17.2B | 29.9x | 46.4x | 9.0x | 8.8x | 13.0x | 12.7x | 16.6x | 5.6% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
CPT | $10.0B | 32.8x | 87.0x | 6.3x | 6.4x | 28.4x | 28.9x | 13.4x | 6.7% |
CSR | $1.1B | 134.9x | — | 4.1x | 4.2x | 10.8x | 10.9x | 12.5x | 6.2% |
AVB | $26.3B | 25.2x | 30.5x | 8.5x | 8.5x | 16.2x | 16.1x | 18.8x | 6.1% |
| Ticker | Mkt cap | P/E | P/E fwd | P/S | P/S fwd | P/GP | P/GP fwd | EV/EBITDA | FCF yld |
|---|---|---|---|---|---|---|---|---|---|
EQR | $23.9B | 25.2x | 45.9x | 7.7x | 7.6x | 16.6x | 16.3x | 13.9x | 5.3% |
SPY | $773.0B | — | — | — | — | — | — | — | — |
Consensus projections
| Ticker | FY2026E | FY2027E | FY2028E | |
|---|---|---|---|---|
MAA | Revenue | +0.9% | +2.4% | +3.3% |
| EPS | −11.4% | −14.3% | +10.5% | |
IRT | Revenue | +2.5% | +17.7% | −8.9% |
| EPS | −25.7% | +32.6% | −10.6% | |
ESS | Revenue | +3.9% | +3.2% | +4.0% |
| EPS | −45.2% | +5.1% | +9.0% | |
CPT | Revenue | −2.0% | +0.9% | +4.7% |
| EPS | −53.4% | +2.8% | +12.4% | |
CSR | Revenue | −3.0% | +3.4% | −40.4% |
| EPS | −156.8% | −33.9% | −118.1% | |
AVB | Revenue | +2.8% | +4.3% | +5.3% |
| EPS | −18.5% | −11.3% | +7.5% | |
EQR | Revenue | +2.2% | +3.3% | +3.5% |
| EPS | −39.6% | +8.6% | +16.8% |
Forward fiscal years only. Blank means no analyst coverage for that year.
Mid-America Apartment Communities has spent three weeks losing a full turn of its valuation without changing a word of its guidance. The Sunbelt apartment owner, which held interests in roughly 102,772 units across 16 states and the District of Columbia, closed at $124.82 on 16 September and $116.31 on 9 October. Against full-year Core funds from operations guidance of $8.35 to $8.71 a share, unchanged through both prints, the midpoint of $8.53 puts the shares at 13.6 times that cash-flow measure, down from 14.6 times — arithmetic from the guidance and the closes, not a disclosed figure.
September's improving lease data was read as the start of an apartment recovery. What moved was the denominator. The Federal Reserve raised its target range a quarter point to 3.75%-4.00% on 16 September, its first increase in more than three years, and the 10-year Treasury touched 5.349% on 5 October, its highest since April 2002, easing to 5.23% by 9 October. MAA's quarterly dividend of $1.53 a share, $6.12 annualized, is a 5.26% yield on that close. The risk-free note pays essentially the same for none of the leverage, and September's 54-point rise in the 10-year was 49 points of real yields with almost no inflation component. The FTSE Nareit All Equity REITs index fell 5.7% that month.
The spread that turned three quarters running
The rent roll is genuinely better. MAA's blended lease-over-lease spreads ran -1.7% in the fourth quarter of 2025, -0.3% in the first quarter of 2026 and +0.7% in the second, composed of new leases still 5.3% below the expiring rent against renewals up 5.2%, on 95.3% occupancy. "We expect third quarter blended pricing to be better than the second quarter, a trend not seen in the last four years," chief operating officer Tim Argo told analysts on 29 July 2026. At Bank of America's global real estate conference on 16 September the company said third-quarter blended rates were running three to five percentage points better year on year, renewals near 4.8%, with new-lease pricing still negative and deliveries still pressing Austin, Phoenix and Nashville. The cost side helps too: insurance premiums renewed more than 12% lower, a third straight annual decline, and same-store expense growth guidance came down to about 1.75%.
None of it has reached the income statement.
Revenue grew 0.95% year on year in the second quarter while operating income fell 7.0%, and the annual operating margin has compressed from 32.1% in 2023 to 28.0% in 2025. Consensus has earnings per share falling to $3.66 this year and $3.14 next.
Independence Realty is withdrawing the free rent
The smaller case is cleaner because concessions are visible. Independence Realty Trust, a $3.46bn owner of apartment communities in non-gateway markets including Atlanta, Louisville, Memphis and Raleigh, improved blended rent growth from +0.7% in the first quarter to +1.3% in the second and +2.5% in July, and cut concession use from 54% of new leases in April to roughly 28% in July. Weeks of free rent never show up in asking rent; they show up in effective rent, which is what the owner banks. Its renovation program turned 600 units in the quarter at a 16.4% weighted average return for $279 of extra monthly rent against unrenovated comparables.
IRT trades at 1.03 times book against MAA's 2.48 times, yet its 15.4 times trailing enterprise value to EBITDA is indistinguishable from MAA's 15.2 times: no discount for class-B assets, no premium for the concession reversal. Its own shares are also partly an arbitrage now, with Centerspace holders voting on 10 November on a merger paying 3.800 IRT shares for each of theirs.
What the recovery can and cannot repair
The operating inflection explains none of the three-week de-rating and the discount rate explains most of it: guidance did not move, the 10-year did. What the lease data does establish is that the Sunbelt supply wave is passing through. Multifamily starts in buildings of five units or more fell to 344,000 annualized in August, down 22.5% in a month, and completions were 25.6% lower year on year in July at 329,000. That pipeline is contracted and cannot be undone, but it lands in 2027 and 2028, while the rate move landed in September.
The overhang in between is local and live. Austin ended the third quarter with 13.5% vacancy and half of conventional properties discounting to new residents; Phoenix carried 12% vacancy with 61% of listings offering concessions. That is why the split runs by geography rather than by asset quality: MAA fell 14.4% over the twelve months to 8 October and Camden Property Trust 7.0%, while Essex Property Trust, whose portfolio sits on the West Coast where little was permitted, rose 2.0% and is the only one of these apartment owners still in an uptrend.
Mid-America controls one of the two clocks running against it. Third-quarter results are due on 28 October, and they can only answer whether blended pricing kept climbing; the note that now pays what the dividend pays answers to nobody in Memphis.